Global Integrated/Hybrid Operating Room Market by Equipment (Diagnostic Imaging Systems, Operating Room Fixtures, Other Equipment) Market by Application (Cardiovascular Surgery, Neurosurgery, Thoracic Surgery, Orthopedic Surgery, Other Applications) Market by End-User (Hospital and Surgical Centers, Outpatient Surgical Centers, Other End-Users), by Geography
GLOBAL INTEGRATED/HYBRID OPERATING ROOM MARKET OVERVIEW
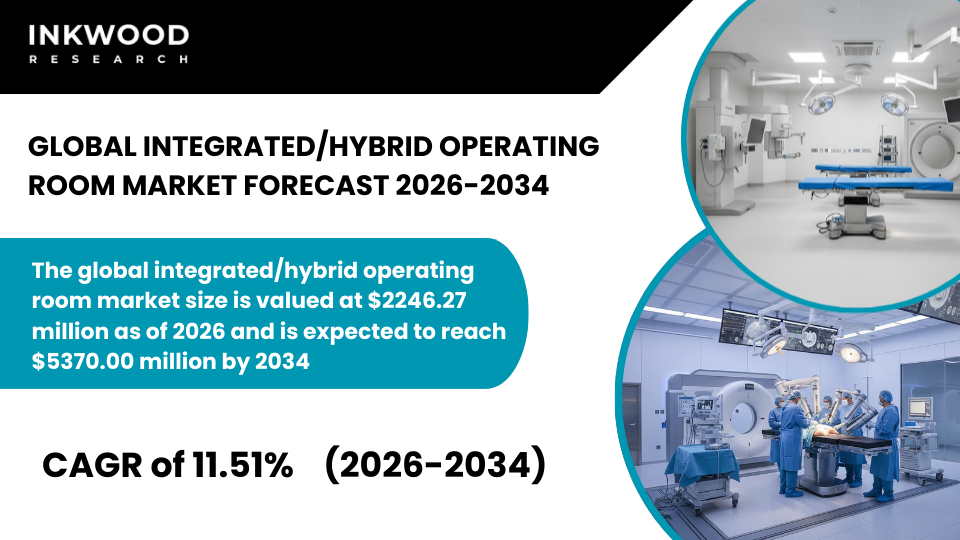
The global integrated/hybrid operating room market size is valued at $2246.27 million as of 2026 and is expected to reach $5370.00 million by 2034, growing at a CAGR of 11.51% during the forecast period 2026-2034. The base year considered for the study is 2025, and the forecast period is between 2026 and 2034. The market study has also analyzed the crisis impact on the integrated/hybrid operating room market qualitatively as well as quantitatively.
An integrated/hybrid operating room represents a sophisticated surgical environment where advanced diagnostic imaging systems seamlessly merge with surgical instruments and audiovisual display systems. These specialized facilities enable surgeons to perform complex, minimally invasive procedures while accessing real-time imaging guidance. The hybrid operating rooms market growth stems from the ability to conduct multi-disciplinary procedures without patient transfer between diagnostic and surgical suites.
Modern hybrid OR systems integrate angiography systems, CT scanners, and MRI scanners directly into the surgical workspace. This integration significantly reduces procedure time and enhances patient outcomes. Furthermore, these advanced facilities support a broad spectrum of surgical specialties, including cardiovascular surgery, neurosurgery, and orthopedic procedures.
Healthcare institutions worldwide are rapidly adopting hybrid operating room systems to meet growing demand for minimally invasive surgical techniques. Hospitals recognize that integrated hybrid OR systems deliver superior clinical outcomes while optimizing workflow efficiency. The shift toward image-guided surgery continues to accelerate market expansion globally.
Additionally, technological advances in robotic-assisted surgical systems and artificial intelligence are transforming hybrid OR capabilities. Tertiary care hospitals lead adoption due to high procedure volumes and available capital investment. Moreover, the healthcare hybrid operating rooms market benefits from increasing patient preference for less invasive treatment options with shorter recovery periods.
To Know More About This Report, Request a Free Sample Copy
GROWTH ENABLERS
Key enablers of the global integrated/hybrid operating room market growth:
- Rising volume of minimally invasive and image-guided surgeries is accelerating demand for hybrid ORs
- Hospitals’ focus on improving surgical outcomes and reducing procedure time is supporting adoption
- Technological advances in intraoperative imaging and digital OR integration are enhancing clinical value
- Increasing investments in smart hospital infrastructure are fueling market expansion
- Increasing investments in smart hospital infrastructure continue to fuel market expansion across developed and emerging economies. Healthcare facilities are modernizing their surgical capabilities to remain competitive in an evolving medical landscape. Smart hospital initiatives emphasize interconnected systems that enhance operational efficiency and patient care quality.
- Consequently, hospitals are allocating substantial capital budgets toward hybrid operating room integration platforms. These investments extend beyond equipment purchases to include infrastructure upgrades, staff training, and ongoing technical support. Government healthcare programs in various countries are providing funding support for hospital modernization projects.
- Moreover, private hospital networks recognize that advanced surgical facilities attract top medical talent and high-value patient referrals. The convergence of value-based care models and patient outcome metrics drives institutions to invest in technologies that demonstrably improve results.
GROWTH RESTRAINTS
Key growth restraining factors of the global integrated/hybrid operating room market:
- High capital and installation costs limit adoption among small and medium-sized hospitals
- Complexity of system integration requires specialized technical and clinical training
- Space and infrastructure requirements make retrofitting existing ORs challenging
- Long procurement and approval cycles delay purchasing decisions in public healthcare systems
- Long procurement and approval cycles significantly delay purchasing decisions in public healthcare systems worldwide. Public hospitals must navigate complex bureaucratic processes involving multiple stakeholders and approval levels. Budget allocation for hybrid operating rooms requires justification through detailed cost-benefit analyses and competitive bidding procedures. Consequently, the timeline from initial consideration to actual installation can extend beyond two years in many jurisdictions.
- Regulatory compliance and safety certifications add further delays to the procurement process. Additionally, public sector purchasing often operates on fixed annual budget cycles with limited flexibility for large capital expenditures. Political considerations and competing healthcare priorities can further postpone investment decisions. These extended timelines create uncertainty for manufacturers and slow overall market penetration in government-funded healthcare facilities.
KEY MARKET TRENDS
Global Integrated/Hybrid Operating Room Industry | Top Trends
- Modern hybrid OR systems now seamlessly combine real-time imaging modalities with precision surgical navigation platforms. This integration allows surgeons to visualize anatomical structures with unprecedented clarity during complex procedures. The fusion of angiography systems and CT scanners with navigation software has become essential for cardiovascular surgery and neurosurgery applications. Consequently, manufacturers are developing turnkey solutions that eliminate compatibility concerns between different system components. According to Siemens Healthineers, their latest hybrid OR solutions feature fully integrated imaging and navigation capabilities designed specifically for minimally invasive procedures.
- Healthcare facilities increasingly prefer modular hybrid operating room systems that allow phased implementation based on budget availability. These flexible designs enable hospitals to start with core functionality and expand capabilities over time. Modular approaches significantly lower the entry barrier for mid-sized hospitals previously unable to afford comprehensive hybrid OR installations. Furthermore, scalable systems provide upgrade pathways as new technologies emerge without requiring complete facility replacement. This trend addresses one of the primary market restraints by making advanced surgical capabilities accessible to broader healthcare segments.
- AI-powered systems are revolutionizing how hybrid operating rooms manage complex surgical workflows and resource allocation. These intelligent platforms optimize equipment positioning, lighting adjustments, and imaging parameters automatically based on procedure type. Machine learning algorithms analyze historical surgical data to predict equipment needs and potential complications. As a result, surgical teams experience reduced setup times and fewer workflow interruptions during critical procedures. Major manufacturers, including GE Healthcare, are incorporating AI-driven workflow optimization into their latest hybrid OR platforms.
- Medical equipment suppliers now provide comprehensive turnkey packages that encompass every aspect of hybrid OR implementation. These solutions include space planning, architectural integration, equipment installation, staff training, and ongoing maintenance services. Turnkey approaches simplify the complex process of hybrid OR adoption for hospital administrators and procurement teams. Additionally, comprehensive service agreements ensure optimal system performance throughout the equipment lifecycle. This trend reflects market maturation as vendors shift from simply selling equipment to delivering complete clinical solutions with guaranteed outcomes.
MARKET SEGMENTATION
Market Segmentation – Equipment, Application, and End-User –
Market by Equipment:
- Diagnostic Imaging Systems
- Diagnostic imaging systems form the technological cornerstone of any hybrid operating room configuration. These advanced systems include angiography systems, MRI scanners, CT scanners, and other specialized imaging modalities essential for real-time surgical guidance. Angiography systems particularly dominate cardiovascular surgery applications where continuous vessel visualization proves critical during complex interventions.
- The ability to capture high-resolution images without patient repositioning represents a defining advantage that drives demand across surgical specialties. Moreover, manufacturers continuously enhance image quality while reducing radiation exposure to protect both patients and surgical teams. Demand for diagnostic imaging systems within hybrid ORs accelerates as minimally invasive techniques expand into new surgical domains.
- Recent product launches demonstrate significant technological advancement, including mobile C-arm systems with 3D imaging capabilities. These innovations enable surgeons to perform increasingly complex procedures with greater precision and confidence. Regulatory approvals from bodies like the FDA for advanced imaging platforms further validate clinical efficacy and safety. Consequently, this sub-segment supports overall hybrid operating rooms market growth by enabling capabilities previously impossible in conventional surgical settings.
- Angiography Systems
- MRI Systems
- CT Scanners
- Other Diagnostic Imaging Systems
- Operating Room Fixtures
- Operating Tables
- Operating Room Lights
- Surgical Booms
- Other Operating Room Fixtures
- Other Equipment
Market by Application:
- Cardiovascular Surgery
- Neurosurgery
- Thoracic Surgery
- Orthopedic Surgery
- Other Applications
Market by End-User:
- Hospital and Surgical Centers
- Outpatient Surgical Centers
- Other End-Users
Geographical Study Based on Four Major Regions:
- North America: The United States and Canada
- Europe: The United Kingdom, Germany, France, Italy, Spain, Poland, Belgium, and Rest of Europe
- Asia-Pacific: China, India, Japan, Australia & New Zealand, South Korea, Thailand, Indonesia, Vietnam, and Rest of Asia-Pacific
- China’s integrated hybrid operating room market demonstrates remarkable expansion driven by government healthcare reform initiatives and rapidly modernizing hospital infrastructure. The country’s ambitious Healthy China 2030 initiative prioritizes upgrading medical facilities with advanced surgical technologies.
- Major tertiary hospitals in urban centers like Beijing, Shanghai, and Guangzhou are leading the adoption of comprehensive hybrid OR systems. Furthermore, China’s growing middle class demands access to world-class medical care, pushing healthcare providers to invest in cutting-edge surgical capabilities.
- Domestic manufacturers are emerging alongside international players, increasing competitive intensity and driving down equipment costs. The market benefits from strong government support for medical device innovation and streamlined regulatory pathways for advanced surgical systems.
- Rest of World: Latin America, the Middle East & Africa
Our market research reports offer an in-depth analysis of individual country-level market size and growth statistics. We cover the segmentation analysis, key growth factors, and macro-economic trends within the integrated/hybrid operating room market, providing detailed insights into –
MAJOR PLAYERS
The major players in the global integrated/hybrid operating room market are:
- Stryker Corporation
- GE Healthcare
- Siemens AG
- Koninklijke Philips NV
- Getinge AB
Key strategies adopted by some of these companies:
- In April 2024, Stryker completed its acquisition of mfPHD, a leader in modular stainless steel wall systems for hospitals and ambulatory surgery centers. This strategic acquisition enables Stryker to offer comprehensive turnkey operating room solutions and accelerates the development of embedded technologies for intelligent hybrid operating rooms.
- In September 2024, Getinge finalized its acquisition of Paragonix Technologies for approximately $477 million. This acquisition strengthens Getinge’s cardiovascular and organ transplant capabilities, particularly enhancing solutions for advanced organ preservation during complex cardiovascular procedures performed in hybrid operating rooms.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Equipment, Application, and End-User |
| Geographies Analyzed | North America, Europe, Asia-Pacific, Rest of World |
| Companies Analyzed | Arthrex Inc, Barco NV, Carl Zeiss Meditec Group, CONMED Corporation, Drägerwerk AG & Co KGaA, Fisher & Paykel Healthcare Corporation Limited, GE Healthcare, Getinge AB, Integra LifeSciences Holdings Corporation, KARL STORZ SE & Co KG, Koninklijke Philips NV, Olympus Corporation, Siemens AG, Smith & Nephew PLC, Stryker Corporation |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- HOSPITALS ARE INCREASINGLY INVESTING IN HYBRID ORS TO ENABLE MULTI-DISCIPLINARY PROCEDURES WITHIN A SINGLE SURGICAL ENVIRONMENT
- CARDIOVASCULAR AND NEUROSURGERY ACCOUNT FOR THE LARGEST SHARE OF HYBRID OR DEPLOYMENTS DUE TO IMAGING-INTENSIVE WORKFLOWS
- TERTIARY AND QUATERNARY CARE HOSPITALS DOMINATE DEMAND BECAUSE OF HIGH PROCEDURE VOLUMES AND CAPITAL AVAILABILITY
- EMERGING MARKETS ARE SHIFTING FROM CONVENTIONAL ORS TO SEMI-INTEGRATED SYSTEMS AS A STEPPING STONE TO FULL HYBRID ROOMS
MARKET DYNAMICS
- KEY DRIVERS
- RISING VOLUME OF MINIMALLY INVASIVE AND IMAGE-GUIDED SURGERIES IS ACCELERATING DEMAND FOR HYBRID ORS
- HOSPITALS’ FOCUS ON IMPROVING SURGICAL OUTCOMES AND REDUCING PROCEDURE TIME IS SUPPORTING ADOPTION
- TECHNOLOGICAL ADVANCES IN INTRAOPERATIVE IMAGING AND DIGITAL OR INTEGRATION ARE ENHANCING CLINICAL VALUE
- INCREASING INVESTMENTS IN SMART HOSPITAL INFRASTRUCTURE ARE FUELING MARKET EXPANSION
- KEY RESTRAINTS
- HIGH CAPITAL AND INSTALLATION COSTS LIMIT ADOPTION AMONG SMALL AND MEDIUM-SIZED HOSPITALS
- COMPLEXITY OF SYSTEM INTEGRATION REQUIRES SPECIALIZED TECHNICAL AND CLINICAL TRAINING
- SPACE AND INFRASTRUCTURE REQUIREMENTS MAKE RETROFITTING EXISTING ORS CHALLENGING
- LONG PROCUREMENT AND APPROVAL CYCLES DELAY PURCHASING DECISIONS IN PUBLIC HEALTHCARE SYSTEMS
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- INTEGRATION OF ADVANCED IMAGING WITH SURGICAL NAVIGATION IS BECOMING A STANDARD FEATURE
- MODULAR AND SCALABLE HYBRID OR DESIGNS ARE GAINING TRACTION TO REDUCE INITIAL INVESTMENT
- ARTIFICIAL INTELLIGENCE ENABLED WORKFLOW MANAGEMENT IS IMPROVING SURGICAL EFFICIENCY
- VENDORS ARE OFFERING TURNKEY SOLUTIONS INCLUDING DESIGN, INSTALLATION, AND LIFECYCLE SUPPORT
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR NORTH AMERICA
- GROWTH PROSPECT MAPPING FOR EUROPE
- GROWTH PROSPECT MAPPING FOR ASIA-PACIFIC
- GROWTH PROSPECT MAPPING FOR REST OF WORLD
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- COMPONENT MANUFACTURERS
- IMAGING SYSTEM SUPPLIERS
- OR INTEGRATION PROVIDERS
- SOFTWARE PLATFORM DEVELOPERS
- SYSTEM INTEGRATORS
- HOSPITAL END-USERS
- KEY BUYING CRITERIA
- IMAGING COMPATIBILITY
- SYSTEM INTEROPERABILITY
- TOTAL COST OWNERSHIP
- AFTER SALES SUPPORT
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
INTEGRATED/HYBRID OPERATING ROOM MARKET BY EQUIPMENT
- DIAGNOSTIC IMAGING SYSTEMS
- ANGIOGRAPHY SYSTEMS
- MRI SYSTEMS
- CT SCANNERS
- OTHER DIAGNOSTIC IMAGING SYSTEMS
- OPERATING ROOM FIXTURES
- OPERATING TABLES
- OPERATING ROOM LIGHTS
- SURGICAL BOOMS
- OTHER OPERATING ROOM FIXTURES
- OTHER EQUIPMENT
- DIAGNOSTIC IMAGING SYSTEMS
INTEGRATED/HYBRID OPERATING ROOM MARKET BY APPLICATION
- CARDIOVASCULAR SURGERY
- NEUROSURGERY
- THORACIC SURGERY
- ORTHOPEDIC SURGERY
- OTHER APPLICATIONS
INTEGRATED/HYBRID OPERATING ROOM MARKET BY END-USER
- HOSPITAL AND SURGICAL CENTERS
- OUTPATIENT SURGICAL CENTERS
- OTHER END-USERS
GEOGRAPHICAL ANALYSIS
- NORTH AMERICA
- MARKET SIZE & ESTIMATES
- NORTH AMERICA MARKET DRIVERS
- NORTH AMERICA MARKET CHALLENGES
- KEY PLAYERS IN NORTH AMERICA INTEGRATED/HYBRID OPERATING ROOM MARKET
- COUNTRY ANALYSIS
- UNITED STATES
- UNITED STATES MARKET SIZE & OPPORTUNITIES
- CANADA
- CANADA MARKET SIZE & OPPORTUNITIES
- UNITED STATES
- EUROPE
- MARKET SIZE & ESTIMATES
- EUROPE MARKET DRIVERS
- EUROPE MARKET CHALLENGES
- KEY PLAYERS IN EUROPE INTEGRATED/HYBRID OPERATING ROOM MARKET
- COUNTRY ANALYSIS
- GERMANY
- GERMANY MARKET SIZE & OPPORTUNITIES
- UNITED KINGDOM
- UNITED KINGDOM MARKET SIZE & OPPORTUNITIES
- FRANCE
- FRANCE MARKET SIZE & OPPORTUNITIES
- ITALY
- ITALY MARKET SIZE & OPPORTUNITIES
- SPAIN
- SPAIN MARKET SIZE & OPPORTUNITIES
- BELGIUM
- BELGIUM MARKET SIZE & OPPORTUNITIES
- POLAND
- POLAND MARKET SIZE & OPPORTUNITIES
- REST OF EUROPE
- REST OF EUROPE MARKET SIZE & OPPORTUNITIES
- GERMANY
- ASIA-PACIFIC
- MARKET SIZE & ESTIMATES
- ASIA-PACIFIC MARKET DRIVERS
- ASIA-PACIFIC MARKET CHALLENGES
- KEY PLAYERS IN ASIA-PACIFIC INTEGRATED/HYBRID OPERATING ROOM MARKET
- COUNTRY ANALYSIS
- CHINA
- CHINA MARKET SIZE & OPPORTUNITIES
- INDIA
- INDIA MARKET SIZE & OPPORTUNITIES
- JAPAN
- JAPAN MARKET SIZE & OPPORTUNITIES
- AUSTRALIA & NEW ZEALAND
- AUSTRALIA & NEW ZEALAND MARKET SIZE & OPPORTUNITIES
- SOUTH KOREA
- SOUTH KOREA MARKET SIZE & OPPORTUNITIES
- THAILAND
- THAILAND MARKET SIZE & OPPORTUNITIES
- INDONESIA
- INDONESIA MARKET SIZE & OPPORTUNITIES
- VIETNAM
- VIETNAM MARKET SIZE & OPPORTUNITIES
- REST OF ASIA-PACIFIC
- REST OF ASIA-PACIFIC MARKET SIZE & OPPORTUNITIES
- CHINA
- REST OF WORLD
- MARKET SIZE & ESTIMATES
- REST OF WORLD MARKET DRIVERS
- REST OF WORLD MARKET CHALLENGES
- KEY PLAYERS IN REST OF WORLD INTEGRATED/HYBRID OPERATING ROOM MARKET
- REGIONAL ANALYSIS
- LATIN AMERICA
- LATIN AMERICA MARKET SIZE & OPPORTUNITIES
- MIDDLE EAST & AFRICA
- MIDDLE EAST & AFRICA MARKET SIZE & OPPORTUNITIES
- LATIN AMERICA
- NORTH AMERICA
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- ARTHREX INC
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- BARCO NV
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- CARL ZEISS MEDITEC GROUP
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- CONMED CORPORATION
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- DRAGERWERK AG & CO KGAA
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- FISHER & PAYKEL HEALTHCARE CORPORATION LIMITED
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- GE HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- GETINGE AB
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- INTEGRA LIFESCIENCES HOLDINGS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- KARL STORZ SE & CO KG
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- KONINKLIJKE PHILIPS N.V
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- OLYMPUS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- SIEMENS AG
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- SMITH & NEPHEW PLC
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- STRYKER CORPORATION
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- ARTHREX INC
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – INTEGRATED/HYBRID OPERATING ROOM
TABLE 2: INTEGRATED/HYBRID OPERATING ROOM MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY EQUIPMENT, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY EQUIPMENT, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: DIAGNOSTIC IMAGING SYSTEMS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: DIAGNOSTIC IMAGING SYSTEMS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: MARKET BY DIAGNOSTIC IMAGING SYSTEMS, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: MARKET BY DIAGNOSTIC IMAGING SYSTEMS, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: ANGIOGRAPHY SYSTEMS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: ANGIOGRAPHY SYSTEMS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: MRI SYSTEMS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 12: MRI SYSTEMS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 13: CT SCANNERS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 14: CT SCANNERS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 15: OTHER DIAGNOSTIC IMAGING SYSTEMS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 16: OTHER DIAGNOSTIC IMAGING SYSTEMS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 17: OPERATING ROOM FIXTURES MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 18: OPERATING ROOM FIXTURES MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 19: MARKET BY OPERATING ROOM FIXTURES, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 20: MARKET BY OPERATING ROOM FIXTURES, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 21: OPERATING TABLES MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 22: OPERATING TABLES MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 23: OPERATING ROOM LIGHTS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 24: OPERATING ROOM LIGHTS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 25: SURGICAL BOOMS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 26: SURGICAL BOOMS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 27: OTHER OPERATING ROOM FIXTURES MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 28: OTHER OPERATING ROOM FIXTURES MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 29: OTHER EQUIPMENT MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 30: OTHER EQUIPMENT MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 31: MARKET BY APPLICATION, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 32: MARKET BY APPLICATION, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 33: CARDIOVASCULAR SURGERY MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 34: CARDIOVASCULAR SURGERY MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 35: NEUROSURGERY MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 36: NEUROSURGERY MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 37: THORACIC SURGERY MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 38: THORACIC SURGERY MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 39: ORTHOPEDIC SURGERY MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 40: ORTHOPEDIC SURGERY MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 41: OTHER APPLICATIONS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 42: OTHER APPLICATIONS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 43: MARKET BY END-USER, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 44: MARKET BY END-USER, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 45: HOSPITAL AND SURGICAL CENTERS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 46: HOSPITAL AND SURGICAL CENTERS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 47: OUTPATIENT SURGICAL CENTERS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 48: OUTPATIENT SURGICAL CENTERS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 49: OTHER END-USERS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 50: OTHER END-USERS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 51: MARKET BY GEOGRAPHICAL ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 52: MARKET BY GEOGRAPHICAL ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 53: NORTH AMERICA MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 54: NORTH AMERICA MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 55: KEY PLAYERS OPERATING IN THE NORTH AMERICAN MARKET
TABLE 56: EUROPE MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 57: EUROPE MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 58: KEY PLAYERS OPERATING IN THE EUROPEAN MARKET
TABLE 59: ASIA-PACIFIC MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 60: ASIA-PACIFIC MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 61: KEY PLAYERS OPERATING IN THE ASIA-PACIFIC MARKET
TABLE 62: REST OF WORLD MARKET, REGIONAL ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 63: REST OF WORLD MARKET, REGIONAL ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 64: KEY PLAYERS OPERATING IN THE REST OF WORLD MARKET
TABLE 65: LIST OF MERGERS & ACQUISITIONS
TABLE 66: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 67: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 68: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: KEY MARKET TRENDS
FIGURE 2: PORTER’S FIVE FORCES ANALYSIS
FIGURE 3: GROWTH PROSPECT MAPPING FOR NORTH AMERICA
FIGURE 4: GROWTH PROSPECT MAPPING FOR EUROPE
FIGURE 5: GROWTH PROSPECT MAPPING FOR ASIA-PACIFIC
FIGURE 6: GROWTH PROSPECT MAPPING FOR REST OF WORLD
FIGURE 7: MARKET MATURITY ANALYSIS
FIGURE 8: MARKET CONCENTRATION ANALYSIS
FIGURE 9: VALUE CHAIN ANALYSIS
FIGURE 10: KEY BUYING CRITERIA
FIGURE 11: SEGMENT GROWTH POTENTIAL, BY EQUIPMENT, IN 2025
FIGURE 12: DIAGNOSTIC IMAGING SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY DIAGNOSTIC IMAGING SYSTEMS, IN 2025
FIGURE 14: ANGIOGRAPHY SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: MRI SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: CT SCANNERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: OTHER DIAGNOSTIC IMAGING SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: OPERATING ROOM FIXTURES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: SEGMENT GROWTH POTENTIAL, BY OPERATING ROOM FIXTURES, IN 2025
FIGURE 20: OPERATING TABLES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: OPERATING ROOM LIGHTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: SURGICAL BOOMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: OTHER OPERATING ROOM FIXTURES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: OTHER EQUIPMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: SEGMENT GROWTH POTENTIAL, BY APPLICATION, IN 2025
FIGURE 26: CARDIOVASCULAR SURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: NEUROSURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: THORACIC SURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 29: ORTHOPEDIC SURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: OTHER APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: SEGMENT GROWTH POTENTIAL, BY END-USER, IN 2025
FIGURE 32: HOSPITAL AND SURGICAL CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 33: OUTPATIENT SURGICAL CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 34: OTHER END-USERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 35: NORTH AMERICA INTEGRATED/HYBRID OPERATING ROOM MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 36: UNITED STATES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 37: CANADA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 38: EUROPE INTEGRATED/HYBRID OPERATING ROOM MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 39: GERMANY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 40: UNITED KINGDOM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 41: FRANCE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 42: ITALY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 43: SPAIN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 44: BELGIUM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 45: POLAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 46: REST OF EUROPE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 47: ASIA-PACIFIC INTEGRATED/HYBRID OPERATING ROOM MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 48: CHINA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 49: INDIA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 50: JAPAN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 51: AUSTRALIA & NEW ZEALAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 52: SOUTH KOREA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 53: THAILAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 54: INDONESIA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 55: VIETNAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 56: REST OF ASIA-PACIFIC MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 57: REST OF WORLD INTEGRATED/HYBRID OPERATING ROOM MARKET, REGIONAL OUTLOOK, 2025 & 2034 (IN %)
FIGURE 58: LATIN AMERICA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 59: MIDDLE EAST & AFRICA MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
FAQs
Emerging markets are adopting hybrid operating room systems as healthcare infrastructure modernizes and demand for advanced surgical capabilities increases. Government investments in tertiary care hospitals and growing medical tourism industries accelerate market penetration in regions like the Asia-Pacific and Latin America.
Hybrid operating rooms enhance patient outcomes by enabling real-time imaging guidance during procedures, reducing the need for multiple surgeries, and minimizing invasive interventions. Studies indicate that hybrid OR procedures result in shorter recovery times and fewer post-operative complications across cardiovascular surgery and neurosurgery applications.
Hospitals encounter significant challenges, including high capital costs, complex integration requirements, and extensive staff training needs. Additionally, space constraints in existing facilities often require substantial infrastructure modifications to accommodate advanced diagnostic imaging systems and surgical equipment within hybrid operating room configurations.
RELATED REPORTS
-
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-
SPAIN ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
MEXICO ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
ITALY ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
AUSTRALIA ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
BRAZIL ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
INDIA ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
GLOBAL ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034