Germany Integrated/Hybrid Operating Room Market by Equipment (Diagnostic Imaging Systems, Operating Room Fixtures, Other Equipment) Market by Application (Cardiovascular Surgery, Neurosurgery, Thoracic Surgery, Orthopedic Surgery, Other Applications) Market by End-User (Hospital and Surgical Centers, Outpatient Surgical Centers, Other End-Users), by Geography
GERMANY INTEGRATED/HYBRID OPERATING ROOM MARKET OVERVIEW
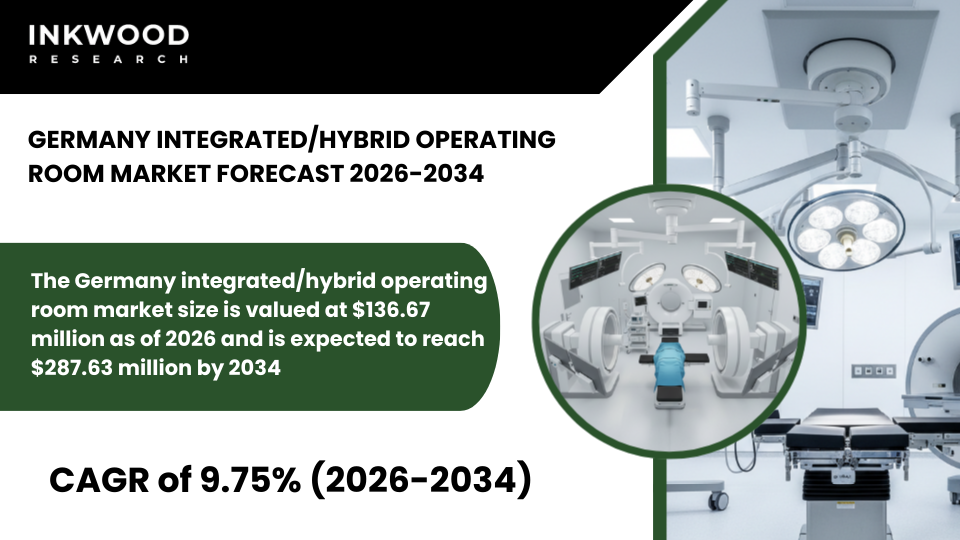
The Germany integrated/hybrid operating room market size is valued at $136.67 million as of 2026 and is expected to reach $287.63 million by 2034, progressing with a CAGR of 9.75% during the forecast years, 2026-2034.
Germany stands as one of Europe’s most sophisticated markets for integrated hybrid operating room systems, benefiting from substantial healthcare infrastructure investments and a strong commitment to medical technology innovation. The German healthcare system, which spent 12.7% of GDP on health expenditure in 2022 according to the European Observatory on Health Systems and Policies, provides hospitals with significant financial resources to pursue advanced surgical capabilities.
This substantial funding, equivalent to approximately €5,832 per capita based on Federal Statistical Office data, enables both public and private hospitals to invest confidently in capital-intensive technologies like hybrid operating rooms. Moreover, Germany’s mandatory health insurance system, covering approximately 87% of the population through statutory health insurance, ensures stable reimbursement structures that make hybrid OR investments economically viable for hospital administrators.
The nation’s aging population, combined with high surgical volumes for cardiovascular and orthopedic procedures, creates sustained demand for advanced operating environments that can accommodate complex, image-guided interventions with superior patient outcomes. Germany operates approximately 1,874 hospitals as of 2023, according to the Federal Statistical Office, representing a mature yet evolving healthcare delivery system focused on quality and efficiency improvements.
To Know More About This Report, Request a Free Sample Copy
These hospitals, distributed across 16 federal states, maintain strong technical capabilities and demonstrate a willingness to adopt innovative surgical technologies that enhance procedural precision and patient safety. Furthermore, Germany’s decentralized healthcare governance system delegates hospital planning and investment decisions to state governments, allowing regional flexibility in modernizing surgical infrastructure based on local population needs and disease burden patterns.
Tertiary care hospitals and university medical centers lead hybrid OR adoption, installing comprehensive systems that support multidisciplinary surgical teams performing cardiovascular interventions, neurosurgical procedures, and complex trauma surgeries.
Additionally, the German government’s recent hospital reform initiatives, including the establishment of a Government Commission for Modern and Needs-based Hospital Care in 2022, emphasize upgrading hospital infrastructure and improving surgical efficiency through technology integration, creating favorable policy conditions for hybrid operating room market expansion.
The Germany integrated/hybrid operating room market is segmented into equipment, application, and end-user. The operating room fixtures segment, categorized under equipment, is further divided into operating tables, operating room lights, surgical booms, and other operating room fixtures.
Operating room fixtures represent a critical component within Germany’s hybrid OR market, encompassing specialized equipment designed to support advanced surgical workflows and optimize space utilization in technology-dense environments. Operating tables designed specifically for hybrid OR applications feature advanced positioning capabilities, radiolucent surfaces for optimal imaging quality, and seamless integration with surrounding imaging systems and surgical navigation platforms.
These sophisticated tables enable surgical teams to perform complex procedures requiring frequent patient repositioning while maintaining sterile fields and uninterrupted access to real-time imaging data. Similarly, operating room lights designed for hybrid environments incorporate LED technology with adjustable intensity and color temperature controls, shadow management systems, and strategic positioning to avoid interference with overhead imaging equipment like angiography systems and surgical navigation cameras.
Surgical booms, meanwhile, provide essential infrastructure for managing the extensive electrical, data, and medical gas connections required by hybrid OR systems, suspending monitors, imaging displays, and surgical instruments from ceiling-mounted articulating arms that maximize floor space and improve workflow efficiency.
German hospitals increasingly prioritize integrated fixture solutions that work harmoniously with diagnostic imaging systems and other equipment, recognizing that proper fixture selection significantly impacts surgical team productivity, procedural safety, and overall hybrid OR functionality.
Some of the top players operating in the Germany integrated/hybrid operating room market include Karl Storz SE & Co KG, Siemens AG, Drägerwerk AG & Co KGaA, Getinge AB, etc.
Karl Storz SE & Co KG, headquartered in Tuttlingen, Germany, maintains a prominent position in the German integrated hybrid operating room market through its comprehensive portfolio of endoscopy equipment, surgical visualization systems, and OR integration platforms. The company has grown into a global leader specializing in rigid and flexible endoscopes, medical imaging systems, and integrated operating room solutions that support minimally invasive surgical techniques.
Karl Storz offers advanced OR integration systems, including the OR1 Fusion digital integration platform, which provides centralized control of multiple imaging sources, surgical displays, recording systems, and communication tools within hybrid operating environments. The company serves hospitals throughout Germany via direct sales teams and maintains close relationships with German surgical centers through extensive training programs and technical support services.
Notably, Karl Storz operates multiple manufacturing facilities within Germany, including its main production complex in Tuttlingen, enabling rapid customization and local support for German hospital customers seeking tailored hybrid OR configurations. With deep roots in German manufacturing excellence and a strong presence in university medical centers across the country, Karl Storz leverages its engineering expertise and understanding of German hospital workflows to deliver integrated solutions that meet the exacting standards expected by German surgical teams pursuing precision medicine and optimal patient outcomes.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Equipment, Application, and End-User |
| Country Analyzed | Germany |
| Companies Analyzed | Barco NV, Carl Zeiss Meditec Group, Drägerwerk AG & Co KGaA, GE Healthcare, Getinge AB, KARL STORZ SE & Co KG, Koninklijke Philips NV, Olympus Corporation, Siemens AG, Stryker Corporation |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- GERMANY REPRESENTS ONE OF THE MOST MATURE AND TECHNOLOGICALLY ADVANCED HYBRID OR MARKETS IN EUROPE
- PUBLIC AND PRIVATE HOSPITALS SHOW HIGH ADOPTION DUE TO STRONG HEALTHCARE FUNDING AND INFRASTRUCTURE
- HYBRID ORS ARE WIDELY UTILIZED FOR CARDIAC VASCULAR AND TRAUMA SURGERIES
- DOMESTIC AND EUROPEAN MEDICAL TECHNOLOGY COMPANIES PLAY A SIGNIFICANT ROLE IN SYSTEM SUPPLY
MARKET DYNAMICS
- KEY DRIVERS
- HIGH SURGICAL VOLUMES AND AN AGING POPULATION ARE DRIVING DEMAND FOR ADVANCED OPERATING ENVIRONMENTS
- STRONG FOCUS ON MINIMALLY INVASIVE AND PRECISION SURGERY IS SUPPORTING HYBRID OR EXPANSION
- FAVORABLE REIMBURSEMENT STRUCTURES ENABLE HOSPITALS TO INVEST IN CAPITAL-INTENSIVE TECHNOLOGIES
- CONTINUOUS TECHNOLOGICAL INNOVATION IN IMAGING AND SURGICAL SYSTEMS IS ENHANCING MARKET GROWTH
- KEY RESTRAINTS
- HIGH INSTALLATION AND INFRASTRUCTURE MODIFICATION COSTS CAN LIMIT RETROFITTING IN OLDER HOSPITAL BUILDINGS
- LENGTHY PROCUREMENT AND APPROVAL PROCESSES CAN DELAY PROJECT IMPLEMENTATION
- COMPLEX SYSTEM INTEGRATION REQUIREMENTS INCREASE DEPLOYMENT TIME AND COST
- PRESSURE ON HOSPITAL BUDGETS TO CONTROL COSTS CAN MODERATE CAPITAL SPENDING
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- INTEGRATION OF ROBOTIC SURGERY WITH HYBRID OPERATING ROOMS IS GAINING MOMENTUM
- HOSPITALS ARE INCREASINGLY FOCUSING ON DIGITALIZATION AND SMART OR CONCEPTS
- STANDARDIZATION OF HYBRID OR DESIGN AND WORKFLOWS IS IMPROVING OPERATIONAL EFFICIENCY
- SUSTAINABILITY AND ENERGY-EFFICIENT OR INFRASTRUCTURE ARE BECOMING KEY PROCUREMENT CRITERIA
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR GERMANY
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- COMPONENT MANUFACTURERS
- IMAGING SYSTEM SUPPLIERS
- OR INTEGRATION PROVIDERS
- SOFTWARE PLATFORM DEVELOPERS
- SYSTEM INTEGRATORS
- HOSPITAL END-USERS
- KEY BUYING CRITERIA
- IMAGING COMPATIBILITY
- SYSTEM INTEROPERABILITY
- TOTAL COST OWNERSHIP
- AFTER SALES SUPPORT
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
INTEGRATED/HYBRID OPERATING ROOM MARKET BY EQUIPMENT
- DIAGNOSTIC IMAGING SYSTEMS
- ANGIOGRAPHY SYSTEMS
- MRI SYSTEMS
- CT SCANNERS
- OTHER DIAGNOSTIC IMAGING SYSTEMS
- OPERATING ROOM FIXTURES
- OPERATING TABLES
- OPERATING ROOM LIGHTS
- SURGICAL BOOMS
- OTHER OPERATING ROOM FIXTURES
- OTHER EQUIPMENT
- DIAGNOSTIC IMAGING SYSTEMS
INTEGRATED/HYBRID OPERATING ROOM MARKET BY APPLICATION
- CARDIOVASCULAR SURGERY
- NEUROSURGERY
- THORACIC SURGERY
- ORTHOPEDIC SURGERY
- OTHER APPLICATIONS
INTEGRATED/HYBRID OPERATING ROOM MARKET BY END-USER
- HOSPITAL AND SURGICAL CENTERS
- OUTPATIENT SURGICAL CENTERS
- OTHER END-USERS
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- BARCO NV
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- CARL ZEISS MEDITEC GROUP
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- DRÄGERWERK AG & CO KGAA
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- GE HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- GETINGE AB
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- KARL STORZ SE & CO KG
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- KONINKLIJKE PHILIPS NV
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- OLYMPUS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- SIEMENS AG
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- STRYKER CORPORATION
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- BARCO NV
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – INTEGRATED/HYBRID OPERATING ROOM
TABLE 2: INTEGRATED/HYBRID OPERATING ROOM MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY EQUIPMENT, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY EQUIPMENT, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: MARKET BY DIAGNOSTIC IMAGING SYSTEMS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: MARKET BY DIAGNOSTIC IMAGING SYSTEMS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: MARKET BY OPERATING ROOM FIXTURES, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: MARKET BY OPERATING ROOM FIXTURES, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: MARKET BY APPLICATION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: MARKET BY APPLICATION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: MARKET BY END-USER, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 12: MARKET BY END-USER, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 13: KEY PLAYERS OPERATING IN THE GERMAN MARKET
TABLE 14: LIST OF MERGERS & ACQUISITIONS
TABLE 15: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 16: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 17: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: KEY MARKET TRENDS
FIGURE 2: PORTER’S FIVE FORCES ANALYSIS
FIGURE 3: GROWTH PROSPECT MAPPING FOR GERMANY
FIGURE 4: MARKET MATURITY ANALYSIS
FIGURE 5: MARKET CONCENTRATION ANALYSIS
FIGURE 6: VALUE CHAIN ANALYSIS
FIGURE 7: KEY BUYING CRITERIA
FIGURE 8: SEGMENT GROWTH POTENTIAL, BY EQUIPMENT, IN 2025
FIGURE 9: DIAGNOSTIC IMAGING SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY DIAGNOSTIC IMAGING SYSTEMS, IN 2025
FIGURE 11: ANGIOGRAPHY SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: MRI SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: CT SCANNERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 14: OTHER DIAGNOSTIC IMAGING SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: OPERATING ROOM FIXTURES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: SEGMENT GROWTH POTENTIAL, BY OPERATING ROOM FIXTURES, IN 2025
FIGURE 17: OPERATING TABLES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: OPERATING ROOM LIGHTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: SURGICAL BOOMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: OTHER OPERATING ROOM FIXTURES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: OTHER EQUIPMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: SEGMENT GROWTH POTENTIAL, BY APPLICATION, IN 2025
FIGURE 23: CARDIOVASCULAR SURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: NEUROSURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: THORACIC SURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: ORTHOPEDIC SURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: OTHER APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: SEGMENT GROWTH POTENTIAL, BY END-USER, IN 2025
FIGURE 29: HOSPITAL AND SURGICAL CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: OUTPATIENT SURGICAL CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: OTHER END-USERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
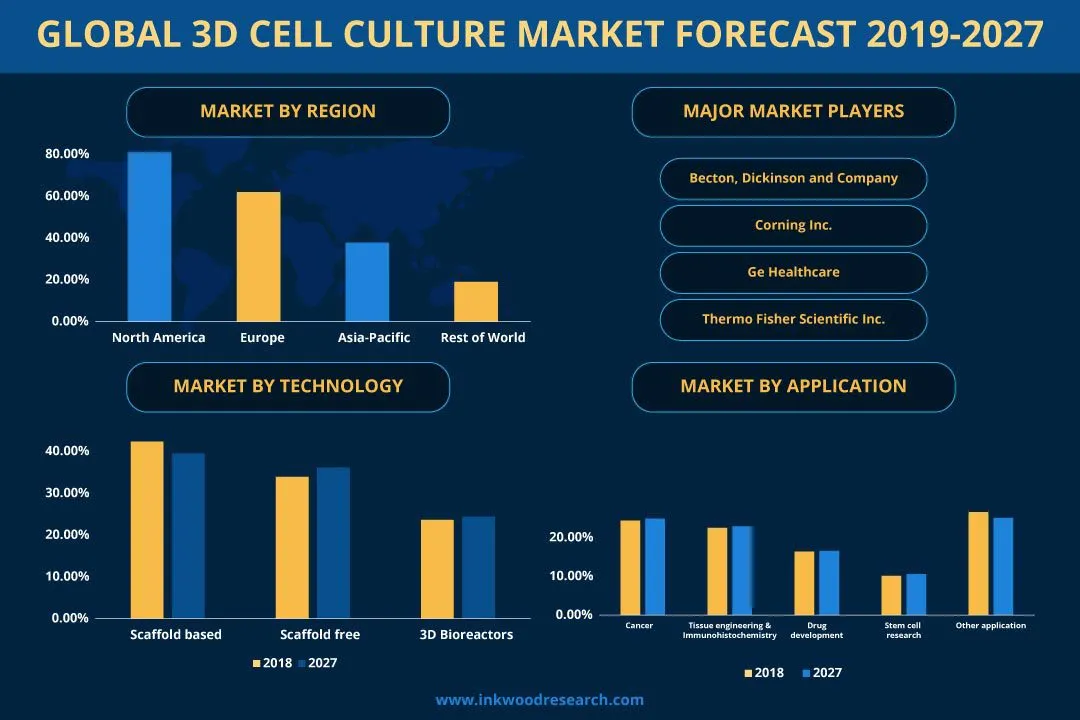
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
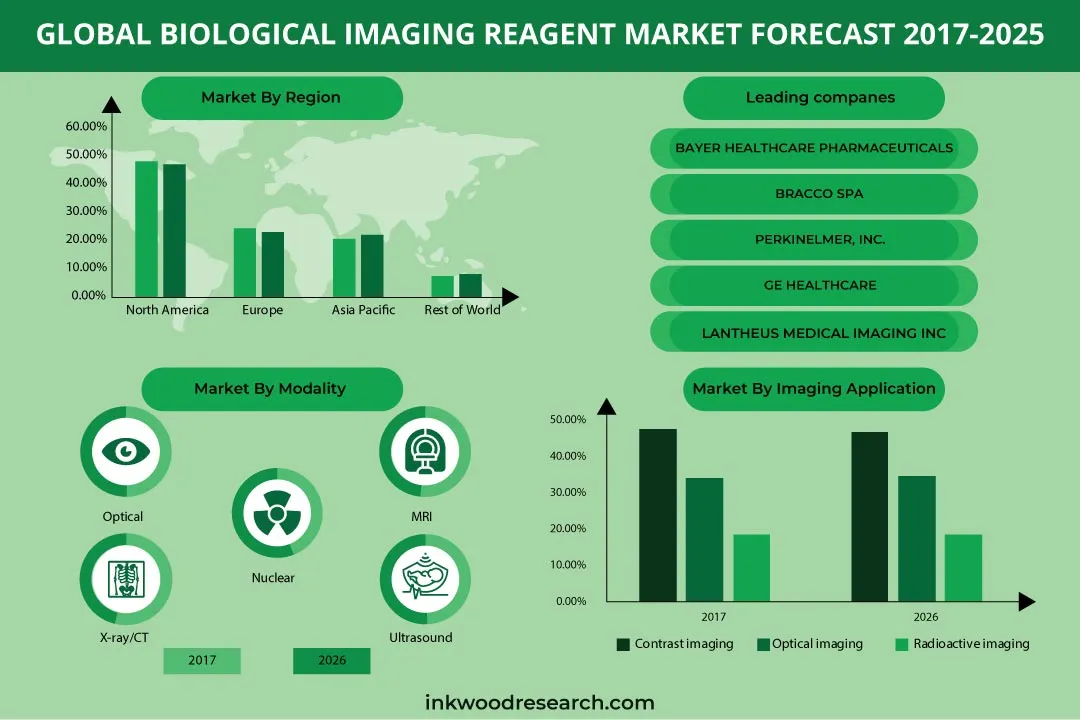
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034