India Integrated/Hybrid Operating Room Market by Equipment (Diagnostic Imaging Systems, Operating Room Fixtures, Other Equipment) Market by Application (Cardiovascular Surgery, Neurosurgery, Thoracic Surgery, Orthopedic Surgery, Other Applications) Market by End-User (Hospital and Surgical Centers, Outpatient Surgical Centers, Other End-Users), by Geography
INDIA INTEGRATED/HYBRID OPERATING ROOM MARKET OVERVIEW
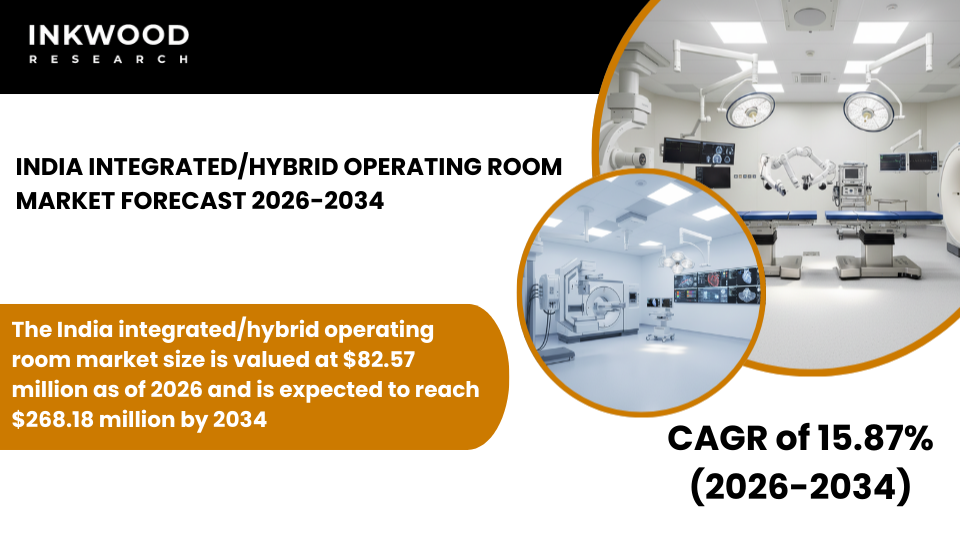
The India integrated/hybrid operating room market size is valued at $82.57 million as of 2026 and is expected to reach $268.18 million by 2034, progressing with a CAGR of 15.87% during the forecast years, 2026-2034.
India emerges as one of the fastest-growing markets for integrated hybrid operating room systems within the Asia-Pacific region, driven by the rapid expansion of private healthcare infrastructure and the increasing adoption of advanced surgical technologies among tertiary care hospitals.
The Indian healthcare sector demonstrates remarkable momentum, with total health expenditure reaching ₹9.04 lakh crore in fiscal year 2022 according to government data, representing 3.8% of GDP and ₹6,602 per capita at current prices. Moreover, the government health expenditure’s share in total healthcare spending has increased substantially from 29% in fiscal year 2015 to 48% in fiscal year 2022, reflecting a stronger public sector commitment to healthcare infrastructure development.
Private multispecialty hospital chains, concentrated primarily in metropolitan areas and tier-one cities, lead hybrid OR adoption patterns as they seek to differentiate their service offerings and attract high-value patients requiring complex cardiovascular and neurosurgical interventions.
Additionally, the growing medical tourism industry positions India as an attractive destination for international patients seeking cost-effective yet sophisticated surgical procedures, motivating premium hospitals to invest in state-of-the-art hybrid operating room facilities that meet global quality standards and enable advanced image-guided interventions with superior clinical outcomes.
To Know More About This Report, Request a Free Sample Copy
According to PRS Legislative Research analysis, approximately 30,174 hospitals were empanelled under the Ayushman Bharat scheme as of July 2024, with about 56% being public hospitals. However, the hybrid OR market remains concentrated among large private hospital groups and select flagship government institutions that possess both the capital resources and technical expertise required for successful implementation of these sophisticated systems.
Private hospitals accounted for 55% of hospitalization cases in India as of 2017-18, according to National Statistical Office data, highlighting the significant role private healthcare infrastructure plays in delivering advanced medical services to the population. Furthermore, the rising incidence of cardiovascular diseases, neurological disorders, and trauma cases creates sustained demand for hybrid operating rooms capable of supporting minimally invasive procedures that combine real-time imaging with surgical intervention.
Indian hospitals increasingly recognize that hybrid OR capabilities enhance procedural efficiency, reduce patient recovery times, and enable surgical teams to tackle more complex cases that would previously require multiple procedures or patient transfers, thereby improving both clinical outcomes and institutional reputations within competitive urban healthcare markets.
The India integrated/hybrid operating room market is segmented into equipment, application, and end-user. The application segment is further categorized into cardiovascular surgery, neurosurgery, thoracic surgery, orthopedic surgery, and other applications.
Cardiovascular surgery represents a dominant application segment within India’s hybrid OR market, accounting for a significant share of installations and procedural volumes across major metropolitan hospitals. The cardiovascular application’s prominence stems from India’s substantial burden of heart disease, which drives high volumes of coronary interventions, valve replacement procedures, and complex vascular surgeries that benefit significantly from hybrid operating room capabilities.
Cardiac surgeons increasingly favor hybrid environments that seamlessly integrate advanced angiography systems with traditional surgical instruments, enabling them to perform sophisticated procedures like transcatheter aortic valve replacement, hybrid coronary revascularization, and endovascular aortic repair without relocating patients between catheterization laboratories and conventional operating theaters.
This integrated approach reduces procedural time, minimizes patient movement risks, and allows multidisciplinary teams comprising interventional cardiologists and cardiac surgeons to collaborate effectively within a single optimized workspace. Moreover, the aging Indian population combined with lifestyle-related risk factors contributes to rising cardiovascular disease prevalence, creating sustained demand for advanced surgical facilities equipped to handle complex cardiac interventions requiring both open surgical access and minimally invasive catheter-based techniques.
Private cardiac specialty hospitals and multispecialty chains with dedicated cardiovascular centers lead investment in hybrid OR systems designed specifically for cardiac applications, recognizing these facilities as essential infrastructure for delivering cutting-edge cardiovascular care that meets international standards while serving both domestic patients and international medical tourists seeking high-quality, cost-competitive cardiac surgical services.
Some of the top players operating in the India integrated/hybrid operating room market include GE Healthcare, Siemens AG, Koninklijke Philips NV, Getinge AB, etc.
GE Healthcare, operating extensively in India through GE HealthCare India Private Limited, maintains a prominent position in the Indian integrated hybrid operating room market through its comprehensive portfolio of medical imaging systems, surgical equipment, and OR integration platforms. The company serves as a leading global medical technology provider with a significant presence across India, delivering advanced diagnostic imaging solutions, including angiography systems, computed tomography scanners, and surgical navigation tools that form the foundation of hybrid operating room installations.
GE Healthcare offers integrated OR solutions, including the OEC Elite CFD C-arm system and Discovery IGS imaging platforms, which provide real-time fluoroscopic guidance essential for cardiovascular and neurosurgical procedures performed in hybrid environments. The company serves Indian hospitals through an extensive network of direct sales teams, authorized distributors, and service centers located across major cities, enabling rapid installation support and ongoing technical maintenance for complex hybrid OR systems.
Notably, GE Healthcare has established local manufacturing capabilities and partnerships within India to address the specific requirements of the Indian market, including cost-sensitive configurations and solutions tailored to the procedural volumes and technical requirements of Indian healthcare facilities.
With strong relationships among leading private hospital chains, cardiac specialty centers, and premier government institutions, including All India Institutes of Medical Sciences, GE Healthcare leverages its brand reputation, comprehensive product portfolio, and local support infrastructure to deliver turnkey hybrid OR solutions. These enable Indian hospitals to offer advanced image-guided surgical capabilities meeting international quality standards while serving the nation’s growing demand for sophisticated cardiovascular and neurosurgical interventions.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Equipment, Application, and End-User |
| Country Analyzed | India |
| Companies Analyzed | Arthrex Inc, Barco NV, Carl Zeiss Meditec Group, CONMED Corporation, Drägerwerk AG & Co KGaA, Fisher & Paykel Healthcare Corporation Limited, GE Healthcare, Getinge AB, Integra LifeSciences Holdings Corporation, KARL STORZ SE & Co KG, Koninklijke Philips NV, Olympus Corporation, Siemens AG, Smith & Nephew PLC, Stryker Corporation |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- THE INDIAN INTEGRATED HYBRID OPERATING ROOM MARKET IS CONCENTRATED IN TERTIARY AND QUATERNARY CARE HOSPITALS LOCATED IN METRO AND TIER ONE CITIES
- PRIVATE MULTISPECIALTY HOSPITAL CHAINS ACCOUNT FOR THE MAJORITY OF HYBRID OR INSTALLATIONS DUE TO HIGH PROCEDURAL VOLUMES AND CAPITAL AVAILABILITY
- CARDIAC AND NEURO INTERVENTIONAL PROCEDURES REPRESENT THE LARGEST SHARE OF HYBRID OR UTILIZATION IN INDIA
- PUBLIC SECTOR ADOPTION REMAINS LIMITED AND IS LARGELY DRIVEN BY FLAGSHIP GOVERNMENT INSTITUTIONS AND MEDICAL COLLEGES
MARKET DYNAMICS
- KEY DRIVERS
- RISING INCIDENCE OF CARDIOVASCULAR AND NEUROLOGICAL DISORDERS IS INCREASING DEMAND FOR IMAGE-GUIDED SURGICAL ENVIRONMENTS
- EXPANSION OF PRIVATE HEALTHCARE INFRASTRUCTURE AND MEDICAL TOURISM IS SUPPORTING INVESTMENT IN ADVANCED OPERATING ROOMS
- INCREASING SURGEON PREFERENCE FOR MINIMALLY INVASIVE AND HYBRID PROCEDURES IS ACCELERATING TECHNOLOGY ADOPTION
- IMPROVING ACCESS TO HIGH-END MEDICAL IMAGING SYSTEMS IS ENABLING INTEGRATION WITH OPERATING ROOM INFRASTRUCTURE
- KEY RESTRAINTS
- HIGH INITIAL CAPITAL EXPENDITURE AND LONG PAYBACK PERIODS LIMIT ADOPTION AMONG MEDIUM-SIZED AND SMALL HOSPITALS
- LACK OF UNIFORM TECHNICAL STANDARDS AND INTEGRATION CHALLENGES ACROSS EQUIPMENT VENDORS SLOW DEPLOYMENT
- SHORTAGE OF TRAINED SURGICAL AND TECHNICAL STAFF CONSTRAINS EFFECTIVE UTILIZATION OF HYBRID ORS
- BUDGETARY CONSTRAINTS IN PUBLIC HEALTHCARE FACILITIES RESTRICT LARGE-SCALE IMPLEMENTATION
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- HOSPITALS ARE INCREASINGLY ADOPTING MODULAR AND SCALABLE HYBRID OR DESIGNS TO OPTIMIZE COSTS
- INTEGRATION OF REAL TIME IMAGING AND DIGITAL WORKFLOW SOLUTIONS IS BECOMING A STANDARD REQUIREMENT
- VENDORS ARE OFFERING TURNKEY SOLUTIONS INCLUDING DESIGN, INSTALLATION, AND MAINTENANCE SERVICES
- COLLABORATION BETWEEN IMAGING AND SURGICAL EQUIPMENT MANUFACTURERS IS INTENSIFYING
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR INDIA
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- COMPONENT MANUFACTURERS
- IMAGING SYSTEM SUPPLIERS
- OR INTEGRATION PROVIDERS
- SOFTWARE PLATFORM DEVELOPERS
- SYSTEM INTEGRATORS
- HOSPITAL END-USERS
- KEY BUYING CRITERIA
- IMAGING COMPATIBILITY
- SYSTEM INTEROPERABILITY
- TOTAL COST OWNERSHIP
- AFTER SALES SUPPORT
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
INTEGRATED/HYBRID OPERATING ROOM MARKET BY EQUIPMENT
- DIAGNOSTIC IMAGING SYSTEMS
- ANGIOGRAPHY SYSTEMS
- MRI SYSTEMS
- CT SCANNERS
- OTHER DIAGNOSTIC IMAGING SYSTEMS
- OPERATING ROOM FIXTURES
- OPERATING TABLES
- OPERATING ROOM LIGHTS
- SURGICAL BOOMS
- OTHER OPERATING ROOM FIXTURES
- OTHER EQUIPMENT
- DIAGNOSTIC IMAGING SYSTEMS
INTEGRATED/HYBRID OPERATING ROOM MARKET BY APPLICATION
- CARDIOVASCULAR SURGERY
- NEUROSURGERY
- THORACIC SURGERY
- ORTHOPEDIC SURGERY
- OTHER APPLICATIONS
INTEGRATED/HYBRID OPERATING ROOM MARKET BY END-USER
- HOSPITAL AND SURGICAL CENTERS
- OUTPATIENT SURGICAL CENTERS
- OTHER END-USERS
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT
LAUNCHES & DEVELOPMENTS - PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- ARTHREX INC
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- BARCO NV
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- CARL ZEISS MEDITEC GROUP
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- CONMED CORPORATION
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- DRAGERWERK AG & CO KGAA
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- FISHER & PAYKEL HEALTHCARE CORPORATION LIMITED
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- GE HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- GETINGE AB
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- INTEGRA LIFESCIENCES HOLDINGS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- KARL STORZ SE & CO KG
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- KONINKLIJKE PHILIPS N.V
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- OLYMPUS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- SIEMENS AG
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- SMITH & NEPHEW PLC
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- STRYKER CORPORATION
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- ARTHREX INC
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – INTEGRATED/HYBRID OPERATING ROOM
TABLE 2: INTEGRATED/HYBRID OPERATING ROOM MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY EQUIPMENT, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY EQUIPMENT, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: MARKET BY DIAGNOSTIC IMAGING SYSTEMS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: MARKET BY DIAGNOSTIC IMAGING SYSTEMS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: MARKET BY OPERATING ROOM FIXTURES, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: MARKET BY OPERATING ROOM FIXTURES, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: MARKET BY APPLICATION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: MARKET BY APPLICATION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: MARKET BY END-USER, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 12: MARKET BY END-USER, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 13: KEY PLAYERS OPERATING IN THE INDIAN MARKET
TABLE 14: LIST OF MERGERS & ACQUISITIONS
TABLE 15: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 16: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 17: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: KEY MARKET TRENDS
FIGURE 2: PORTER’S FIVE FORCES ANALYSIS
FIGURE 3: GROWTH PROSPECT MAPPING FOR INDIA
FIGURE 4: MARKET MATURITY ANALYSIS
FIGURE 5: MARKET CONCENTRATION ANALYSIS
FIGURE 6: VALUE CHAIN ANALYSIS
FIGURE 7: KEY BUYING CRITERIA
FIGURE 8: SEGMENT GROWTH POTENTIAL, BY EQUIPMENT, IN 2025
FIGURE 9: DIAGNOSTIC IMAGING SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY DIAGNOSTIC IMAGING SYSTEMS, IN 2025
FIGURE 11: ANGIOGRAPHY SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: MRI SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: CT SCANNERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 14: OTHER DIAGNOSTIC IMAGING SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: OPERATING ROOM FIXTURES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: SEGMENT GROWTH POTENTIAL, BY OPERATING ROOM FIXTURES, IN 2025
FIGURE 17: OPERATING TABLES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: OPERATING ROOM LIGHTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: SURGICAL BOOMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: OTHER OPERATING ROOM FIXTURES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: OTHER EQUIPMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: SEGMENT GROWTH POTENTIAL, BY APPLICATION, IN 2025
FIGURE 23: CARDIOVASCULAR SURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: NEUROSURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: THORACIC SURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: ORTHOPEDIC SURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: OTHER APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: SEGMENT GROWTH POTENTIAL, BY END-USER, IN 2025
FIGURE 29: HOSPITAL AND SURGICAL CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: OUTPATIENT SURGICAL CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: OTHER END-USERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
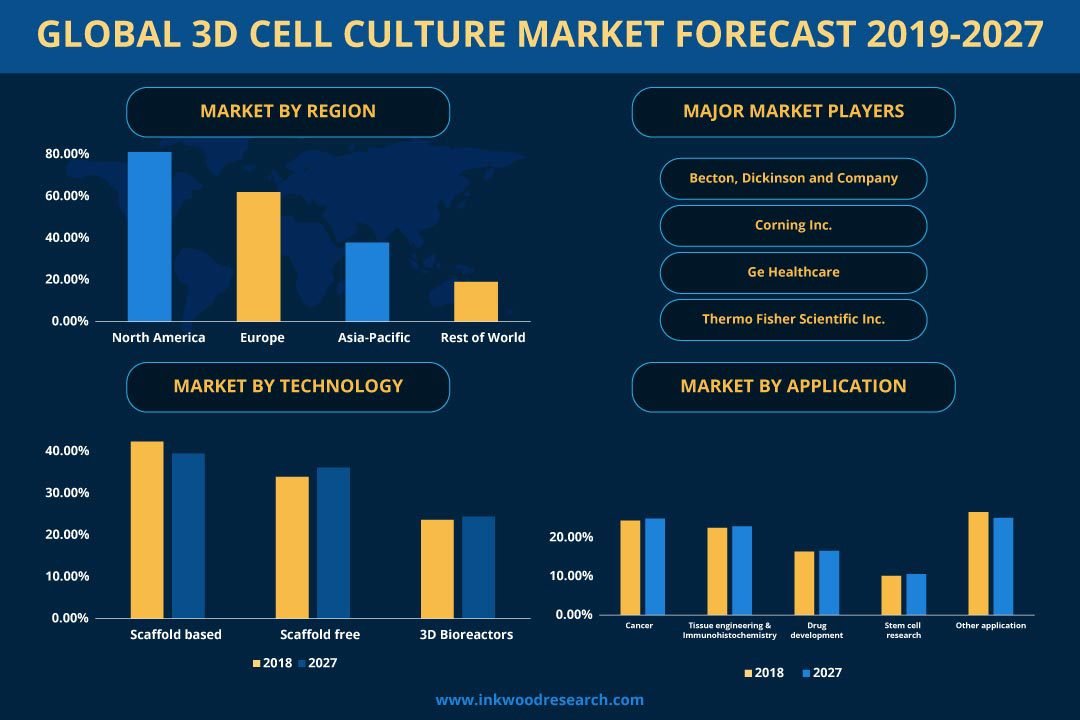
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
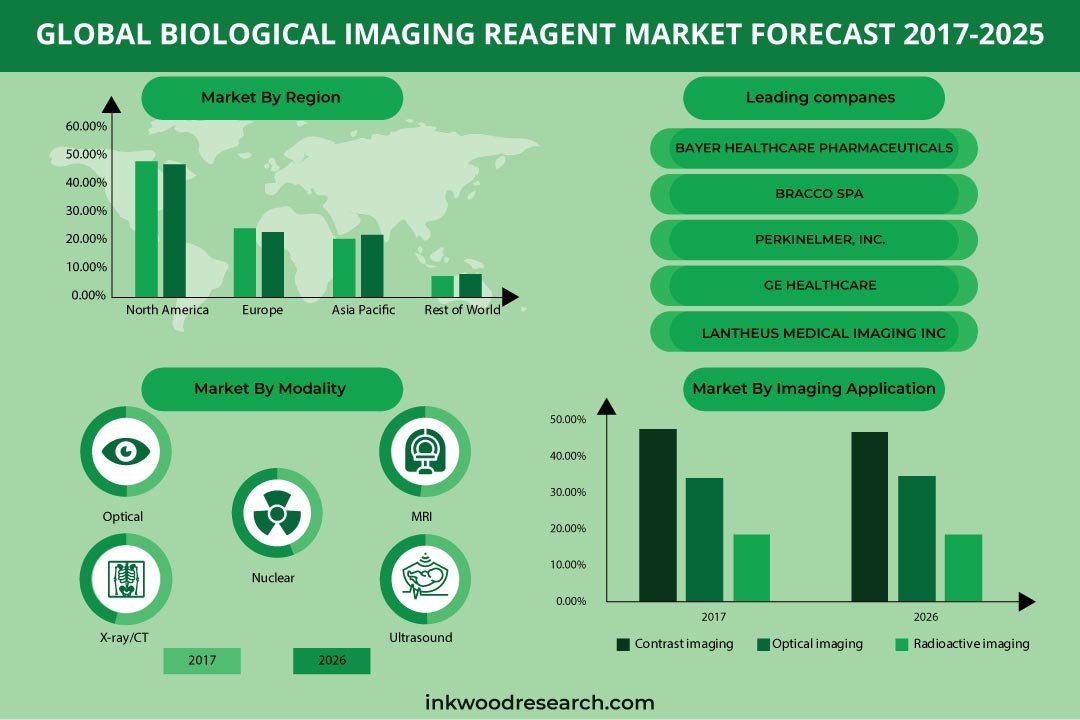
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034