Thailand Integrated/Hybrid Operating Room Market by Equipment (Diagnostic Imaging Systems, Operating Room Fixtures, Other Equipment) Market by Application (Cardiovascular Surgery, Neurosurgery, Thoracic Surgery, Orthopedic Surgery, Other Applications) Market by End-User (Hospital and Surgical Centers, Outpatient Surgical Centers, Other End-Users), by Geography
THAILAND INTEGRATED/HYBRID OPERATING ROOM MARKET OVERVIEW
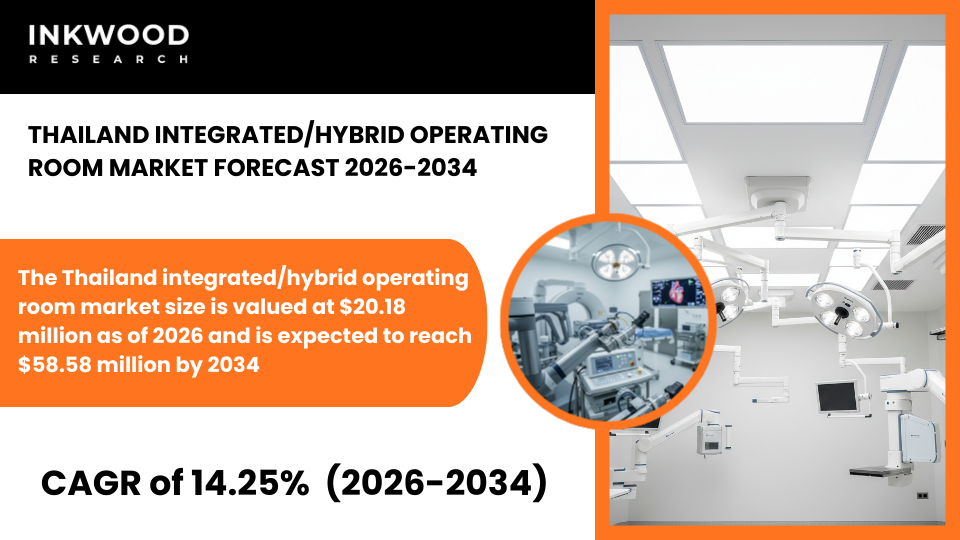
The Thailand integrated/hybrid operating room market size is valued at $20.18 million as of 2026 and is expected to reach $58.58 million by 2034, progressing with a CAGR of 14.25% during the forecast years, 2026-2034.
Thailand stands as a unique and strategically positioned market for integrated hybrid operating room systems, distinguished primarily by its prominent role as a leading medical tourism destination within the Asia-Pacific region. The country’s healthcare sector benefits from substantial government support and private sector investment, with government final consumption expenditure on healthcare reaching approximately 761.74 billion Thai baht in 2022, according to the National Economic and Social Development Council.
Thailand’s thriving medical tourism industry, which attracted an estimated 580,000 medical tourists in 2025 according to the Tourism Authority of Thailand, creates strong demand for world-class surgical infrastructure that can serve both domestic patients and international visitors seeking advanced medical procedures. Moreover, the country boasts 65 medical facilities accredited by the Joint Commission International as of 2024.
This demonstrates widespread commitment to international quality standards that necessitate sophisticated surgical capabilities. Private hospitals dominate the hybrid operating room market, as these facilities aggressively pursue international patient flows by offering premium surgical services at prices 30-70% lower than Western markets while maintaining comparable clinical outcomes and patient safety standards.
To Know More About This Report, Request a Free Sample Copy
Thailand operates approximately 927 government hospitals and 363 private hospitals according to healthcare infrastructure reports, serving a population of nearly 66 million through universal healthcare coverage schemes alongside a robust private healthcare sector. Private hospitals, particularly those in Bangkok and major tourist destinations like Phuket and Pattaya, lead investments in hybrid OR technology as they recognize these advanced facilities serve as powerful differentiators when competing for high-value international patients requiring complex cardiovascular, neurosurgical, and orthopedic procedures.
Furthermore, Thailand’s strategic geographic location within Southeast Asia positions it ideally to serve medical tourists from neighboring countries, including Myanmar, Cambodia, Laos, and increasingly from Middle Eastern nations seeking specialized surgical interventions. The government’s Thailand 4.0 initiative, which identified medical tourism among the top five priority industries for technological innovation and development, reinforces policy support for healthcare infrastructure modernization, including advanced operating room capabilities.
Additionally, private hospital operators recognize that maintaining cutting-edge surgical facilities with integrated imaging systems enhances their ability to attract partnerships with international healthcare providers and insurance networks that increasingly direct patients toward accredited facilities offering advanced procedural capabilities.
The Thailand integrated/hybrid operating room market is segmented into equipment, application, and end-user. The application segment is further classified into cardiovascular surgery, neurosurgery, thoracic surgery, orthopedic surgery, and other applications.
Neurosurgery represents a rapidly growing application segment within Thailand’s hybrid OR market, driven by increasing demand for complex brain and spine procedures that benefit significantly from real-time imaging guidance and precise surgical navigation capabilities.
Neurosurgical applications in hybrid operating environments enable surgeons to perform sophisticated procedures, including cerebral aneurysm repairs, arteriovenous malformation treatments, and complex spinal interventions with enhanced precision and improved patient outcomes.
The integration of advanced imaging modalities like intraoperative CT scanners and angiography systems within hybrid OR suites allows neurosurgical teams to verify procedural success immediately, reducing the need for repeat interventions and minimizing patient complications.
Thailand’s neurosurgical centers, particularly those affiliated with major private hospital groups and academic medical institutions, increasingly invest in hybrid OR capabilities to attract international patients seeking specialized brain and spine surgeries that require both exceptional technical expertise and state-of-the-art surgical environments.
Moreover, the growing incidence of cerebrovascular diseases and traumatic brain injuries across Southeast Asian populations creates sustained demand for advanced neurosurgical capabilities, while medical tourists from neighboring countries specifically seek Thai neurosurgical centers offering hybrid OR facilities that combine sophisticated technology with highly experienced surgical teams at accessible price points compared to Western and Middle Eastern alternatives.
Some of the top players operating in the Thailand integrated/hybrid operating room market include Koninklijke Philips NV, Siemens AG, GE Healthcare, Getinge AB, etc.
Koninklijke Philips NV, commonly known as Philips, maintains a significant presence in the Thailand integrated hybrid operating room market through its comprehensive portfolio of medical imaging systems, surgical lighting solutions, and OR integration platforms designed specifically for advanced surgical environments.
The Dutch multinational technology company operates as a leading global health technology provider with a strong market position across Thailand’s private hospital sector, delivering diagnostic imaging solutions, including interventional X-ray systems, advanced visualization tools, and image-guided therapy platforms essential for modern hybrid operating rooms.
Philips offers integrated OR solutions, including the Azurion image-guided therapy platform and the FlexVision surgical display systems, which provide seamless integration between diagnostic imaging equipment and surgical displays for optimal procedural visualization and workflow efficiency.
The company serves Thailand’s medical tourism-focused hospitals through regional sales offices, authorized distributors, and dedicated service teams capable of supporting complex hybrid OR installations requiring coordination between multiple technology systems and hospital infrastructure.
Notably, Philips has established partnerships with several leading Thai hospital groups, including those operating networks of JCI-accredited facilities catering specifically to international patients, enabling these institutions to offer cutting-edge hybrid OR capabilities that enhance their competitive positioning within the regional medical tourism marketplace.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Equipment, Application, and End-User |
| Country Analyzed | Thailand |
| Companies Analyzed | Barco NV, Carl Zeiss Meditec Group, Drägerwerk AG & Co KGaA, GE Healthcare, Getinge AB, KARL STORZ SE & Co KG, Koninklijke Philips NV, Olympus Corporation, Siemens AG, Stryker Corporation |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- THE THAI HYBRID OPERATING ROOM MARKET IS STRONGLY INFLUENCED BY THE COUNTRY’S ROLE AS A REGIONAL MEDICAL TOURISM HUB
- PRIVATE HOSPITALS DOMINATE MARKET ADOPTION DUE TO STRONG FOREIGN PATIENT INFLOWS AND HIGH PROCEDURE COMPLEXITY
- CARDIOVASCULAR AND ENDOVASCULAR SURGERIES ACCOUNT FOR THE LARGEST SHARE OF HYBRID OR INSTALLATIONS
- TECHNOLOGY PROCUREMENT IS HIGHLY DEPENDENT ON INTERNATIONAL MEDICAL EQUIPMENT SUPPLIERS
MARKET DYNAMICS
- KEY DRIVERS
- GROWTH IN MEDICAL TOURISM IS DRIVING DEMAND FOR WORLD-CLASS SURGICAL INFRASTRUCTURE
- RISING HEALTHCARE EXPENDITURE AND PRIVATE INVESTMENT ARE SUPPORTING ADVANCEMENTS OR UPGRADES
- INCREASING PREVALENCE OF CHRONIC DISEASES IS FUELING THE NEED FOR COMPLEX INTERVENTIONAL PROCEDURES
- STRONG EMPHASIS ON QUALITY ACCREDITATION IS ENCOURAGING HOSPITALS TO INVEST IN HYBRID OR SYSTEMS
- KEY RESTRAINTS
- HIGH DEPENDENCE ON IMPORTED EQUIPMENT RESULTS IN ELEVATED INSTALLATION AND MAINTENANCE COSTS
- LIMITED TECHNICAL EXPERTISE FOR SYSTEM INTEGRATION CAN DELAY PROJECT EXECUTION
- CAPITAL INTENSIVE NATURE OF HYBRID ORS LIMITS PENETRATION BEYOND LARGE PRIVATE HOSPITALS
- FLUCTUATIONS IN MEDICAL TOURISM FLOWS CAN IMPACT RETURN ON INVESTMENT
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- HOSPITALS ARE INCREASINGLY POSITIONING HYBRID ORS AS A PREMIUM DIFFERENTIATOR FOR INTERNATIONAL PATIENTS
- ADOPTION OF ADVANCED IMAGING TECHNOLOGIES, SUCH AS ANGIOGRAPHY, CT, AND MRI, IS INCREASING
- DIGITAL OR MANAGEMENT AND DATA INTEGRATION SOLUTIONS ARE GAINING TRACTION
- STRATEGIC PARTNERSHIPS WITH GLOBAL OEMS ARE BECOMING MORE COMMON
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR THAILAND
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- COMPONENT MANUFACTURERS
- IMAGING SYSTEM SUPPLIERS
- OR INTEGRATION PROVIDERS
- SOFTWARE PLATFORM DEVELOPERS
- SYSTEM INTEGRATORS
- HOSPITAL END-USERS
- KEY BUYING CRITERIA
- IMAGING COMPATIBILITY
- SYSTEM INTEROPERABILITY
- TOTAL COST OWNERSHIP
- AFTER SALES SUPPORT
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
INTEGRATED/HYBRID OPERATING ROOM MARKET BY EQUIPMENT
- DIAGNOSTIC IMAGING SYSTEMS
- ANGIOGRAPHY SYSTEMS
- MRI SYSTEMS
- CT SCANNERS
- OTHER DIAGNOSTIC IMAGING SYSTEMS
- OPERATING ROOM FIXTURES
- OPERATING TABLES
- OPERATING ROOM LIGHTS
- SURGICAL BOOMS
- OTHER OPERATING ROOM FIXTURES
- OTHER EQUIPMENT
- DIAGNOSTIC IMAGING SYSTEMS
INTEGRATED/HYBRID OPERATING ROOM MARKET BY APPLICATION
- CARDIOVASCULAR SURGERY
- NEUROSURGERY
- THORACIC SURGERY
- ORTHOPEDIC SURGERY
- OTHER APPLICATIONS
INTEGRATED/HYBRID OPERATING ROOM MARKET BY END-USER
- HOSPITAL AND SURGICAL CENTERS
- OUTPATIENT SURGICAL CENTERS
- OTHER END-USERS
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- BARCO NV
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- CARL ZEISS MEDITEC GROUP
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- DRÄGERWERK AG & CO KGAA
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- GE HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- GETINGE AB
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- KARL STORZ SE & CO KG
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- KONINKLIJKE PHILIPS NV
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- OLYMPUS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- SIEMENS AG
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- STRYKER CORPORATION
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- BARCO NV
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – INTEGRATED/HYBRID OPERATING ROOM
TABLE 2: INTEGRATED/HYBRID OPERATING ROOM MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY EQUIPMENT, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY EQUIPMENT, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: MARKET BY DIAGNOSTIC IMAGING SYSTEMS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: MARKET BY DIAGNOSTIC IMAGING SYSTEMS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: MARKET BY OPERATING ROOM FIXTURES, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: MARKET BY OPERATING ROOM FIXTURES, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: MARKET BY APPLICATION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: MARKET BY APPLICATION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: MARKET BY END-USER, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 12: MARKET BY END-USER, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 13: KEY PLAYERS OPERATING IN THE THAI MARKET
TABLE 14: LIST OF MERGERS & ACQUISITIONS
TABLE 15: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 16: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 17: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: KEY MARKET TRENDS
FIGURE 2: PORTER’S FIVE FORCES ANALYSIS
FIGURE 3: GROWTH PROSPECT MAPPING FOR THAILAND
FIGURE 4: MARKET MATURITY ANALYSIS
FIGURE 5: MARKET CONCENTRATION ANALYSIS
FIGURE 6: VALUE CHAIN ANALYSIS
FIGURE 7: KEY BUYING CRITERIA
FIGURE 8: SEGMENT GROWTH POTENTIAL, BY EQUIPMENT, IN 2025
FIGURE 9: DIAGNOSTIC IMAGING SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY DIAGNOSTIC IMAGING SYSTEMS, IN 2025
FIGURE 11: ANGIOGRAPHY SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: MRI SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: CT SCANNERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 14: OTHER DIAGNOSTIC IMAGING SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: OPERATING ROOM FIXTURES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: SEGMENT GROWTH POTENTIAL, BY OPERATING ROOM FIXTURES, IN 2025
FIGURE 17: OPERATING TABLES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: OPERATING ROOM LIGHTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: SURGICAL BOOMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: OTHER OPERATING ROOM FIXTURES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: OTHER EQUIPMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: SEGMENT GROWTH POTENTIAL, BY APPLICATION, IN 2025
FIGURE 23: CARDIOVASCULAR SURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: NEUROSURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: THORACIC SURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: ORTHOPEDIC SURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: OTHER APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: SEGMENT GROWTH POTENTIAL, BY END-USER, IN 2025
FIGURE 29: HOSPITAL AND SURGICAL CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: OUTPATIENT SURGICAL CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: OTHER END-USERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
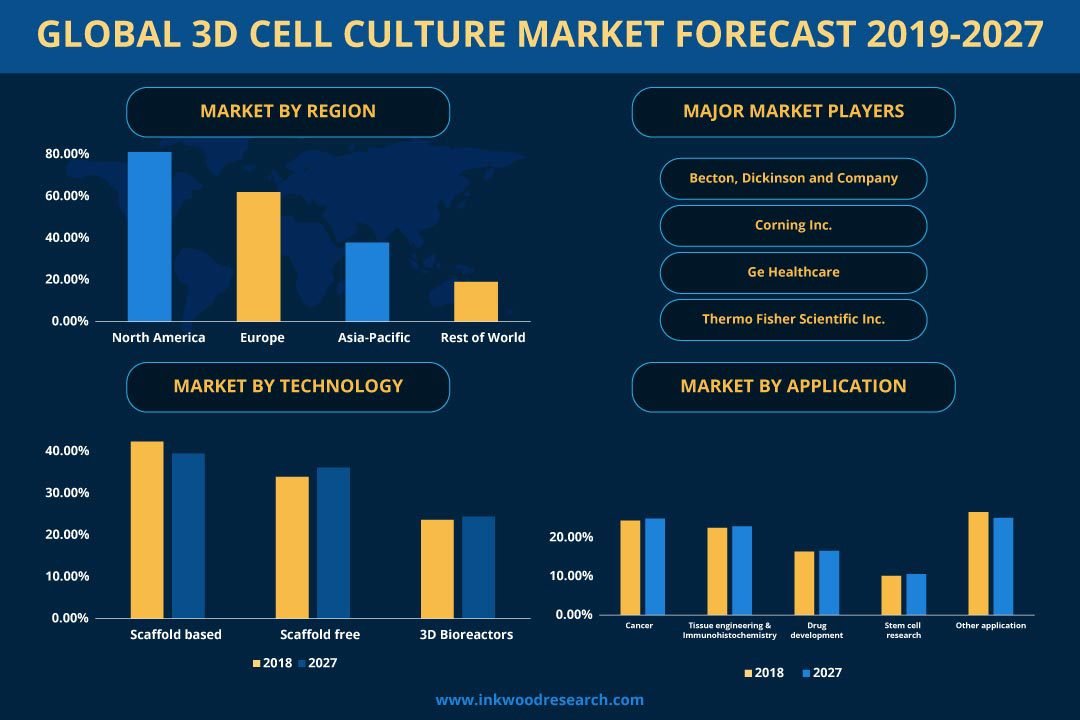
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
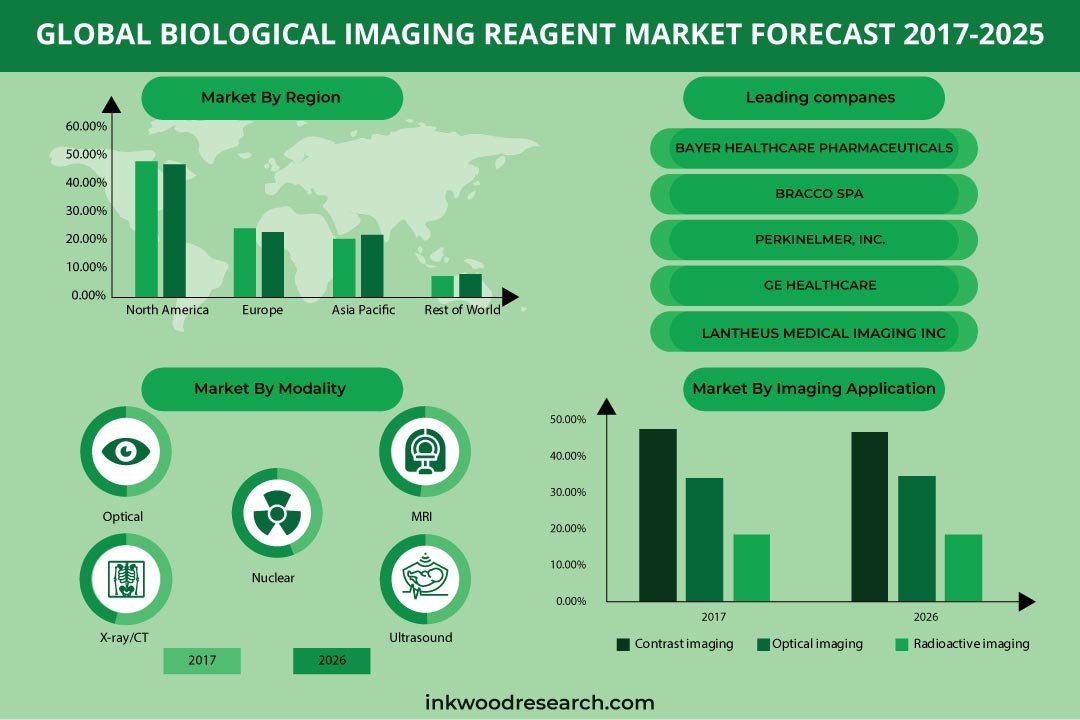
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034