Italy Advanced Delivery Nutraceuticals Market by Delivery Technology (Nanoencapsulated Forms, Liposomal Delivery Systems, Microencapsulated Forms, Other Delivery Technologies), Market by Product Type (Dietary Supplements, Functional Foods, Functional Beverages, Other Product Types), Market by Application (Dietary Supplements, Functional Foods & Beverages, Sports Nutrition, Clinical Nutrition, Other Applications), by Geography
ITALY ADVANCED DELIVERY NUTRACEUTICALS MARKET OVERVIEW
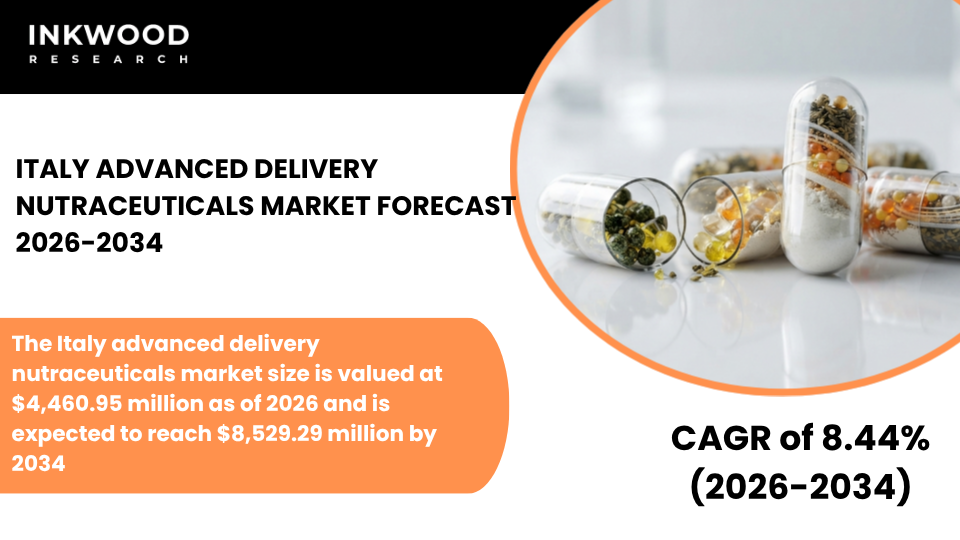
The Italy advanced delivery nutraceuticals market size is valued at $4,460.95 million as of 2026 and is expected to reach $8,529.29 million by 2034, progressing with a CAGR of 8.44% during the forecast years, 2026-2034.
MARKET INSIGHTS
Italy occupies a uniquely prominent position within the Europe nutraceutical delivery systems market trends landscape, driven by one of the most deeply embedded wellness cultures in the world. Italians have long prioritized nutrition as a cornerstone of health, and this cultural foundation is now actively accelerating the transition toward encapsulated nutraceuticals market products that deliver superior, clinically validated results.
The country is, in fact, one of Europe’s largest dietary supplement markets by volume, and consumer demand is progressively shifting toward bioavailability enhancement nutraceuticals over conventional formats. Italian consumers are notably quality-driven and scientifically literate in their health product choices, which creates natural demand for advanced oral delivery systems nutraceuticals that can substantiate their efficacy through credible clinical evidence.
Furthermore, Italy’s extensive pharmacy network, which functions as the primary retail channel for dietary supplements across the country, plays a decisive role in consumer education and product adoption. Pharmacists actively guide purchasing decisions, and their endorsement of encapsulated nutraceuticals market solutions, particularly those incorporating liposomal nutraceutical delivery systems and sustained release nutraceutical formulations, carries significant commercial weight.
Additionally, the country’s strong functional foods tradition and growing interest in personalized nutrition delivery technologies are together broadening the demand base for Italy’s advanced delivery nutraceuticals market well beyond conventional supplementation.
Italy operates within the European Union’s regulatory framework, which is both a quality assurance advantage and a meaningful market entry consideration for the nutraceutical delivery systems market. The Italian Ministry of Health (Ministero della Salute) oversees the notification and regulation of dietary supplements under the national implementation of EU Directive 2002/46/EC on food supplements.
Products incorporating advanced delivery technologies, including nanoencapsulated forms, microencapsulation nutraceutical applications, and controlled release nutraceuticals, are subject to both EU-level food safety assessments by the European Food Safety Authority (EFSA) and national-level notifications through the Italian Ministry of Health’s dedicated supplement registry.
For vendors, this dual-layer compliance structure requires thorough ingredient safety documentation and, in the case of novel delivery platforms such as solid lipid nanoparticles nutraceuticals, or phytosome technology nutraceuticals, may necessitate novel food authorization under EU Regulation 2015/2283. This regulatory rigor, while operationally demanding, serves as a powerful quality signal for Italian consumers and creates a durable competitive advantage for brands that achieve full compliance.
On the other hand, for investors, the Italian regulatory environment effectively filters out low-quality entrants, ensuring that those who invest in proper substantiation can command premium pricing and strong pharmacy channel placement within the functional nutraceuticals market growth landscape.
Italy also presents compelling nutraceutical R&D trends and investment opportunities, particularly at the intersection of its world-class food science expertise and advanced delivery technology innovation. The country hosts a cluster of highly capable nutraceutical contract manufacturers and ingredient companies, many of which are located in the Veneto and Lombardy regions and specialize in innovative nutraceutical formulations market opportunities.
These manufacturers are investing increasingly in lipid-based nutraceutical delivery systems market growth capabilities, including liposomal and phytosome production, to serve both domestic brands and international clients seeking EU-compliant manufacturing partners. Moreover, Italy’s growing clinical nutrition segment is generating strong demand for targeted nutraceutical delivery technologies, as healthcare providers incorporate advanced supplement absorption technologies into therapeutic nutrition protocols for aging and chronic disease patient populations.
The rise of clean-label delivery systems nutraceuticals is also particularly resonant in Italy, where ingredient transparency and natural sourcing are deeply valued by consumers across all product categories. The integration of smart nutraceutical delivery platforms into Italy’s expanding functional food sector further broadens the innovative nutraceutical formulations market opportunities available to brands and investors. These converging factors are collectively set to sustain the Italy advanced delivery nutraceuticals market growth robustly throughout the forecast period.
To Know More About This Report, Request a Free Sample Copy
SEGMENTATION ANALYSIS
The Italy advanced delivery nutraceuticals market is segmented by delivery technology, product type, and application. The application segment is further categorized into dietary supplements, functional foods and beverages, sports nutrition, clinical nutrition, and other applications.
Clinical nutrition represents one of the most strategically significant and structurally well-supported sub-segments within the Italy advanced delivery nutraceuticals market. Clinical nutrition products are formulated specifically to meet the needs of patients with conditions requiring targeted, precise nutrient delivery, including oncology patients, post-surgical recovery cases, elderly individuals with malabsorption issues, and those managing chronic metabolic diseases.
Italy’s rapidly aging population makes this segment particularly compelling. Italy has one of the oldest population profiles in Europe, with over 24-25% of its population aged 65 or above as of recent census data. This demographic reality directly amplifies clinical demand for advanced oral delivery systems nutraceuticals.
Furthermore, Italian healthcare professionals are increasingly adopting controlled release nutraceuticals and liposomal nutraceutical delivery systems within clinical nutrition protocols. Aligning with this, they also recognize that bioavailability enhancement nutraceuticals meaningfully improve therapeutic outcomes compared to standard formulations.
The integration of personalized nutraceutical delivery systems market insights into clinical settings is also gaining traction, with hospitals and outpatient care facilities beginning to incorporate targeted nutrient delivery recommendations into individualized patient care plans. For vendors operating in this sub-segment, strong clinical evidence generation and active engagement with Italy’s healthcare professional community are essential strategic priorities.
COMPETITIVE INSIGHTS
Some of the top players operating in the Italy advanced delivery nutraceuticals market include Labomar, Gattefossé, Nestlé Health Science, BASF SE, etc.
Labomar is an Italian contract development and manufacturing organization (CDMO) specializing in nutraceuticals and dietary supplements, and it stands out as one of the most strategically relevant domestic players within the Italy advanced delivery nutraceuticals market. Headquartered in Istrana, in the Veneto region, Labomar provides end-to-end services spanning formulation development, clinical substantiation, regulatory support, and full-scale manufacturing for brands seeking science-backed, innovative nutraceutical formulations market opportunities within the EU.
Its product development capabilities are directly aligned with the most in-demand advanced delivery platforms in the European market, including microencapsulation nutraceutical applications, liposomal nutraceutical delivery systems, and sustained release nutraceutical formulations across formats such as softgels, sticks, tablets, and functional beverages. Labomar serves a broad client base of Italian and international nutraceutical brands, positioning it as a key enabler of the encapsulated nutraceuticals market across the region, with a particular strength in combining clean label delivery systems nutraceuticals principles with clinical-grade formulation rigor.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Delivery Technology, Product Type, Application |
| Country Analyzed | Italy |
| Companies Analyzed | Lonza Group, Glanbia Nutritionals, BASF SE, Evonik Industries, Nestlé Health Science, Gattefossé, Labomar |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE, SHARE & ESTIMATES
- MARKET OVERVIEW
- SCOPE OF STUDY
- MAJOR MARKET FINDINGS
- ADVANCED DELIVERY NUTRACEUTICALS ARE GAINING MOMENTUM WITHIN THE BROADER EUROPEAN WELLNESS MARKET
- PHARMACY CHANNELS PLAY A KEY ROLE IN PRODUCT DISTRIBUTION
- CONSUMERS PREFER HIGH-QUALITY AND CLINICALLY VALIDATED PRODUCTS
- INNOVATION IN MICROENCAPSULATION IS DRIVING PRODUCT DIFFERENTIATION
MARKET DYNAMICS
- KEY DRIVERS
- AGING POPULATION IS INCREASING DEMAND FOR HEALTH SUPPLEMENTS
- STRONG TRADITION OF NUTRITION AND WELLNESS SUPPORTS MARKET GROWTH
- ADVANCEMENTS IN DELIVERY TECHNOLOGIES ENHANCE PRODUCT EFFICACY
- EXPANDING PHARMACY AND RETAIL NETWORKS IMPROVE ACCESS
- KEY RESTRAINTS
- REGULATORY COMPLEXITY WITHIN THE EU HINDERS MARKET ENTRY
- HIGH PRODUCT COSTS LIMIT MASS MARKET PENETRATION
- INTENSE COMPETITION FROM ESTABLISHED BRANDS
- LIMITED CONSUMER AWARENESS ABOUT ADVANCED DELIVERY SYSTEMS
- KEY DRIVERS
STRATEGIC MARKET ANALYTICS
- GROWTH METRICS
- TAM, SAM & SOM OPPORTUNITY ANALYSIS
- EMERGING MARKET TRENDS & PARADIGM SHIFTS
- GROWING DEMAND FOR FUNCTIONAL FOODS WITH ENHANCED BIOAVAILABILITY
- RISING USE OF LIPOSOMAL DELIVERY SYSTEMS
- INCREASING FOCUS ON NATURAL AND ORGANIC FORMULATIONS
- EXPANSION OF PREVENTIVE HEALTHCARE PRODUCTS
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- PESTLE ANALYSIS
- POLITICAL
- ECONOMIC
- SOCIAL LANDSCAPE
- TECHNOLOGY
- LEGAL
- ENVIRONMENTAL
- GROWTH OPPORTUNITY MAPPING & HEATMAP
- GROWTH PROSPECT MAPPING FOR THE ITALY
- MARKET MATURITY & LIFECYCLE ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- GROWTH METRICS
ADVANCED DELIVERY NUTRACEUTICALS VALUE CHAIN & DECISION FRAMEWORK
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SOURCING
- ACTIVE INGREDIENT EXTRACTION
- DELIVERY TECHNOLOGY DEVELOPMENT
- FORMULATION DEVELOPMENT
- CONTRACT MANUFACTURING
- BRANDING MARKETING
- DISTRIBUTION CHANNELS
- KEY BUYING CRITERIA
- HIGH BIOAVAILABILITY
- CLINICAL EVIDENCE
- CLEAN LABEL
- COST EFFECTIVENESS
- PRICING MODELS, COST STRUCTURES & PREMIUMIZATION STRATEGIES
- REGULATORY & POLICY LANDSCAPE ANALYSIS
- VALUE CHAIN ANALYSIS
ADVANCED DELIVERY NUTRACEUTICALS MARKET BY DELIVERY TECHNOLOGY
- NANOENCAPSULATED FORMS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- LIPOSOMAL DELIVERY SYSTEMS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- MICROENCAPSULATED FORMS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER DELIVERY TECHNOLOGIES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- NANOENCAPSULATED FORMS
ADVANCED DELIVERY NUTRACEUTICALS MARKET BY PRODUCT TYPE
- DIETARY SUPPLEMENTS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- FUNCTIONAL FOODS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- FUNCTIONAL BEVERAGES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER PRODUCT TYPES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- DIETARY SUPPLEMENTS
ADVANCED DELIVERY NUTRACEUTICALS MARKET BY APPLICATION
- DIETARY SUPPLEMENTS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- FUNCTIONAL FOODS & BEVERAGES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SPORTS NUTRITION
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- CLINICAL NUTRITION
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER APPLICATIONS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- DIETARY SUPPLEMENTS
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPETITOR POSITIONING & DIFFERENTIATION MAP
- COMPANY PROFILES
- LONZA GROUP
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- GLANBIA NUTRITIONALS
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- BASF SE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- EVONIK INDUSTRIES
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- NESTLÉ HEALTH SCIENCE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- GATTEFOSSÉ
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- LABOMAR
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- LONZA GROUP
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – ADVANCED DELIVERY NUTRACEUTICALS MARKET
TABLE 2: PRICING MODELS, COST STRUCTURES & PREMIUMIZATION STRATEGIES
TABLE 3: REGULATORY & POLICY LANDSCAPE ANALYSIS
TABLE 4: MARKET BY DELIVERY TECHNOLOGY, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 5: MARKET BY DELIVERY TECHNOLOGY, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 6: MARKET BY PRODUCT TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 7: MARKET BY PRODUCT TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 8: MARKET BY APPLICATION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 9: MARKET BY APPLICATION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 10: KEY PLAYERS OPERATING IN THE ITALIAN MARKET
TABLE 11: LIST OF MERGERS & ACQUISITIONS
TABLE 12: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 13: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 14: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR ITALY
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY DELIVERY TECHNOLOGY, IN 2025
FIGURE 11: NANOENCAPSULATED FORMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: LIPOSOMAL DELIVERY SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: MICROENCAPSULATED FORMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 14: OTHER DELIVERY TECHNOLOGIES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: SEGMENT GROWTH POTENTIAL, BY PRODUCT TYPE, IN 2025
FIGURE 16: DIETARY SUPPLEMENTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: FUNCTIONAL FOODS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: FUNCTIONAL BEVERAGES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: OTHER PRODUCT TYPES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: SEGMENT GROWTH POTENTIAL, BY APPLICATION, IN 2025
FIGURE 21: DIETARY SUPPLEMENTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: FUNCTIONAL FOODS & BEVERAGES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: SPORTS NUTRITION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: CLINICAL NUTRITION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: OTHER APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-
UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034