Australia Advanced Delivery Nutraceuticals Market by Delivery Technology (Nanoencapsulated Forms, Liposomal Delivery Systems, Microencapsulated Forms, Other Delivery Technologies), Market by Product Type (Dietary Supplements, Functional Foods, Functional Beverages, Other Product Types), Market by Application (Dietary Supplements, Functional Foods & Beverages, Sports Nutrition, Clinical Nutrition, Other Applications), by Geography
AUSTRALIA ADVANCED DELIVERY NUTRACEUTICALS MARKET OVERVIEW
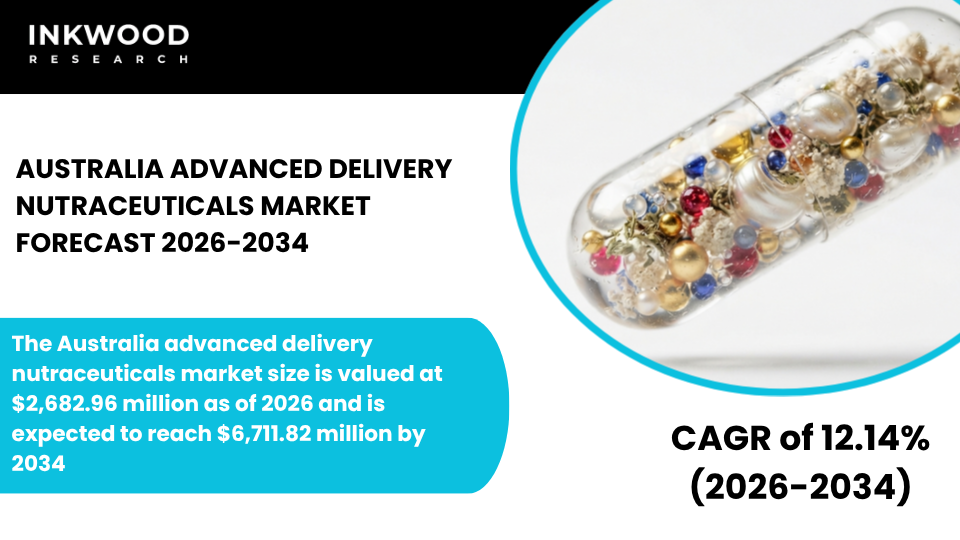
The Australia advanced delivery nutraceuticals market size is valued at $2,682.96 million as of 2026 and is expected to reach $6,711.82 million by 2034, progressing with a CAGR of 12.14% during the forecast years, 2026-2034.
MARKET INSIGHTS
Australia’s advanced delivery nutraceuticals market is one of the most dynamic and high-growth segments within the broader Asia-Pacific nutraceutical innovation market. The country benefits from a highly health-conscious population, strong disposable incomes, and a well-established culture of preventive healthcare.
These characteristics together create ideal conditions for the adoption of bioavailability enhancement nutraceuticals and advanced supplement absorption technologies. Australian consumers are notably discerning, and they increasingly seek out products that are backed by clinical evidence rather than simply ingredient lists.
This consumer sophistication is, in turn, elevating demand for encapsulated nutraceutical market solutions that deliver measurable, proven results, particularly within the dietary supplement, sports nutrition, and functional food categories. Furthermore, the country’s robust retail pharmacy network, including chains such as Chemist Warehouse and Priceline, provides strong last-mile distribution for advanced oral delivery systems nutraceuticals across both urban and regional markets.
The regulatory landscape in Australia plays a defining role in shaping the advanced delivery nutraceuticals market. The Therapeutic Goods Administration (TGA), operating under the Australian Government Department of Health and Aged Care, regulates complementary medicines, including dietary supplements and nutraceuticals that employ advanced delivery technologies.
Products containing novel encapsulation systems, such as nanoencapsulated forms or liposomal nutraceutical delivery systems, are subject to pre-market assessment pathways that ensure safety and quality before they reach consumers. While this regulatory rigor raises the cost and timeline of product approval, it simultaneously serves as a strong quality signal for Australian and international buyers alike.
For vendors and investors, this means that products entering the nutraceutical delivery systems market in Australia must be backed by solid documentation and clinical substantiation, which raises the barrier to entry but also ensures significantly higher consumer trust and willingness to pay premium prices.
Additionally, Complementary Medicines Australia (CMA), the industry’s peak body, actively advocates for evidence-based policy frameworks that support innovation in nutraceutical delivery technology, making regulatory engagement an important strategic consideration for market participants.
Australia’s export orientation is also a key driver of the functional nutraceuticals market growth in the country. Australian nutraceutical manufacturers are increasingly recognized across the Asia-Pacific, particularly in China, Japan, South Korea, and Southeast Asia, for their clean-label credentials and adherence to stringent quality standards.
This export demand is boosting domestic production capacity for controlled release nutraceuticals, microencapsulation nutraceutical applications, and phytosome technology nutraceuticals, as manufacturers scale up to serve both local and international buyers. For investors, this dual-market dynamic, combining a premium domestic consumer base with high-value regional export channels, makes Australia a strategically attractive hub within the global nutraceutical delivery technology market.
Moreover, the country’s growing biotech and life sciences ecosystem, supported by the Australian Government’s Medical Research Future Fund (MRFF), is channeling investment into nutraceutical R&D trends and innovation, further strengthening the pipeline of novel nutraceutical carriers market solutions. These interconnected drivers are collectively set to sustain and accelerate the Australia advanced delivery nutraceuticals market growth throughout the forecast period.
To Know More About This Report, Request a Free Sample Copy
SEGMENTATION ANALYSIS
The Australia advanced delivery nutraceuticals market is segmented by delivery technology, product type, and application. The delivery technology segment is further categorized into nanoencapsulated forms, liposomal delivery systems, microencapsulated forms, and other delivery technologies.
Among these, liposomal delivery systems represent one of the most commercially promising and fastest-growing sub-segments within the Australia advanced delivery nutraceuticals market. Liposomal nutraceutical delivery systems use phospholipid bilayer vesicles to encapsulate active ingredients, enabling them to pass through gastrointestinal barriers more efficiently and reach systemic circulation at significantly higher concentrations than conventional formats.
This makes them particularly well-suited to high-potency applications such as liposomal vitamin C, glutathione, and curcumin, which are among the top-selling premium supplement formats in Australian pharmacies and health specialty retailers. Australian consumers’ strong preference for scientifically validated, clean label products has accelerated the adoption of lipid-based nutraceutical delivery systems, as liposomal formats can be produced using food-grade, naturally derived phospholipids that align well with clean label delivery systems nutraceuticals demand.
Furthermore, the personalized nutrition delivery technologies trend is reinforcing liposomal system adoption, as brands use these platforms to develop tailored nutrient blends with predictable, enhanced absorption profiles. For vendors, liposomal delivery represents a high-margin, differentiated positioning opportunity within the broader encapsulated nutraceuticals market, particularly as Australian consumers show consistent willingness to invest in advanced supplement absorption technologies that are backed by transparent clinical claims.
COMPETITIVE INSIGHTS
Some of the top players operating in the Australia advanced delivery nutraceuticals market include Pharmako Biotechnologies, Nestlé Health Science, DSM Nutritional Products, Evonik Industries, etc.
Pharmako Biotechnologies is an Australian-headquartered bioavailability and delivery science company, and it stands out as one of the most strategically relevant players within the domestic advanced delivery nutraceuticals market. The company specializes in proprietary delivery enhancement platforms designed to maximize the absorption and efficacy of nutraceutical and functional ingredients, with a particular focus on bioavailability enhancement nutraceuticals for the dietary supplement, sports nutrition, and clinical nutrition sectors.
The company’s flagship technology, LipiSperse, is a patented lipid-based dispersion system that improves the water dispersibility of hydrophobic actives such as curcumin and omega-3 fatty acids, directly addressing the core functional challenge within the nutraceutical delivery systems market. Pharmako operates across both the Australian domestic market and key export markets in Asia-Pacific, Europe, and North America, supplying its delivery platforms to global ingredient and supplement brands seeking validated, science-backed differentiation in the encapsulated nutraceuticals market.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Delivery Technology, Product Type, Application |
| Country Analyzed | Australia |
| Companies Analyzed | DSM Nutritional Products, Lonza Group, Arla Foods Ingredients, Evonik Industries, Nestlé Health Science, Gattefossé, Pharmako Biotechnologies, BioNexus Australia |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE, SHARE & ESTIMATES
- MARKET OVERVIEW
- SCOPE OF STUDY
- MAJOR MARKET FINDINGS
- ADVANCED DELIVERY NUTRACEUTICALS ARE GAINING STRONG ACCEPTANCE IN PREMIUM HEALTH SEGMENTS
- HIGH REGULATORY STANDARDS ENSURE PRODUCT QUALITY AND SAFETY
- CONSUMERS SHOW STRONG PREFERENCE FOR SCIENTIFICALLY BACKED FORMULATIONS
- EXPORT-ORIENTED MANUFACTURING IS DRIVING MARKET GROWTH
MARKET DYNAMICS
- KEY DRIVERS
- HIGH HEALTH AWARENESS AMONG CONSUMERS SUPPORTS MARKET EXPANSION
- DEMAND FOR HIGH BIOAVAILABILITY PRODUCTS IS INCREASING
- STRONG RETAIL AND PHARMACY NETWORKS IMPROVE PRODUCT DISTRIBUTION
- GROWING EXPORT DEMAND FROM THE ASIA-PACIFIC REGION BOOSTS PRODUCTION
- KEY RESTRAINTS
- STRINGENT REGULATIONS INCREASE TIME AND COST FOR PRODUCT APPROVAL
- HIGH PRODUCTION COSTS LIMIT COMPETITIVENESS
- SMALL DOMESTIC MARKET SIZE RESTRICTS SCALE
- DEPENDENCE ON IMPORTED RAW MATERIALS CREATES SUPPLY RISKS
- KEY DRIVERS
STRATEGIC MARKET ANALYTICS
- GROWTH METRICS
- TAM, SAM & SOM OPPORTUNITY ANALYSIS
- EMERGING MARKET TRENDS & PARADIGM SHIFTS
- INCREASING DEMAND FOR LIPOSOMAL AND ENCAPSULATED SUPPLEMENTS
- FOCUS ON CLEAN LABEL AND NATURAL INGREDIENTS
- RISING POPULARITY OF FUNCTIONAL BEVERAGES
- INTEGRATION OF PERSONALIZED NUTRITION SOLUTIONS
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- PESTLE ANALYSIS
- POLITICAL
- ECONOMIC
- SOCIAL LANDSCAPE
- TECHNOLOGY
- LEGAL
- ENVIRONMENTAL
- GROWTH OPPORTUNITY MAPPING & HEATMAP
- GROWTH PROSPECT MAPPING FOR THE AUSTRALIA
- MARKET MATURITY & LIFECYCLE ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- GROWTH METRICS
ADVANCED DELIVERY NUTRACEUTICALS VALUE CHAIN & DECISION FRAMEWORK
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SOURCING
- ACTIVE INGREDIENT EXTRACTION
- DELIVERY TECHNOLOGY DEVELOPMENT
- FORMULATION DEVELOPMENT
- CONTRACT MANUFACTURING
- BRANDING MARKETING
- DISTRIBUTION CHANNELS
- KEY BUYING CRITERIA
- HIGH BIOAVAILABILITY
- CLINICAL EVIDENCE
- CLEAN LABEL
- COST EFFECTIVENESS
- PRICING MODELS, COST STRUCTURES & PREMIUMIZATION STRATEGIES
- REGULATORY & POLICY LANDSCAPE ANALYSIS
- VALUE CHAIN ANALYSIS
ADVANCED DELIVERY NUTRACEUTICALS MARKET BY DELIVERY TECHNOLOGY
- NANOENCAPSULATED FORMS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- LIPOSOMAL DELIVERY SYSTEMS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- MICROENCAPSULATED FORMS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER DELIVERY TECHNOLOGIES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- NANOENCAPSULATED FORMS
ADVANCED DELIVERY NUTRACEUTICALS MARKET BY PRODUCT TYPE
- DIETARY SUPPLEMENTS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- FUNCTIONAL FOODS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- FUNCTIONAL BEVERAGES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER PRODUCT TYPES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- DIETARY SUPPLEMENTS
ADVANCED DELIVERY NUTRACEUTICALS MARKET BY APPLICATION
- DIETARY SUPPLEMENTS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- FUNCTIONAL FOODS & BEVERAGES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SPORTS NUTRITION
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- CLINICAL NUTRITION
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER APPLICATIONS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- DIETARY SUPPLEMENTS
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPETITOR POSITIONING & DIFFERENTIATION MAP
- COMPANY PROFILES
- DSM NUTRITIONAL PRODUCTS
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- LONZA GROUP
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- ARLA FOODS INGREDIENTS
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- EVONIK INDUSTRIES
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- NESTLÉ HEALTH SCIENCE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- GATTEFOSSÉ
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- PHARMAKO BIOTECHNOLOGIES
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- BIONEXUS AUSTRALIA
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- DSM NUTRITIONAL PRODUCTS
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – ADVANCED DELIVERY NUTRACEUTICALS MARKET
TABLE 2: PRICING MODELS, COST STRUCTURES & PREMIUMIZATION STRATEGIES
TABLE 3: REGULATORY & POLICY LANDSCAPE ANALYSIS
TABLE 4: MARKET BY DELIVERY TECHNOLOGY, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 5: MARKET BY DELIVERY TECHNOLOGY, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 6: MARKET BY PRODUCT TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 7: MARKET BY PRODUCT TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 8: MARKET BY APPLICATION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 9: MARKET BY APPLICATION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 10: KEY PLAYERS OPERATING IN THE AUSTRALIAN MARKET
TABLE 11: LIST OF MERGERS & ACQUISITIONS
TABLE 12: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 13: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 14: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR AUSTRALIA
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY DELIVERY TECHNOLOGY, IN 2025
FIGURE 11: NANOENCAPSULATED FORMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: LIPOSOMAL DELIVERY SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: MICROENCAPSULATED FORMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 14: OTHER DELIVERY TECHNOLOGIES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: SEGMENT GROWTH POTENTIAL, BY PRODUCT TYPE, IN 2025
FIGURE 16: DIETARY SUPPLEMENTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: FUNCTIONAL FOODS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: FUNCTIONAL BEVERAGES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: OTHER PRODUCT TYPES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: SEGMENT GROWTH POTENTIAL, BY APPLICATION, IN 2025
FIGURE 21: DIETARY SUPPLEMENTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: FUNCTIONAL FOODS & BEVERAGES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: SPORTS NUTRITION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: CLINICAL NUTRITION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: OTHER APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-
UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034