Global Acute Care at Home Market by Service Type (Physician Care Services, Skilled Nursing Services, Diagnostic & Monitoring Services, Therapy Services, Medication Administration Services, Other Acute Care Services) Market by Component (Remote Patient Monitoring Devices, Telehealth & Virtual Care Platforms, Clinical Command Center Software, Therapeutic Equipment, Other Components) Market by Disease Indication (Respiratory Diseases, Cardiovascular Diseases, Infectious Diseases, Renal Disorders, Post-Surgical Care, Other Acute Conditions), by Geography
GLOBAL ACUTE CARE AT HOME MARKET OVERVIEW
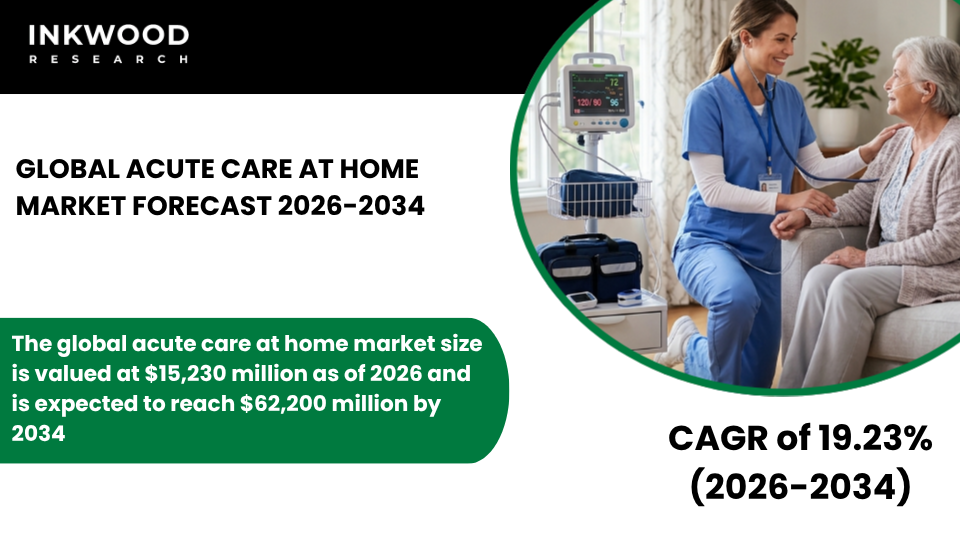
The global acute care at home market size is valued at $15,230 million as of 2026 and is expected to reach $62,200 million by 2034, growing at a CAGR of 19.23% during the forecast period 2026–2034. The base year considered for the study is 2025, and the forecast period is between 2026 and 2034. The market study has also analyzed the crisis impact on the acute care at home market qualitatively as well as quantitatively.
The acute care at home market refers to the delivery of hospital-level medical care within a patient’s residential setting, using an integrated model of in-person clinical visits, telehealth platforms, remote patient monitoring devices, and coordinated care teams. This model covers a broad range of medical services, including physician-led care, skilled nursing, infusion therapy, diagnostic monitoring, and respiratory support, that were historically confined to traditional inpatient hospital settings.
Unlike standard home health services, acute home healthcare is designed for patients with high-acuity conditions who require intensive, time-sensitive clinical intervention but are clinically stable enough to be managed outside a hospital. By combining advanced digital health platforms with hands-on clinical staffing, the acute care at home market enables health systems to extend their care continuum beyond their physical walls, reduce inpatient bed pressure, and improve patient outcomes, all while significantly lowering the overall cost of care.
The global hospital at home market is expanding rapidly, driven by mounting pressure on healthcare systems to reduce costs, improve patient experience, and manage a growing burden of chronic and acute illness. Aging populations across North America, Europe, and the Asia-Pacific are generating increased demand for accessible and continuous care, while simultaneously overwhelming traditional hospital infrastructure.
At the same time, the rapid evolution of remote patient monitoring technology, AI-driven analytics, and telehealth platforms has made it clinically feasible to deliver hospital-grade care in home settings, with outcomes comparable to or better than conventional inpatient care. Government-backed reimbursement frameworks, such as the U.S. Centers for Medicare & Medicaid Services (CMS) Acute Hospital Care at Home (AHCAH) initiative, have further accelerated adoption across major markets. Together, these dynamics are fueling the sustained growth of the acute care at home services industry.
To Know More About This Report, Request a Free Sample Copy
GROWTH ENABLERS
Key enablers of the global acute care at home market growth:
- Rising healthcare costs are driving demand for lower-cost alternatives such as home-based acute care models
- Increasing prevalence of chronic diseases is fueling the need for continuous and accessible acute care solutions
- Advancements in remote patient monitoring and connected medical devices are supporting safe home-based treatment
- Government initiatives and reimbursement policies are encouraging the expansion of hospital at home programs
- Government initiatives are playing a decisive role in shaping the acute home healthcare market globally. In the United States, the CMS Acute Hospital Care at Home initiative, launched in November 2020 and subsequently extended multiple times, has become a cornerstone of federal care delivery policy. According to CMS, as of October 2024, 366 hospitals across 38 states had participated in the program, collectively serving over 31,000 patients.
- The American Hospital Association (AHA) reported that by September 2025, this figure had grown to 419 approved hospitals across 147 systems in 39 states. In December 2025, the House of Representatives passed the Hospital Inpatient Services Modernization Act (H.R. 4313), which proposes to extend hospital at home programs through 2030. This sustained legislative support signals a long-term structural shift toward home-based acute care delivery, providing both hospitals and technology providers with a stable policy environment to invest in and scale their acute care home services.
Key growth restraining factors of the global acute care at home market:
- Limited reimbursement consistency across regions is hindering the large-scale adoption of acute care at home models
- Concerns regarding patient safety and emergency response capabilities in home settings restrict market growth
- Lack of standardized clinical protocols creates operational challenges for healthcare providers
- High initial investment in technology infrastructure and workforce training acts as a barrier for market entry
- The high upfront capital requirement for technology infrastructure and workforce training remains one of the most significant barriers in the acute care at home market. Standing up a viable hospital at home program demands substantial investment in remote monitoring devices, telehealth platforms, supply chain logistics, clinical command center software, and staff education, all before a single patient is enrolled.
- While over 370 hospitals have received CMS waivers, implementation experience and program scale vary widely, with many approved hospitals struggling to launch or grow their programs to clinically and financially meaningful levels. For smaller health systems and providers in lower-income regions, these cost barriers effectively preclude participation in the home-based acute care market, limiting the market’s equitable expansion despite growing patient demand.
KEY MARKET TRENDS
Global Acute Care at Home Industry | Top Trends
- The use of artificial intelligence and predictive analytics is fundamentally transforming how clinical decisions are made within the acute care home model market. AI-powered algorithms, such as those developed by Biofourmis, which received FDA clearance, continuously analyze real-time patient data to identify early warning signs of deterioration, enabling proactive interventions that reduce emergency escalations. As health systems integrate these tools into their clinical command centers, AI is becoming a standard feature of the acute home healthcare market rather than a novel add-on.
- Strategic alliances between hospital systems and digital health companies are rapidly reshaping the competitive landscape of the hospital at home market. A landmark example is the partnership between GE HealthCare and Biofourmis, announced in February 2024. Through this, GE HealthCare began distributing Biofourmis’ FDA-cleared, AI-guided virtual care-at-home solutions to U.S. customers from Q1 2024. These collaborations extend the care continuum from the inpatient hospital setting into the home, combining established clinical infrastructure with advanced remote monitoring capabilities. Such partnerships are accelerating the scalability of acute care at home services and broadening market reach across health systems.
- The growing shift toward value-based care reimbursement structures is directly accelerating the adoption of home-based acute care models. Because acute care at home programs typically lower direct costs of care and reduce hospital readmissions, while maintaining comparable or superior clinical outcomes, they align closely with the incentives embedded in value-based payment models. Research indicates that hospital at home care can reduce care costs by up to 30% compared to traditional inpatient settings. Payers and health systems are increasingly recognizing this alignment, with commercial insurers and Medicare Advantage plans expanding coverage for home-based acute care delivery, further strengthening the market outlook.
- Shifting patient preferences are an increasingly important driver of the acute care at home market. Aligning with this, more than two-thirds of Americans aged 60–79 express a desire to remain at home in their later years, a demographic trend that directly supports demand for home-based acute care services. Patients receiving care at home consistently report higher satisfaction scores compared to those treated in hospital settings. Moreover, home settings reduce exposure to hospital-acquired infections, lower fall risks, and support faster psychological recovery. These patient-centric outcomes are reinforcing the clinical and commercial case for expanding the acute care home model market globally.
MARKET SEGMENTATION
Market Segmentation – Service Type, Component, and Disease Indication –
Market by Service Type:
- Physician Care Services
- Physician care services represent the clinical core of the acute care at home market. This sub-segment encompasses physician-led visits, both in-person and via telehealth, that form the supervisory backbone of home-based acute care programs. Under models like the CMS Acute Hospital Care at Home initiative, eligible patients must be enrolled under a physician’s orders, with care teams including attending physicians who conduct daily virtual rounds and direct clinical decision-making.
- Physician care services are distinguished by their role in patient triage, diagnosis, treatment planning, and real-time clinical escalation, functions that historically required inpatient hospitalization. The growth of this sub-segment is driven by expanding telemedicine infrastructure, which enables physicians to evaluate and manage high-acuity patients remotely with clinical-grade monitoring data.
- Programs such as Kaiser Permanente’s Advanced Care at Home, which integrates home visits, telehealth encounters, and remote patient monitoring coordinated through specialist command centers, exemplify how physician care services anchor the broader acute home healthcare model. As more health systems build physician-led care protocols for the home setting, this sub-segment is expected to remain a primary growth engine within the acute care at home services industry.
- Skilled Nursing Services
- Diagnostic & Monitoring Services
- Therapy Services (Physical / Occupational / Respiratory)
- Medication Administration Services
- Other Acute Care Services
Market by Component:
- Remote Patient Monitoring Devices
- Telehealth & Virtual Care Platforms
- Clinical Command Center Software
- Therapeutic Equipment
- Other Components
Market by Disease Indication:
- Respiratory Diseases
- Cardiovascular Diseases
- Infectious Diseases
- Renal Disorders
- Post-Surgical Care
- Other Acute Conditions
Geographical Study based on Four Major Regions:
North America: The United States and Canada
- The North America acute care at home market size is valued at $6,653.42 million as of 2026 and is expected to reach $24,231.43 million by 2034, growing at a CAGR of 17.53% during the forecast period 2026–2034.
- North America dominates the global hospital at home market, underpinned by a mature digital health infrastructure, strong regulatory momentum, and high rates of chronic disease prevalence.
- In the United States, the CMS Acute Hospital Care at Home initiative has been the most significant institutional catalyst for market growth, with 419 hospitals across 39 states approved under the program as of September 2025, per the AHA.
- A landmark development came in December 2025, when the House passed the Hospital Inpatient Services Modernization Act to extend hospital at home programs through 2030, providing long-term investment certainty for health systems and technology providers.
- Notably, Ochsner Health in New Orleans launched an acute care at home program in 2024 that saved over 1,000 bed-days in less than a year, according to the American Medical Association (AMA).
- In Canada, the Ontario government committed CAD 1.1 billion over three years to expand its Hospital to Home (H2H) program, reflecting similar policy support for the home-based acute care market across the region.
Europe: The United Kingdom, Germany, France, Italy, Spain, Poland, Belgium, and Rest of Europe
- The Europe acute care at home market size is valued at $4,204.32 million as of 2026 and is expected to reach $15,903.89 million by 2034, growing at a CAGR of 18.09% during the forecast period 2026–2034.
- Europe represents a diverse and rapidly evolving landscape for the acute care at home services market, shaped by aging demographics, strained public health systems, and growing national commitments to home-based care delivery.
- In the United Kingdom, companies like Doccla have developed virtual bed technology enabling early hospital discharge and remote patient management, raising USD 46 million in September 2024 to fund expansion across Europe.
- Germany’s acute home healthcare market is advancing through digital health infrastructure investments and a regulatory environment that increasingly supports outpatient and home-based treatment pathways.
- Additionally, Spain has emerged as a key growth market, with Air Liquide winning a major government contract in September 2025 to deliver home respiratory care to 70,000 patients in the Community of Madrid. This demonstrates how public procurement is driving commercial scale in the home-based acute care market across Europe.
Asia-Pacific: China, India, Japan, Australia & New Zealand, South Korea, Thailand, Indonesia, Vietnam, Singapore, and Rest of Asia-Pacific
- The Asia-Pacific acute care at home market size is valued at $3,281.57 million as of 2026 and is expected to reach $17,348.91 million by 2034, growing at a CAGR of 23.14% during the forecast period 2026–2034.
- Asia-Pacific is emerging as the fastest-growing region in the global acute home healthcare market, driven by severe hospital capacity constraints, rapidly aging populations, and accelerating healthcare digitalization.
- China is investing heavily in digital health infrastructure and telemedicine platforms as part of its broader healthcare reform agenda, creating a large and expanding opportunity for the acute care home model market.
- Japan, one of the world’s most rapidly aging societies, is advancing its home-based medical care framework through government-backed community care initiatives that increasingly incorporate remote monitoring and virtual care.
- Meanwhile, markets such as India, Indonesia, and Vietnam are experiencing rising demand for affordable, scalable acute care at home services, with private healthcare providers and insurers beginning to pilot hospital-at-home programs to address infrastructure gaps.
- Across the region, increasing smartphone penetration, investment in connected medical devices, and greater telemedicine adoption are collectively strengthening the foundation for long-term growth in the Asia-Pacific acute care at home market.
Rest of World: Latin America, the Middle East & Africa
Our market research reports offer an in-depth analysis of individual country-level market size and growth statistics. We cover the segmentation analysis, key growth factors, and macro-economic trends within the acute care at home market, providing detailed insights into –
MAJOR PLAYERS
The major players in the global acute care at home market are:
- DispatchHealth
- Amedisys (Contessa Health Division)
- Biofourmis
- Current Health (part of Best Buy Health)
- Philips Healthcare
Key strategies adopted by some of these companies:
- In March 2025, DispatchHealth and Boston-based Medically Home completed a strategic merger to form the largest advanced at-home care provider in the United States. The combined entity now operates across 50 major metropolitan areas in partnership with nearly 40 health systems and most major health plans. Moreover, it delivers a full spectrum of care from same-day urgent visits to complex, hospital-level acute care at home, directly strengthening its position in the home-based acute care market.
- In February 2024, GE HealthCare and Biofourmis announced a strategic collaboration to extend patient monitoring capabilities from the hospital into the home. Beginning Q1 2024, GE HealthCare began distributing Biofourmis’ FDA-cleared, AI-guided remote monitoring solutions to U.S. health systems, enabling care teams to manage high-acuity patients in the home setting with real-time clinical insights. This partnership is significant because it bridges established hospital infrastructure with advanced virtual care-at-home technology, accelerating adoption of the acute care home model market.
- In September 2025, Air Liquide was awarded a major contract by the Community of Madrid in Spain to deliver home-based respiratory care to 70,000 patients with chronic conditions, including COPD and sleep apnea. This business expansion highlights the growing role of institutional procurement in scaling acute care at home services across Europe, and illustrates how public health systems are actively embedding home-based acute care delivery into national healthcare frameworks.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Service Type, Component, Disease Indication |
| Geographies Analyzed | North America, Europe, Asia-Pacific, Rest of World |
| Companies Analyzed | DispatchHealth, Amedisys (Contessa Health division), Biofourmis, Current Health (part of Best Buy Health), Philips Healthcare, AlayaCare, Amwell, GE HealthCare, Cardinal Health Velocare |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY & KEY INSIGHTS
- MARKET SIZE, SHARE & ESTIMATES
- MARKET OVERVIEW
- SCOPE OF STUDY
- MAJOR MARKET FINDINGS
- THE ACUTE CARE AT HOME MARKET IS WITNESSING RAPID ADOPTION AS HEALTH SYSTEMS SHIFT TOWARD COST-EFFICIENT AND PATIENT-CENTRIC CARE DELIVERY MODELS
- TECHNOLOGICAL INTEGRATION INCLUDING REMOTE MONITORING AND TELEHEALTH PLATFORMS IS ENABLING HOSPITAL-LEVEL CARE IN HOME SETTINGS
- NORTH AMERICA LEADS THE MARKET DUE TO FAVORABLE REIMBURSEMENT FRAMEWORKS AND ADVANCED DIGITAL HEALTH INFRASTRUCTURE
- ASIA-PACIFIC IS EMERGING AS A HIGH-GROWTH REGION DRIVEN BY HEALTHCARE CAPACITY CONSTRAINTS AND INCREASING DIGITALIZATION
MARKET DYNAMICS
- KEY DRIVERS
- RISING HEALTHCARE COSTS ARE DRIVING DEMAND FOR LOWER-COST ALTERNATIVES SUCH AS HOME-BASED ACUTE CARE MODELS
- INCREASING PREVALENCE OF CHRONIC DISEASES IS FUELING THE NEED FOR CONTINUOUS AND ACCESSIBLE ACUTE CARE SOLUTIONS
- ADVANCEMENTS IN REMOTE PATIENT MONITORING AND CONNECTED MEDICAL DEVICES ARE SUPPORTING SAFE HOME-BASED TREATMENT
- GOVERNMENT INITIATIVES AND REIMBURSEMENT POLICIES ARE ENCOURAGING THE EXPANSION OF HOSPITAL-AT-HOME PROGRAMS
- KEY RESTRAINTS
- LIMITED REIMBURSEMENT CONSISTENCY ACROSS REGIONS IS HINDERING THE LARGE-SCALE ADOPTION OF ACUTE CARE AT HOME MODELS
- CONCERNS REGARDING PATIENT SAFETY AND EMERGENCY RESPONSE CAPABILITIES IN HOME SETTINGS RESTRICT MARKET GROWTH
- LACK OF STANDARDIZED CLINICAL PROTOCOLS CREATES OPERATIONAL CHALLENGES FOR HEALTHCARE PROVIDERS
- HIGH INITIAL INVESTMENT IN TECHNOLOGY INFRASTRUCTURE AND WORKFORCE TRAINING ACTS AS A BARRIER FOR MARKET ENTRY
- KEY DRIVERS
STRATEGIC MARKET ANALYTICS
- GROWTH METRICS
- TAM, SAM & SOM OPPORTUNITY ANALYSIS
- EMERGING MARKET TRENDS & PARADIGM SHIFTS
- INTEGRATION OF AI AND PREDICTIVE ANALYTICS IS IMPROVING CLINICAL DECISION-MAKING IN HOME-BASED ACUTE CARE SETTINGS
- PARTNERSHIPS BETWEEN HOSPITALS AND DIGITAL HEALTH COMPANIES ARE EXPANDING SERVICE CAPABILITIES AND MARKET REACH
- INCREASING FOCUS ON VALUE-BASED CARE MODELS IS ACCELERATING THE SHIFT TOWARD HOME-BASED ACUTE CARE DELIVERY
- GROWING PATIENT PREFERENCE FOR COMFORTABLE AND CONVENIENT CARE SETTINGS IS DRIVING DEMAND FOR HOME-BASED SERVICES
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- PESTLE ANALYSIS
- POLITICAL
- ECONOMIC
- SOCIAL LANDSCAPE
- TECHNOLOGY
- LEGAL
- ENVIRONMENTAL
- GROWTH OPPORTUNITY MAPPING & HEATMAP
- GROWTH PROSPECT MAPPING FOR NORTH AMERICA
- GROWTH PROSPECT MAPPING FOR EUROPE
- GROWTH MAPPING PROSPECT FOR ASIA-PACIFIC
- GROWTH MAPPING PROSPECT FOR REST OF WORLD
- MARKET MATURITY & LIFECYCLE ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- GROWTH METRICS
ACUTE CARE AT HOME VALUE CHAIN & DECISION FRAMEWORK
- VALUE CHAIN ANALYSIS
- MEDICAL DEVICE SUPPLIERS
- TECHNOLOGY PROVIDERS
- HEALTHCARE PROVIDERS
- HOME CARE SERVICES
- PAYERS INSURERS
- PATIENT MONITORING
- KEY BUYING CRITERIA
- CLINICAL EFFECTIVENESS
- COST EFFICIENCY
- TECHNOLOGY INTEGRATION
- PATIENT SAFETY
- PRICING MODELS, REIMBURSEMENT STRUCTURES & CARE DELIVERY OPTIMIZATION STRATEGIES
- REGULATORY & POLICY LANDSCAPE ANALYSIS
- VALUE CHAIN ANALYSIS
ACUTE CARE AT HOME MARKET BY SERVICE TYPE
- PHYSICIAN CARE SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SKILLED NURSING SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- DIAGNOSTIC & MONITORING SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- THERAPY SERVICES (PHYSICAL / OCCUPATIONAL / RESPIRATORY)
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- MEDICATION ADMINISTRATION SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER ACUTE CARE SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PHYSICIAN CARE SERVICES
ACUTE CARE AT HOME MARKET BY COMPONENT
- REMOTE PATIENT MONITORING DEVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- TELEHEALTH & VIRTUAL CARE PLATFORMS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- CLINICAL COMMAND CENTER SOFTWARE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- THERAPEUTIC EQUIPMENT
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER COMPONENTS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- REMOTE PATIENT MONITORING DEVICES
ACUTE CARE AT HOME MARKET BY DISEASE INDICATION
- RESPIRATORY DISEASES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- CARDIOVASCULAR DISEASES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- INFECTIOUS DISEASES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- RENAL DISORDERS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- POST-SURGICAL CARE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER ACUTE CONDITIONS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- RESPIRATORY DISEASES
GEOGRAPHICAL ANALYSIS
- NORTH AMERICA
- MARKET SIZE & ESTIMATES
- NORTH AMERICA ACUTE CARE AT HOME MARKET DRIVERS
- NORTH AMERICA ACUTE CARE AT HOME MARKET CHALLENGES
- KEY REGIONAL PLAYERS & ECOSYSTEM
- COUNTRY ANALYSIS
- UNITED STATES
- UNITED STATES ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- CANADA
- CANADA ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- UNITED STATES
- EUROPE
- MARKET SIZE & ESTIMATES
- EUROPE ACUTE CARE AT HOME MARKET DRIVERS
- EUROPE ACUTE CARE AT HOME MARKET CHALLENGES
- KEY REGIONAL PLAYERS & ECOSYSTEM
- COUNTRY ANALYSIS
- UNITED KINGDOM
- UNITED KINGDOM ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- GERMANY
- GERMANY ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- FRANCE
- FRANCE ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- ITALY
- ITALY ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- SPAIN
- SPAIN ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- BELGIUM
- BELGIUM ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- POLAND
- POLAND ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- REST OF EUROPE
- REST OF EUROPE ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- UNITED KINGDOM
- ASIA-PACIFIC
- MARKET ESTIMATES & SIZES
- ASIA-PACIFIC ACUTE CARE AT HOME MARKET DRIVERS
- ASIA-PACIFIC ACUTE CARE AT HOME MARKET CHALLENGES
- KEY REGIONAL PLAYERS & ECOSYSTEM
- COUNTRY ANALYSIS
- CHINA
- CHINA ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- JAPAN
- JAPAN ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- AUSTRALIA & NEW ZEALAND
- AUSTRALIA & NEW ZEALAND ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- INDIA
- INDIA ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- SOUTH KOREA
- SOUTH KOREA ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- INDONESIA
- INDONESIA ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- THAILAND
- THAILAND ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- VIETNAM
- VIETNAM ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- SINGAPORE
- SINGAPORE ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- REST OF ASIA-PACIFIC
- REST OF ASIA-PACIFIC ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- CHINA
- REST OF WORLD
- MARKET ESTIMATES & SIZES
- REST OF WORLD ACUTE CARE AT HOME MARKET DRIVERS
- REST OF WORLD ACUTE CARE AT HOME MARKET CHALLENGES
- KEY REGIONAL PLAYERS & ECOSYSTEM
- REGIONAL ANALYSIS
- LATIN AMERICA
- LATIN AMERICA ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- MIDDLE EAST & AFRICA
- MIDDLE EAST & AFRICA ACUTE CARE AT HOME MARKET SIZE & OPPORTUNITIES
- LATIN AMERICA
- NORTH AMERICA
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPETITOR POSITIONING & DIFFERENTIATION MAP
- COMPANY PROFILES
- DISPATCHHEALTH
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- AMEDISYS (CONTESSA HEALTH DIVISION)
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- BIOFOURMIS
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- CURRENT HEALTH (PART OF BEST BUY HEALTH)
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- PHILIPS HEALTHCARE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- ALAYACARE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- AMWELL
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- GE HEALTHCARE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- CARDINAL HEALTH VELOCARE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- DISPATCHHEALTH
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – ACUTE CARE AT HOME MARKET
TABLE 2: PRICING MODELS, REIMBURSEMENT STRUCTURES & CARE DELIVERY OPTIMIZATION STRATEGIES
TABLE 3: REGULATORY & POLICY LANDSCAPE ANALYSIS
TABLE 4: MARKET BY SERVICE TYPE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 5: MARKET BY SERVICE TYPE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 6: PHYSICIAN CARE SERVICES MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 7: PHYSICIAN CARE SERVICES MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 8: SKILLED NURSING SERVICES MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 9: SKILLED NURSING SERVICES MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 10: DIAGNOSTIC & MONITORING SERVICES MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 11: DIAGNOSTIC & MONITORING SERVICES MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 12: THERAPY SERVICES (PHYSICAL / OCCUPATIONAL / RESPIRATORY) MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 13: THERAPY SERVICES (PHYSICAL / OCCUPATIONAL / RESPIRATORY) MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 14: MEDICATION ADMINISTRATION SERVICES MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 15: MEDICATION ADMINISTRATION SERVICES MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 16: OTHER ACUTE CARE SERVICES MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 17: OTHER ACUTE CARE SERVICES MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 18: MARKET BY COMPONENT, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 19: MARKET BY COMPONENT, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 20: REMOTE PATIENT MONITORING DEVICES MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 21: REMOTE PATIENT MONITORING DEVICES MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 22: TELEHEALTH & VIRTUAL CARE PLATFORMS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 23: TELEHEALTH & VIRTUAL CARE PLATFORMS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 24: CLINICAL COMMAND CENTER SOFTWARE MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 25: CLINICAL COMMAND CENTER SOFTWARE MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 26: THERAPEUTIC EQUIPMENT MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 27: THERAPEUTIC EQUIPMENT MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 28: OTHER COMPONENTS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 29: OTHER COMPONENTS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 30: MARKET BY DISEASE INDICATION, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 31: MARKET BY DISEASE INDICATION, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 32: RESPIRATORY DISEASES MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 33: RESPIRATORY DISEASES MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 34: CARDIOVASCULAR DISEASES MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 35: CARDIOVASCULAR DISEASES MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 36: INFECTIOUS DISEASES MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 37: INFECTIOUS DISEASES MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 38: RENAL DISORDERS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 39: RENAL DISORDERS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 40: POST-SURGICAL CARE MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 41: POST-SURGICAL CARE MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 42: OTHER ACUTE CONDITIONS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 43: OTHER ACUTE CONDITIONS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 44: MARKET BY GEOGRAPHICAL ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 45: MARKET BY GEOGRAPHICAL ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 46: NORTH AMERICA MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 47: NORTH AMERICA MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 48: KEY PLAYERS OPERATING IN THE NORTH AMERICAN MARKET
TABLE 49: EUROPE MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 50: EUROPE MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 51: KEY PLAYERS OPERATING IN THE EUROPEAN MARKET
TABLE 52: ASIA-PACIFIC MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 53: ASIA-PACIFIC MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 54: KEY PLAYERS OPERATING IN THE ASIA-PACIFIC MARKET
TABLE 55: REST OF WORLD MARKET, REGIONAL ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 56: REST OF WORLD MARKET, REGIONAL ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 57: KEY PLAYERS OPERATING IN THE REST OF WORLD MARKET
TABLE 58: LIST OF MERGERS & ACQUISITIONS
TABLE 59: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 60: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 61: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR NORTH AMERICA
FIGURE 6: GROWTH PROSPECT MAPPING FOR EUROPE
FIGURE 7: GROWTH PROSPECT MAPPING FOR ASIA-PACIFIC
FIGURE 8: GROWTH PROSPECT MAPPING FOR REST OF WORLD
FIGURE 9: MARKET MATURITY ANALYSIS
FIGURE 10: MARKET CONCENTRATION ANALYSIS
FIGURE 11: VALUE CHAIN ANALYSIS
FIGURE 12: KEY BUYING CRITERIA
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY SERVICE TYPE, IN 2025
FIGURE 14: PHYSICIAN CARE SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: SKILLED NURSING SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: DIAGNOSTIC & MONITORING SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: THERAPY SERVICES (PHYSICAL / OCCUPATIONAL / RESPIRATORY) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: MEDICATION ADMINISTRATION SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: OTHER ACUTE CARE SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: SEGMENT GROWTH POTENTIAL, BY COMPONENT, IN 2025
FIGURE 21: REMOTE PATIENT MONITORING DEVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: TELEHEALTH & VIRTUAL CARE PLATFORMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: CLINICAL COMMAND CENTER SOFTWARE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: THERAPEUTIC EQUIPMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: OTHER COMPONENTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: SEGMENT GROWTH POTENTIAL, BY DISEASE INDICATION, IN 2025
FIGURE 27: RESPIRATORY DISEASES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: CARDIOVASCULAR DISEASES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 29: INFECTIOUS DISEASES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: RENAL DISORDERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: POST-SURGICAL CARE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 32: OTHER ACUTE CONDITIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 33: NORTH AMERICA ACUTE CARE AT HOME MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 34: UNITED STATES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 35: CANADA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 36: EUROPE ACUTE CARE AT HOME MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 37: GERMANY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 38: UNITED KINGDOM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 39: FRANCE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 40: ITALY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 41: SPAIN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 42: BELGIUM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 43: POLAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 44: REST OF EUROPE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 45: ASIA-PACIFIC ACUTE CARE AT HOME MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 46: CHINA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 47: INDIA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 48: JAPAN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 49: AUSTRALIA & NEW ZEALAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 50: SOUTH KOREA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 51: THAILAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 52: INDONESIA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 53: VIETNAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 54: SINGAPORE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 55: REST OF ASIA-PACIFIC MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 56: REST OF WORLD ACUTE CARE AT HOME MARKET, REGIONAL OUTLOOK, 2025 & 2034 (IN %)
FIGURE 57: LATIN AMERICA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 58: MIDDLE EAST & AFRICA MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
FAQs
The global acute care at home market is valued at $15.23 billion in 2026 and is projected to reach $62.20 billion by 2034, growing at a CAGR of 19.23%. This high growth rate reflects increasing demand for cost-effective, patient-centric alternatives to traditional hospitalization across major global markets.
The hospital at home market is being driven by rising healthcare costs, the growing prevalence of chronic and acute diseases, advancements in remote patient monitoring and telehealth platforms, and supportive government reimbursement policies such as the CMS Acute Hospital Care at Home initiative in the United States. These factors are collectively accelerating the shift from facility-based to home-based acute care delivery.
North America currently leads the global acute home healthcare market, driven by the CMS Acute Hospital Care at Home program, an advanced digital health infrastructure, and strong private-sector investment in hospital-at-home programs. As of September 2025, over 419 hospitals across 39 U.S. states had been approved to deliver hospital-level care at home under federal waivers.
The home-based acute care market is segmented by service type (physician care, skilled nursing, diagnostic & monitoring, therapy services, medication administration), by component (remote patient monitoring devices, telehealth platforms, clinical command center software, therapeutic equipment), and by disease indication (respiratory, cardiovascular, infectious diseases, renal disorders, and post-surgical care).
The acute care at home services industry faces challenges, including inconsistent reimbursement policies across regions, patient safety concerns related to emergency response in home settings, a lack of standardized clinical protocols, and the high initial cost of technology infrastructure and workforce training. These barriers particularly affect smaller health systems and providers in lower-income markets.
Leading players in the global acute care at home market include DispatchHealth, Amedisys (Contessa Health division), Biofourmis, Current Health (part of Best Buy Health), Philips Healthcare, AlayaCare, Amwell, GE HealthCare, and Cardinal Health Velocare. These companies are competing through strategic partnerships, technology innovation, and geographic expansion to capture growing demand for home-based acute care models.
RELATED REPORTS
-
LATIN AMERICA FACIAL RECOGNITION MARKET FORECAST 2019-2028
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
JAPAN AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
INDIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034