Germany Acute Care at Home Market by Service Type (Physician Care Services, Skilled Nursing Services, Diagnostic & Monitoring Services, Therapy Services, Medication Administration Services, Other Acute Care Services) Market by Component (Remote Patient Monitoring Devices, Telehealth & Virtual Care Platforms, Clinical Command Center Software, Therapeutic Equipment, Other Components) Market by Disease Indication (Respiratory Diseases, Cardiovascular Diseases, Infectious Diseases, Renal Disorders, Post-Surgical Care, Other Acute Conditions), by Geography
GERMANY ACUTE CARE AT HOME MARKET OVERVIEW
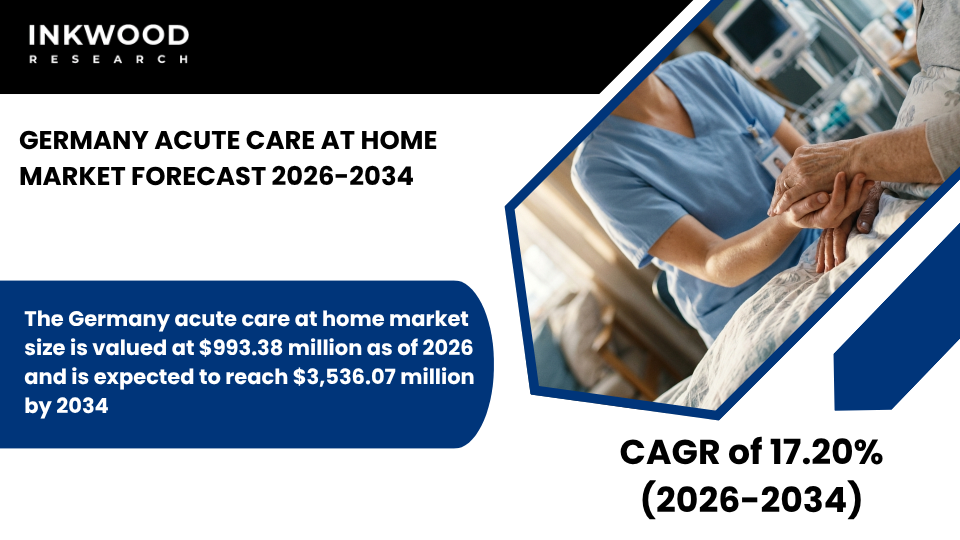
The Germany acute care at home market size is valued at $993.38 million as of 2026 and is expected to reach $3,536.07 million by 2034, progressing with a CAGR of 17.20% during the forecast years, 2026–2034.
MARKET INSIGHTS
Germany’s acute care at home market is developing within one of Europe’s most rigorously regulated and digitally ambitious healthcare systems. The German federal government has enacted a series of landmark legislative reforms that are directly shaping the growth trajectory of the home-based acute care market.
The Digital Healthcare Act (DVG), introduced in 2019 and expanded through the Digital Act (DigiG) in March 2024, established a statutory reimbursement pathway for digital health applications, known as DiGA, covering approximately 90% of the German population through statutory health insurance (SHI). Plus, according to the German Federal Ministry of Health (Bundesgesundheitsministerium), the government has committed €200 million per year to its healthcare innovation fund to accelerate the integration of proven digital care approaches.
Furthermore, the number of approved DiGAs grew from 24 at the end of 2021 to 68 by late 2024, with cumulative reimbursements reaching €234 million by December 2024 and statutory health insurer (GKV) expenditure increasing by 71% between 2023 and 2024. These developments are creating a structured and increasingly reimbursable environment for telehealth and remote monitoring tools that underpin the acute home healthcare market in Germany.
A major policy shift embedded in the Digital Act of 2024 is particularly consequential for the acute care at home services market. For the first time, the DiGA framework was extended to include class IIb medical devices, which cover more complex diagnostic and monitoring tools used in the management of serious or life-threatening conditions.
This regulatory expansion enables remote telemonitoring solutions to qualify for statutory reimbursement, opening a significant commercial opportunity for device manufacturers and digital health providers operating in the home-based acute care space. Additionally, from January 2025, an electronic patient record (ePA) was automatically activated for all 73 million statutorily insured Germans under an opt-out model, as noted by Germany Trade & Invest (GTAI).
This interoperable digital infrastructure lays a critical foundation for coordinated home-based care delivery, enabling seamless data sharing between hospital physicians, home care providers, and remote monitoring platforms. For vendors and investors, these legislative milestones signal durable, policy-backed demand for scalable digital health solutions within the German acute care home market. These factors, in turn, are set to sustain and accelerate the acute care at home market growth in Germany during the forecast period.
To Know More About This Report, Request a Free Sample Copy
SEGMENTATION ANALYSIS
The Germany acute care at home market is segmented by service type, component, and disease indication. The component segment is further categorized into remote patient monitoring devices, telehealth and virtual care platforms, clinical command center software, therapeutic equipment, and other components.
Telehealth and virtual care platforms represent one of the most strategically pivotal and rapidly advancing sub-segments within the Germany acute care at home market. This sub-segment encompasses software-based systems and digital infrastructure that enable real-time video consultations, remote physician oversight, clinical data transmission, and multi-disciplinary care coordination between home-based patients and hospital command centers.
In the German context, the significance of this sub-segment is amplified by the Digital Act (DigiG) of March 2024, which lifted the previously existing 30% cap on telemedicine consultations, thereby allowing physicians to provide an unlimited proportion of their patient interactions via telehealth, per CMS Law. This regulatory change removes one of the most material structural barriers to scaling virtual care delivery in the home setting.
Additionally, the mandated rollout of electronic patient records (ePA) to all 73 million statutorily insured individuals from January 2025 provides the interoperable data backbone that telehealth platforms require to function effectively across care settings. For technology providers, this sub-segment represents the highest-leverage entry point into the Germany acute care home services market, as demand for compliant, SHI-reimbursable virtual care tools accelerates across hospitals, home care providers, and integrated care networks.
COMPETITIVE INSIGHTS
Some of the top players operating in the Germany acute care at home market include Fresenius Kabi, Actimi GmbH, Caspar Health, and Careship, among others.
Fresenius Kabi is a Bad Homburg-based global healthcare company and a wholly owned subsidiary of the Fresenius SE & Co. KGaA healthcare group. In the context of the Germany acute care at home market, Fresenius Kabi is a leading provider of home infusion therapy, delivering intravenous drug administration, parenteral nutrition, and clinical nutrition solutions to critically and chronically ill patients outside of hospital settings.
The company operates an extensive global manufacturing network, including key production facilities in Friedberg, Germany, and reported sales of more than €8.5 billion in 2025. Its portfolio of infusion pumps, IV drug systems, and clinical nutrition products forms a core part of high-acuity home care delivery, particularly for patients with oncological, infectious, and renal conditions requiring ongoing medication administration at home.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Service Type, Component, Disease Indication |
| Country Analyzed | Germany |
| Companies Analyzed | Careship, Veyo Care, Home Therapie Management GmbH, Smart Care, Actimi GmbH, Caspar Health, Nui Care GmbH, Fresenius Kabi |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE, SHARE & ESTIMATES
- MARKET OVERVIEW
- SCOPE OF STUDY
- MAJOR MARKET FINDINGS
- GERMANY’S ACUTE CARE AT HOME MARKET IS EMERGING WITH STRONG SUPPORT FROM DIGITAL HEALTH REFORMS AND TELEMEDICINE ADOPTION
- STATUTORY HEALTH INSURANCE COVERAGE IS EXPANDING TO INCLUDE CERTAIN HOME-BASED ACUTE CARE SERVICES
- HOSPITALS ARE PILOTING HOME TREATMENT MODELS TO REDUCE INPATIENT BURDEN
- ADVANCED MEDICAL DEVICE INTEGRATION IS SUPPORTING HIGH-QUALITY HOME CARE DELIVERY
MARKET DYNAMICS
- KEY DRIVERS
- DIGITAL HEALTHCARE ACT AND TELEMEDICINE REIMBURSEMENT POLICIES ARE DRIVING MARKET GROWTH
- INCREASING DEMAND FOR COST-EFFICIENT CARE DELIVERY IS PROMOTING HOME-BASED MODELS
- AGING POPULATION AND HIGH INCIDENCE OF CHRONIC DISEASES ARE SUPPORTING DEMAND
- TECHNOLOGICAL ADVANCEMENTS IN MEDICAL DEVICES AND REMOTE MONITORING ENABLE EXPANSION
- KEY RESTRAINTS
- STRICT REGULATORY REQUIREMENTS SLOW DOWN IMPLEMENTATION OF NEW CARE MODELS
- LIMITED AWARENESS AND ACCEPTANCE OF HOME-BASED ACUTE CARE AMONG PATIENTS
- WORKFORCE SHORTAGES IN HOME HEALTHCARE SERVICES IMPACT SERVICE AVAILABILITY
- COMPLEX REIMBURSEMENT STRUCTURES CREATE BARRIERS FOR PROVIDERS
- KEY DRIVERS
STRATEGIC MARKET ANALYTICS
- GROWTH METRICS
- TAM, SAM & SOM OPPORTUNITY ANALYSIS
- EMERGING MARKET TRENDS & PARADIGM SHIFTS
- INCREASING ADOPTION OF TELEMEDICINE PLATFORMS IS SUPPORTING REMOTE ACUTE CARE
- PILOT PROGRAMS FOR HOSPITAL-AT-HOME MODELS ARE GAINING TRACTION
- INTEGRATION OF DIGITAL HEALTH APPLICATIONS INTO CARE DELIVERY IS EXPANDING
- FOCUS ON PATIENT-CENTRIC CARE IS DRIVING HOME-BASED TREATMENT INITIATIVES
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- PESTLE ANALYSIS
- POLITICAL
- ECONOMIC
- SOCIAL LANDSCAPE
- TECHNOLOGY
- LEGAL
- ENVIRONMENTAL
- GROWTH OPPORTUNITY MAPPING & HEATMAP
- GROWTH PROSPECT MAPPING FOR GERMANY
- MARKET MATURITY & LIFECYCLE ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- GROWTH METRICS
ACUTE CARE AT HOME VALUE CHAIN & DECISION FRAMEWORK
- VALUE CHAIN ANALYSIS
- MEDICAL DEVICE SUPPLIERS
- TECHNOLOGY PROVIDERS
- HEALTHCARE PROVIDERS
- HOME CARE SERVICES
- PAYERS INSURERS
- PATIENT MONITORING
- KEY BUYING CRITERIA
- CLINICAL EFFECTIVENESS
- COST EFFICIENCY
- TECHNOLOGY INTEGRATION
- PATIENT SAFETY
- PRICING MODELS, REIMBURSEMENT STRUCTURES & CARE DELIVERY OPTIMIZATION STRATEGIES
- REGULATORY & POLICY LANDSCAPE ANALYSIS
- VALUE CHAIN ANALYSIS
ACUTE CARE AT HOME MARKET BY SERVICE TYPE
- PHYSICIAN CARE SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SKILLED NURSING SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- DIAGNOSTIC & MONITORING SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- THERAPY SERVICES (PHYSICAL / OCCUPATIONAL / RESPIRATORY)
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- MEDICATION ADMINISTRATION SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER ACUTE CARE SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PHYSICIAN CARE SERVICES
ACUTE CARE AT HOME MARKET BY COMPONENT
- REMOTE PATIENT MONITORING DEVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- TELEHEALTH & VIRTUAL CARE PLATFORMS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- CLINICAL COMMAND CENTER SOFTWARE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- THERAPEUTIC EQUIPMENT
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER COMPONENTS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- REMOTE PATIENT MONITORING DEVICES
ACUTE CARE AT HOME MARKET BY DISEASE INDICATION
- RESPIRATORY DISEASES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- CARDIOVASCULAR DISEASES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- INFECTIOUS DISEASES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- RENAL DISORDERS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- POST-SURGICAL CARE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER ACUTE CONDITIONS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- RESPIRATORY DISEASES
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPETITOR POSITIONING & DIFFERENTIATION MAP
- COMPANY PROFILES
- CARESHIP
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- VEYO CARE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- HOME THERAPIE MANAGEMENT GMBH
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- SMART CARE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- ACTIMI GMBH
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- CASPAR HEALTH
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- NUI CARE GMBH
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- FRESENIUS KABI
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- CARESHIP
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – ACUTE CARE AT HOME MARKET
TABLE 2: PRICING MODELS, REIMBURSEMENT STRUCTURES & CARE DELIVERY OPTIMIZATION STRATEGIES
TABLE 3: REGULATORY & POLICY LANDSCAPE ANALYSIS
TABLE 4: MARKET BY SERVICE TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 5: MARKET BY SERVICE TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 6: MARKET BY COMPONENT, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 7: MARKET BY COMPONENT, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 8: MARKET BY DISEASE INDICATION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 9: MARKET BY DISEASE INDICATION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 10: KEY PLAYERS OPERATING IN THE GERMAN MARKET
TABLE 11: LIST OF MERGERS & ACQUISITIONS
TABLE 12: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 13: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 14: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR GERMANY
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY SERVICE TYPE, IN 2025
FIGURE 11: PHYSICIAN CARE SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: SKILLED NURSING SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: DIAGNOSTIC & MONITORING SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 14: THERAPY SERVICES (PHYSICAL / OCCUPATIONAL / RESPIRATORY) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: MEDICATION ADMINISTRATION SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: OTHER ACUTE CARE SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: SEGMENT GROWTH POTENTIAL, BY COMPONENT, IN 2025
FIGURE 18: REMOTE PATIENT MONITORING DEVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: TELEHEALTH & VIRTUAL CARE PLATFORMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: CLINICAL COMMAND CENTER SOFTWARE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: THERAPEUTIC EQUIPMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: OTHER COMPONENTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: SEGMENT GROWTH POTENTIAL, BY DISEASE INDICATION, IN 2025
FIGURE 24: RESPIRATORY DISEASES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: CARDIOVASCULAR DISEASES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: INFECTIOUS DISEASES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: RENAL DISORDERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: POST-SURGICAL CARE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 29: OTHER ACUTE CONDITIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
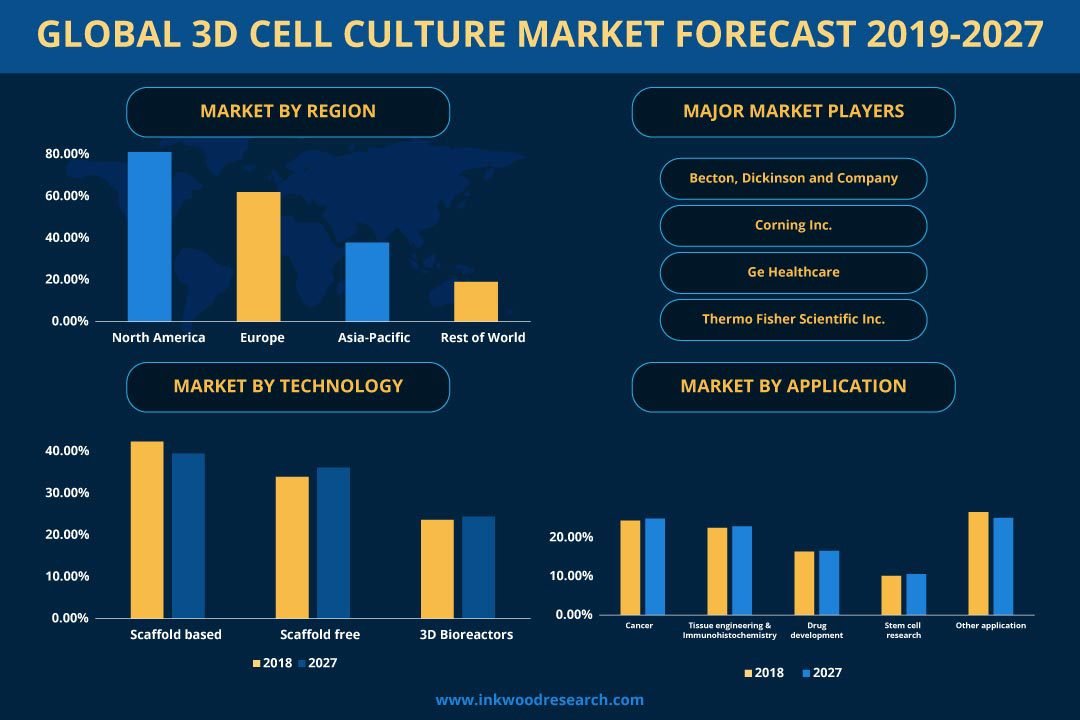
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
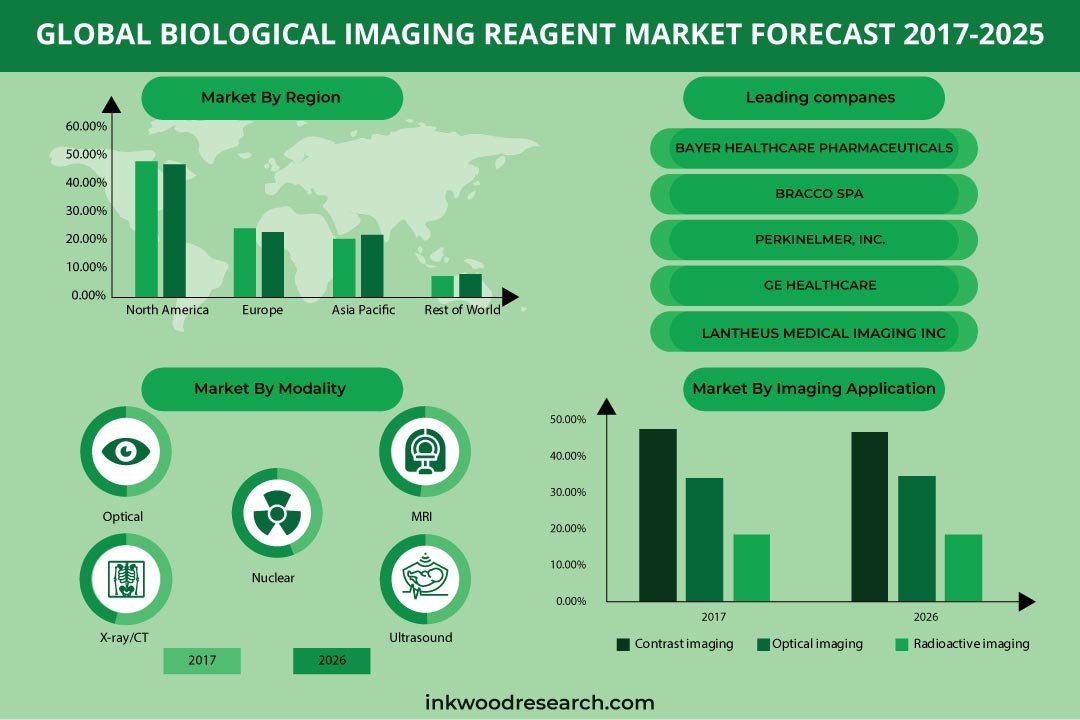
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034