United Kingdom AI-Driven Cloud Migration Services Market by Service Type (Professional Services, Managed Services), Market by Deployment Type (Public Cloud, Private Cloud, Hybrid Cloud), Market by Enterprise Size (Large Enterprises, Small & Medium Enterprises (SMEs)), and Market by Industry Vertical (BFSI, IT & Telecom, Healthcare, Retail & E-Commerce, Manufacturing, Government & Public Sector, Media & Entertainment, Other Industry Verticals), by Geography
UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET OVERVIEW
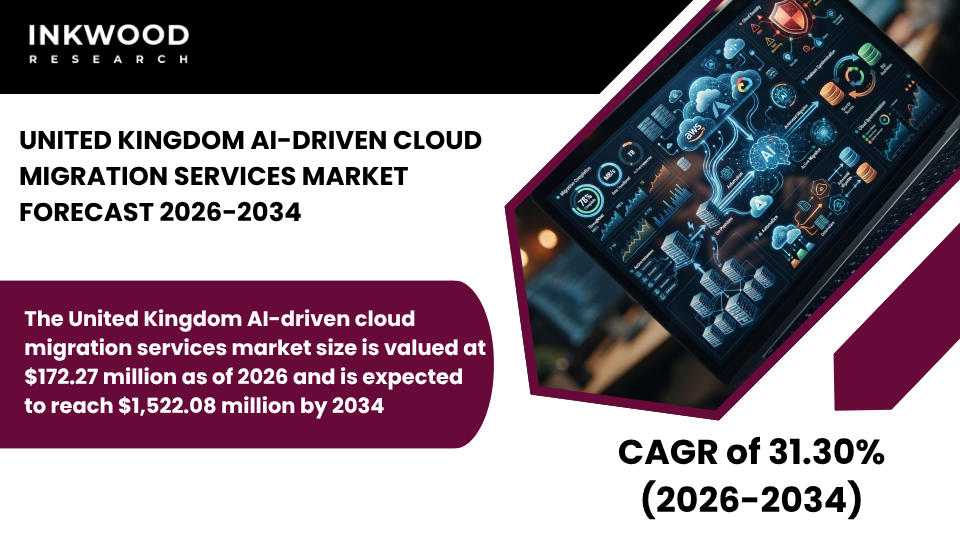
The United Kingdom AI-driven cloud migration services market size is valued at $172.27 million as of 2026 and is expected to reach $1,522.08 million by 2034, progressing with a CAGR of 31.30% during the forecast years, 2026-2034.
MARKET INSIGHTS
The United Kingdom represents one of Europe’s most dynamic markets for AI-driven cloud migration services. Enterprises across the financial, healthcare, and public sectors are accelerating their shift away from legacy infrastructure. This transition is driven by the need to improve operational resilience, reduce costs, and meet the growing demands of a digitally connected economy.
Furthermore, the UK’s well-established technology ecosystem and mature enterprise IT landscape make it fertile ground for AI-powered migration adoption. The country’s strong concentration of global financial institutions, multinational corporations, and fast-growing fintech firms continues to generate consistent demand for intelligent, automated cloud migration solutions.
Government-led digital transformation initiatives are a significant growth driver in this market. The UK Government’s Cloud First policy, published by the Government Digital Service (GDS) under the Cabinet Office, mandates that public sector bodies evaluate cloud solutions before any other IT option. This policy has directly accelerated cloud migration projects across NHS trusts, local authorities, and central government departments.
Additionally, the National Cyber Security Centre (NCSC) provides guidance on secure cloud adoption, shaping how public sector entities approach AI-driven migration. The Financial Conduct Authority (FCA) also enforces operational resilience standards for financial services firms, compelling banks and insurers to modernize their IT environments with compliant, cloud-native architectures.
Moreover, the UK GDPR, enforced by the Information Commissioner’s Office (ICO), introduces strict data localization and governance requirements that drive demand for AI migration tools capable of automating compliance checks throughout the migration process.
Post-Brexit data sovereignty considerations have added a new layer of complexity to cloud migration strategies in the UK. Organizations handling cross-border data flows between the UK and the European Union must navigate evolving adequacy arrangements, which increase demand for migration solutions with built-in data governance capabilities.
Additionally, the rapid growth of the UK’s fintech sector, recognized as one of the largest globally by the UK Finance industry body, is fueling the need for scalable, cloud-native infrastructure. SMEs, in particular, are emerging as a high-growth opportunity segment, as AI migration tools lower the technical barriers and cost thresholds traditionally associated with enterprise-grade cloud transitions.
A rising focus on green cloud migration, aligned with the UK’s legally binding net-zero targets under the Climate Change Act 2008, is further encouraging enterprises to migrate to energy-efficient cloud environments. These factors, in turn, are set to bolster the AI-driven cloud migration services market growth in the United Kingdom during the forecast period.
To Know More About This Report, Request a Free Sample Copy
SEGMENTATION ANALYSIS
The United Kingdom AI-driven cloud migration services market is segmented by service type, deployment type, enterprise size, and industry vertical. The service type segment is further categorized into professional services and managed services. Managed services are further divided into ongoing optimization and monitoring and management.
The managed services segment is gaining considerable traction within the UK AI-driven cloud migration services market. As organizations complete initial migration phases, they increasingly require continuous oversight to keep cloud environments secure, cost-efficient, and performant.
The ongoing optimization sub-segment, in particular, is seeing strong uptake. Enterprises are leveraging AI-powered tools to continuously analyze workload performance, rightsize cloud resources, and identify cost-saving opportunities across multi-cloud environments.
Furthermore, the monitoring and management sub-segment is expanding rapidly, driven by the growing complexity of hybrid cloud deployments. Organizations need real-time visibility into their cloud infrastructure to detect anomalies, maintain uptime, and ensure regulatory compliance, especially in sensitive sectors like BFSI and healthcare.
Additionally, the shortage of specialized cloud talent in the UK is pushing enterprises to outsource ongoing cloud management to experienced service providers, further fueling the managed services segment. Vendors that offer AI-driven, fully managed post-migration solutions with built-in compliance monitoring are especially well-positioned to capture this growing demand.
COMPETITIVE INSIGHTS
Some of the top players operating in the United Kingdom AI-driven cloud migration services market include IBM Corporation, Accenture plc, Tata Consultancy Services (TCS), Infosys Limited, Cloud4C, SecureKloud Technologies, Bitwise Global, etc.
Accenture plc is a global professional services company with a significant operational presence in the United Kingdom. It delivers services across strategy, consulting, technology, and operations, with cloud transformation forming a core pillar of its portfolio. In the AI-driven cloud migration space, Accenture offers its myNav cloud navigation platform, which uses AI to assess enterprise IT landscapes and build data-driven migration business cases.
The company also operates dedicated Cloud Centers of Excellence across the UK, serving large enterprise clients in BFSI, public sector, and retail. Its strong partnerships with hyperscalers, including Microsoft Azure, AWS, and Google Cloud, combined with deep industry expertise in regulated sectors, make Accenture a strategically relevant and highly capable player in the United Kingdom market.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Service Type, Deployment Type, Enterprise Size, Industry Vertical |
| Country Analyzed | The United Kingdom |
| Companies Analyzed | IBM Corporation, Accenture plc, Tata Consultancy Services (TCS), Infosys Limited, Cloud4C, SecureKloud Technologies, Bitwise Global |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE, SHARE & ESTIMATES
- MARKET OVERVIEW
- SCOPE OF STUDY
- MAJOR MARKET FINDINGS
- THE UNITED KINGDOM MARKET IS DRIVEN BY ENTERPRISE CLOUD ADOPTION ACROSS FINANCIAL AND PUBLIC SECTOR ORGANIZATIONS
- AI-DRIVEN MIGRATION SERVICES ARE BEING UTILIZED TO IMPROVE DATA GOVERNANCE AND OPERATIONAL EFFICIENCY
- STRONG REGULATORY FRAMEWORKS ARE SHAPING MIGRATION STRATEGIES AND TECHNOLOGY IMPLEMENTATION
- INCREASING FOCUS ON DIGITAL TRANSFORMATION IN SMEs IS EXPANDING MARKET OPPORTUNITIES
MARKET DYNAMICS
- KEY DRIVERS
- GOVERNMENT-LED DIGITAL INITIATIVES ARE ACCELERATING CLOUD MIGRATION PROJECTS
- RISING DEMAND FOR DATA LOCALIZATION AND COMPLIANCE IS DRIVING AI-ENABLED MIGRATION SOLUTIONS
- GROWTH IN FINTECH AND DIGITAL SERVICES IS BOOSTING CLOUD INFRASTRUCTURE REQUIREMENTS
- INCREASING ADOPTION OF HYBRID CLOUD MODELS IS SUPPORTING MARKET EXPANSION
- KEY RESTRAINTS
- DATA SOVEREIGNTY REQUIREMENTS CREATE COMPLEXITIES IN CROSS-BORDER MIGRATION PROJECTS
- HIGH COST OF ADVANCED AI MIGRATION TOOLS LIMITS ADOPTION AMONG SMALL BUSINESSES
- LEGACY INFRASTRUCTURE IN PUBLIC SECTOR ORGANIZATIONS SLOWS MIGRATION PROCESSES
- LIMITED AVAILABILITY OF SPECIALIZED TALENT IMPACTS IMPLEMENTATION SPEED
- KEY DRIVERS
STRATEGIC MARKET ANALYTICS
- GROWTH METRICS
- TAM, SAM & SOM OPPORTUNITY ANALYSIS
- EMERGING MARKET TRENDS & PARADIGM SHIFTS
- GROWING USE OF AI FOR AUTOMATED COMPLIANCE CHECKS DURING MIGRATION IS EMERGING
- INCREASING FOCUS ON GREEN CLOUD MIGRATION STRATEGIES IS SHAPING ENTERPRISE DECISIONS
- EXPANSION OF CLOUD-FIRST POLICIES IN THE PUBLIC SECTOR IS DRIVING DEMAND
- RISE OF MANAGED MIGRATION SERVICES IS IMPROVING OPERATIONAL EFFICIENCY
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- PESTLE ANALYSIS
- POLITICAL
- ECONOMIC
- SOCIAL LANDSCAPE
- TECHNOLOGY
- LEGAL
- ENVIRONMENTAL
- GROWTH OPPORTUNITY MAPPING & HEATMAP
- GROWTH PROSPECT MAPPING FOR THE UNITED KINGDOM
- MARKET MATURITY & LIFECYCLE ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- GROWTH METRICS
AI-DRIVEN CLOUD MIGRATION SERVICES VALUE CHAIN & DECISION FRAMEWORK
- VALUE CHAIN ANALYSIS
- DATA ASSESSMENT
- WORKLOAD DISCOVERY
- MIGRATION PLANNING
- TOOL DEVELOPMENT
- EXECUTION SERVICES
- POST MIGRATION
- KEY BUYING CRITERIA
- DATA SECURITY
- COST EFFICIENCY
- SCALABILITY FLEXIBILITY
- VENDOR EXPERTISE
- PRICING MODELS, FEE STRUCTURES & CLOUD MIGRATION COST OPTIMIZATION STRATEGIES
- REGULATORY & POLICY LANDSCAPE ANALYSIS
- VALUE CHAIN ANALYSIS
AI-DRIVEN CLOUD MIGRATION SERVICES MARKET BY SERVICE TYPE
- PROFESSIONAL SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ASSESSMENT & PLANNING
- MIGRATION & IMPLEMENTATION
- POST-MIGRATION SUPPORT
- MANAGED SERVICES
- MANAGED SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ONGOING OPTIMIZATION
- MONITORING & MANAGEMENT
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PROFESSIONAL SERVICES
AI-DRIVEN CLOUD MIGRATION SERVICES MARKET BY DEPLOYMENT TYPE
- PUBLIC CLOUD
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PRIVATE CLOUD
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- HYBRID CLOUD
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PUBLIC CLOUD
AI-DRIVEN CLOUD MIGRATION SERVICES MARKET BY ENTERPRISE SIZE
- LARGE ENTERPRISES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SMALL & MEDIUM ENTERPRISES (SMES)
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- LARGE ENTERPRISES
AI-DRIVEN CLOUD MIGRATION SERVICES MARKET BY INDUSTRY VERTICAL
- BFSI
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- IT & TELECOM
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- HEALTHCARE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- RETAIL & E-COMMERCE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- MANUFACTURING
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- GOVERNMENT & PUBLIC SECTOR
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- MEDIA & ENTERTAINMENT
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER INDUSTRY VERTICALS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- BFSI
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPETITOR POSITIONING & DIFFERENTIATION MAP
- COMPANY PROFILES
- IBM CORPORATION
- COMPANY OVERVIEW
- PRODXUCT LIST
- STRENGTHS & CHALLENGES
- ACCENTURE PLC
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- TATA CONSULTANCY SERVICES (TCS)
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- INFOSYS LIMITED
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- CLOUD4C
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- SECUREKLOUD TECHNOLOGIES
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- BITWISE GLOBAL
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- IBM CORPORATION
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – AI-DRIVEN CLOUD MIGRATION SERVICES MARKET
TABLE 2: PRICING MODELS, FEE STRUCTURES & CLOUD MIGRATION COST OPTIMIZATION STRATEGIES
TABLE 3: REGULATORY & POLICY LANDSCAPE ANALYSIS
TABLE 4: MARKET BY SERVICE TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 5: MARKET BY SERVICE TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 6: MARKET BY PROFESSIONAL SERVICES, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 7: MARKET BY PROFESSIONAL SERVICES, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 8: MARKET BY MANAGED SERVICES, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 9: MARKET BY MANAGED SERVICES, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 10: MARKET BY DEPLOYMENT TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 11: MARKET BY DEPLOYMENT TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 12: MARKET BY ENTERPRISE SIZE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 13: MARKET BY ENTERPRISE SIZE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 14: MARKET BY INDUSTRY VERTICAL, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 15: MARKET BY INDUSTRY VERTICAL, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 16: KEY PLAYERS OPERATING IN THE UNITED KINGDOM MARKET
TABLE 17: LIST OF MERGERS & ACQUISITIONS
TABLE 18: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 19: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 20: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR THE UNITED KINGDOM
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY SERVICE TYPE, IN 2025
FIGURE 11: PROFESSIONAL SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: SEGMENT GROWTH POTENTIAL, BY PROFESSIONAL SERVICES, IN 2025
FIGURE 13: ASSESSMENT & PLANNING MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 14: MIGRATION & IMPLEMENTATION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: POST-MIGRATION SUPPORT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: MANAGED SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: SEGMENT GROWTH POTENTIAL, BY MANAGED SERVICES, IN 2025
FIGURE 18: ONGOING OPTIMIZATION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: MONITORING & MANAGEMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: SEGMENT GROWTH POTENTIAL, BY DEPLOYMENT TYPE, IN 2025
FIGURE 21: PUBLIC CLOUD MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: PRIVATE CLOUD MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: HYBRID CLOUD MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: SEGMENT GROWTH POTENTIAL, BY ENTERPRISE SIZE, IN 2025
FIGURE 25: LARGE ENTERPRISES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: SMALL & MEDIUM ENTERPRISES (SMES) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: SEGMENT GROWTH POTENTIAL, BY INDUSTRY VERTICAL, IN 2025
FIGURE 28: BFSI MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 29: IT & TELECOM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: HEALTHCARE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: RETAIL & E-COMMERCE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 32: MANUFACTURING MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 33: GOVERNMENT & PUBLIC SECTOR MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 34: MEDIA & ENTERTAINMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 35: OTHER INDUSTRY VERTICALS MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
LATIN AMERICA FACIAL RECOGNITION MARKET FORECAST 2019-2028
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
JAPAN AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
INDIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
CHINA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034