Australia AI-Driven Cloud Migration Services Market by Service Type (Professional Services, Managed Services), Market by Deployment Type (Public Cloud, Private Cloud, Hybrid Cloud), Market by Enterprise Size (Large Enterprises, Small & Medium Enterprises (SMEs)), and Market by Industry Vertical (BFSI, IT & Telecom, Healthcare, Retail & E-Commerce, Manufacturing, Government & Public Sector, Media & Entertainment, Other Industry Verticals), by Geography
AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET OVERVIEW
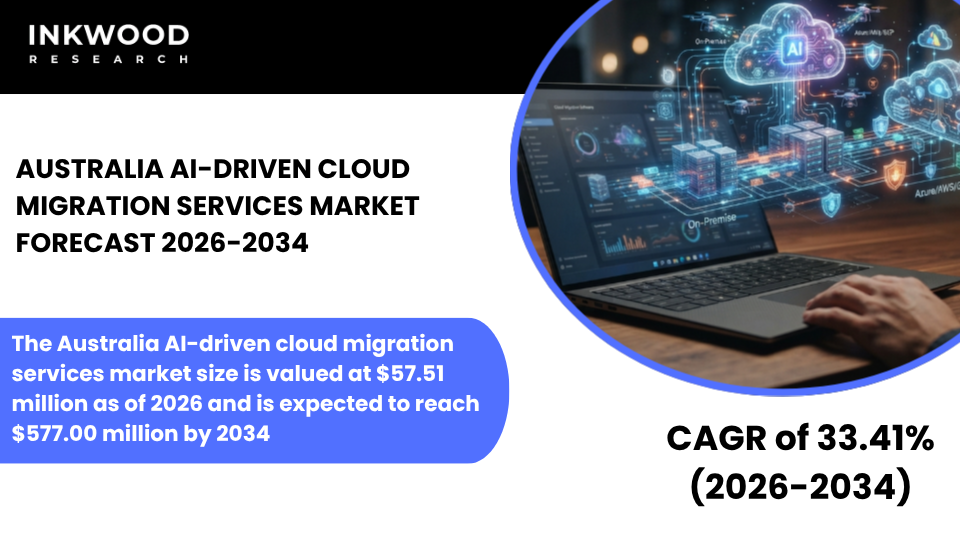
The Australia AI-driven cloud migration services market size is valued at $57.51 million as of 2026 and is expected to reach $577.00 million by 2034, progressing with a CAGR of 33.41% during the forecast years, 2026-2034.
MARKET INSIGHTS
Australia is emerging as a significant market for AI-driven cloud migration services, supported by strong enterprise demand for digital transformation and a well-developed technology infrastructure. Enterprises across financial services, government, healthcare, and retail are actively retiring legacy systems in favor of cloud-native architectures to improve scalability, reduce operational costs, and enable data-driven decision-making.
Additionally, the strong presence of all three major hyperscalers, namely Amazon Web Services, Microsoft Azure, and Google Cloud, each operating dedicated local data center regions within Australia, has substantially addressed data sovereignty concerns that previously slowed enterprise cloud adoption. This in-country infrastructure availability gives Australian organizations the confidence to migrate sensitive workloads to public cloud environments while remaining compliant with domestic data residency requirements.
Government policy is a central driver of cloud adoption in Australia. The Digital Transformation Agency (DTA) leads the government’s cloud strategy, actively encouraging federal and state agencies to adopt cloud-first approaches for new and existing IT systems. The Australian Cyber Security Centre (ACSC), operating under the Australian Signals Directorate, publishes cloud security guidance and the Information Security Registered Assessors Program (IRAP) framework, which governs how government entities assess and select cloud service providers.
These frameworks directly shape procurement decisions and migration planning across the public sector. Furthermore, the Australian Prudential Regulation Authority (APRA) has issued Prudential Practice Guide CPG 235, which sets out expectations for financial institutions managing data risk in cloud environments. This guidance has become a key reference point for banks, insurers, and superannuation funds undertaking AI-driven cloud migrations, compelling them to adopt structured, compliance-embedded migration methodologies.
Australia’s evolving privacy landscape is adding further regulatory complexity to cloud migration projects. The Privacy Act 1988, currently under review following recommendations from the Attorney-General’s Department, is expected to introduce stronger data protection obligations aligned with international standards.
These anticipated changes are encouraging enterprises to proactively restructure their data governance frameworks during migration, driving demand for AI tools with built-in compliance automation. Moreover, Australia’s unique geographic dispersion presents infrastructure deployment challenges, particularly for organizations operating across regional and remote areas with limited connectivity.
This challenge is accelerating interest in hybrid and edge-integrated cloud architectures. For vendors and investors, the government and public sector, BFSI, and healthcare verticals represent the most immediate high-value opportunities, while the growing SME base offers significant longer-term market expansion potential. These factors, in turn, are set to bolster the AI-driven cloud migration services market growth in Australia during the forecast period.
To Know More About This Report, Request a Free Sample Copy
SEGMENTATION ANALYSIS
The Australia AI-driven cloud migration services market is segmented by service type, deployment type, enterprise size, and industry vertical. The deployment type segment is further categorized into public cloud, private cloud, and hybrid cloud.
The public cloud segment holds a prominent position within the Australia AI-driven cloud migration services market. The availability of locally domiciled hyperscaler regions has resolved the data sovereignty barrier that previously restricted public cloud adoption for regulated industries.
Government agencies, financial institutions, and healthcare organizations can now migrate to public cloud platforms while keeping data within Australian borders, meeting both APRA and Privacy Act requirements. Additionally, the DTA’s cloud-first mandate has created a structured pipeline of public sector workloads being transitioned to pre-approved public cloud platforms, generating consistent and foreseeable demand.
The scalability and cost-efficiency advantages of public cloud are particularly compelling for Australian enterprises managing fluctuating workloads across diverse geographic regions. Furthermore, the growing adoption of Cloud FinOps practices is enabling organizations to optimize cloud spending post-migration, making the total cost of ownership case for public cloud increasingly persuasive.
Vendors offering AI-driven migration tools with IRAP-aligned security assessments and automated compliance reporting are particularly well-placed to serve the high-value government and regulated enterprise segments within Australia’s public cloud migration market.
COMPETITIVE INSIGHTS
Some of the top players operating in the Australia AI-driven cloud migration services market include IBM Corporation, Accenture plc, Tata Consultancy Services (TCS), Infosys Limited, Impetus Technologies, etc.
Infosys Limited is a global IT services and consulting company headquartered in Bengaluru, India, with a well-established operational presence across Australia. It delivers services spanning cloud transformation, AI, digital engineering, and managed operations to enterprise and government clients. In the AI-driven cloud migration space, Infosys offers its Infosys Cobalt cloud platform, a suite of over 35,000 cloud assets, solutions, and platforms designed to accelerate enterprise cloud migrations across hybrid and multi-cloud environments.
The company’s cloud services cover the full migration lifecycle, from workload assessment and migration planning through to post-migration optimization and ongoing managed services. Infosys has a significant client base across Australia’s financial services, utilities, and government sectors, and its strong hyperscaler partnerships with AWS, Microsoft Azure, and Google Cloud reinforce its ability to deliver compliant, scalable migration outcomes for Australian enterprises.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Service Type, Deployment Type, Enterprise Size, Industry Vertical |
| Country Analyzed | Australia |
| Companies Analyzed | IBM Corporation, Accenture plc, Tata Consultancy Services (TCS), Infosys Limited, Cloud4C, Celebal Technologies, SecureKloud Technologies, Impetus Technologies |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE, SHARE & ESTIMATES
- MARKET OVERVIEW
- SCOPE OF STUDY
- MAJOR MARKET FINDINGS
- AUSTRALIA IS EXPERIENCING STRONG GROWTH IN AI-DRIVEN CLOUD MIGRATION SERVICES SUPPORTED BY ENTERPRISE DIGITAL TRANSFORMATION
- CLOUD-FIRST STRATEGIES ARE WIDELY ADOPTED ACROSS PUBLIC AND PRIVATE SECTORS
- SMES ARE INCREASINGLY ADOPTING CLOUD MIGRATION TO IMPROVE SCALABILITY
- FOCUS ON DATA SECURITY AND COMPLIANCE IS SHAPING MIGRATION STRATEGIES
MARKET DYNAMICS
- KEY DRIVERS
- GOVERNMENT CLOUD ADOPTION POLICIES ARE DRIVING MARKET EXPANSION
- RISING DEMAND FOR DIGITAL SERVICES IS BOOSTING CLOUD INFRASTRUCTURE NEEDS
- INCREASING ADOPTION OF AI TECHNOLOGIES IS ENHANCING MIGRATION EFFICIENCY
- STRONG PRESENCE OF GLOBAL CLOUD PROVIDERS IS SUPPORTING MARKET GROWTH
- KEY RESTRAINTS
- DATA SOVEREIGNTY REQUIREMENTS CREATE CHALLENGES IN CLOUD MIGRATION
- HIGH COST OF ADVANCED MIGRATION SOLUTIONS LIMITS SME ADOPTION
- GEOGRAPHICAL DISPERSION IMPACTS INFRASTRUCTURE DEPLOYMENT
- SKILL SHORTAGES IN CLOUD TECHNOLOGIES AFFECT IMPLEMENTATION
- KEY DRIVERS
STRATEGIC MARKET ANALYTICS
- GROWTH METRICS
- TAM, SAM & SOM OPPORTUNITY ANALYSIS
- EMERGING MARKET TRENDS & PARADIGM SHIFTS
- GROWTH OF HYBRID CLOUD DEPLOYMENTS IS GAINING MOMENTUM
- INCREASING USE OF AI FOR AUTOMATED MIGRATION PLANNING IS EMERGING
- EXPANSION OF MANAGED SERVICES IS IMPROVING OPERATIONAL EFFICIENCY
- FOCUS ON SUSTAINABLE CLOUD MIGRATION STRATEGIES IS RISING
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- PESTLE ANALYSIS
- POLITICAL
- ECONOMIC
- SOCIAL LANDSCAPE
- TECHNOLOGY
- LEGAL
- ENVIRONMENTAL
- GROWTH OPPORTUNITY MAPPING & HEATMAP
- GROWTH PROSPECT MAPPING FOR THE AUSTRALIA
- MARKET MATURITY & LIFECYCLE ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- GROWTH METRICS
AI-DRIVEN CLOUD MIGRATION SERVICES VALUE CHAIN & DECISION FRAMEWORK
- VALUE CHAIN ANALYSIS
- DATA ASSESSMENT
- WORKLOAD DISCOVERY
- MIGRATION PLANNING
- TOOL DEVELOPMENT
- EXECUTION SERVICES
- POST MIGRATION
- KEY BUYING CRITERIA
- DATA SECURITY
- COST EFFICIENCY
- SCALABILITY FLEXIBILITY
- VENDOR EXPERTISE
- PRICING MODELS, FEE STRUCTURES & CLOUD MIGRATION COST OPTIMIZATION STRATEGIES
- REGULATORY & POLICY LANDSCAPE ANALYSIS
- VALUE CHAIN ANALYSIS
AI-DRIVEN CLOUD MIGRATION SERVICES MARKET BY SERVICE TYPE
- PROFESSIONAL SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ASSESSMENT & PLANNING
- MIGRATION & IMPLEMENTATION
- POST-MIGRATION SUPPORT
- MANAGED SERVICES
- MANAGED SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ONGOING OPTIMIZATION
- MONITORING & MANAGEMENT
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PROFESSIONAL SERVICES
AI-DRIVEN CLOUD MIGRATION SERVICES MARKET BY DEPLOYMENT TYPE
- PUBLIC CLOUD
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PRIVATE CLOUD
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- HYBRID CLOUD
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PUBLIC CLOUD
AI-DRIVEN CLOUD MIGRATION SERVICES MARKET BY ENTERPRISE SIZE
- LARGE ENTERPRISES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SMALL & MEDIUM ENTERPRISES (SMES)
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- LARGE ENTERPRISES
AI-DRIVEN CLOUD MIGRATION SERVICES MARKET BY INDUSTRY VERTICAL
- BFSI
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- IT & TELECOM
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- HEALTHCARE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- RETAIL & E-COMMERCE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- MANUFACTURING
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- GOVERNMENT & PUBLIC SECTOR
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- MEDIA & ENTERTAINMENT
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER INDUSTRY VERTICALS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- BFSI
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPETITOR POSITIONING & DIFFERENTIATION MAP
- COMPANY PROFILES
- IBM CORPORATION
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- ACCENTURE PLC
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- TATA CONSULTANCY SERVICES (TCS)
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- INFOSYS LIMITED
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- CLOUD4C
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- CELEBAL TECHNOLOGIES
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- SECUREKLOUD TECHNOLOGIES
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- IMPETUS TECHNOLOGIES
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- IBM CORPORATION
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – AI-DRIVEN CLOUD MIGRATION SERVICES MARKET
TABLE 2: PRICING MODELS, FEE STRUCTURES & CLOUD MIGRATION COST OPTIMIZATION STRATEGIES
TABLE 3: REGULATORY & POLICY LANDSCAPE ANALYSIS
TABLE 4: MARKET BY SERVICE TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 5: MARKET BY SERVICE TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 6: MARKET BY PROFESSIONAL SERVICES, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 7: MARKET BY PROFESSIONAL SERVICES, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 8: MARKET BY MANAGED SERVICES, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 9: MARKET BY MANAGED SERVICES, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 10: MARKET BY DEPLOYMENT TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 11: MARKET BY DEPLOYMENT TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 12: MARKET BY ENTERPRISE SIZE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 13: MARKET BY ENTERPRISE SIZE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 14: MARKET BY INDUSTRY VERTICAL, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 15: MARKET BY INDUSTRY VERTICAL, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 16: KEY PLAYERS OPERATING IN THE AUSTRALIAN MARKET
TABLE 17: LIST OF MERGERS & ACQUISITIONS
TABLE 18: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 19: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 20: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR AUSTRALIA
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY SERVICE TYPE, IN 2025
FIGURE 11: PROFESSIONAL SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: SEGMENT GROWTH POTENTIAL, BY PROFESSIONAL SERVICES, IN 2025
FIGURE 13: ASSESSMENT & PLANNING MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 14: MIGRATION & IMPLEMENTATION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: POST-MIGRATION SUPPORT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: MANAGED SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: SEGMENT GROWTH POTENTIAL, BY MANAGED SERVICES, IN 2025
FIGURE 18: ONGOING OPTIMIZATION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: MONITORING & MANAGEMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: SEGMENT GROWTH POTENTIAL, BY DEPLOYMENT TYPE, IN 2025
FIGURE 21: PUBLIC CLOUD MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: PRIVATE CLOUD MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: HYBRID CLOUD MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: SEGMENT GROWTH POTENTIAL, BY ENTERPRISE SIZE, IN 2025
FIGURE 25: LARGE ENTERPRISES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: SMALL & MEDIUM ENTERPRISES (SMES) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: SEGMENT GROWTH POTENTIAL, BY INDUSTRY VERTICAL, IN 2025
FIGURE 28: BFSI MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 29: IT & TELECOM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: HEALTHCARE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: RETAIL & E-COMMERCE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 32: MANUFACTURING MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 33: GOVERNMENT & PUBLIC SECTOR MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 34: MEDIA & ENTERTAINMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 35: OTHER INDUSTRY VERTICALS MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
LATIN AMERICA FACIAL RECOGNITION MARKET FORECAST 2019-2028
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
JAPAN AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
INDIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
CHINA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034