
THAILAND CONTRAST ULTRASOUND MARKET FORECAST 2026-2034
SCOPE OF THE REPORT
Thailand Contrast Ultrasound Market by Product (Equipment, Contrast Agents) Market by Type (Non-Targeted, Targeted) Market by Application (Diagnostic Applications, Therapeutic Applications) Market by End Use (Hospitals, Clinics, Ambulatory Diagnostic Centers), by Geography
REPORTS » HEALTHCARE » MEDICAL DEVICES » THAILAND CONTRAST ULTRASOUND MARKET FORECAST 2026-2034
THAILAND CONTRAST ULTRASOUND MARKET OVERVIEW
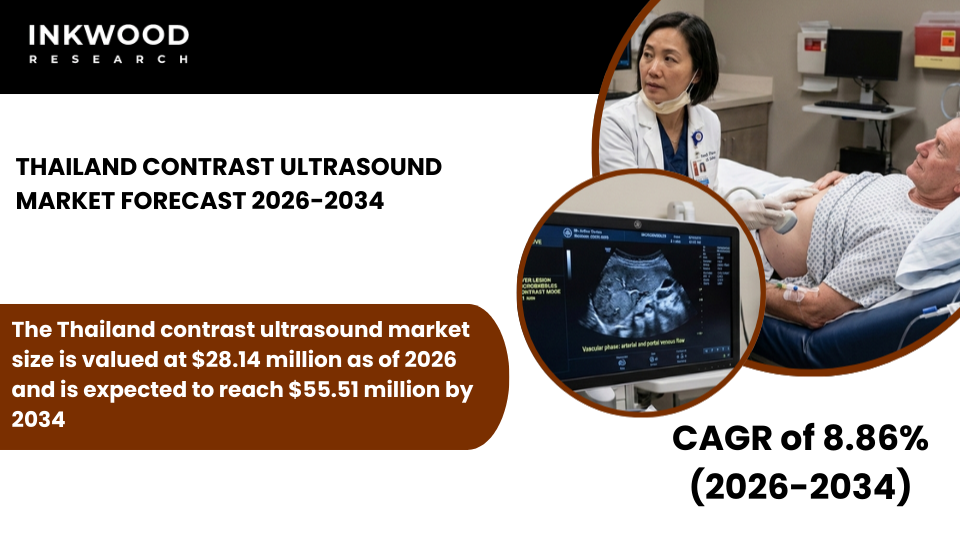
The Thailand contrast ultrasound market size is valued at $28.14 million as of 2026 and is expected to reach $55.51 million by 2034, progressing with a CAGR of 8.86% during the forecast years, 2026-2034.
Thailand’s contrast ultrasound market is experiencing steady growth driven by medical tourism, well-developed private hospital networks, and the increasing prevalence of chronic diseases requiring advanced diagnostic capabilities. The country benefits from a dual-tier healthcare system combining universal coverage for Thai citizens through the National Health Security Office with premium private healthcare facilities that attract both domestic and international patients seeking high-quality diagnostic services.
Rising prevalence of chronic diseases, particularly liver cancer and cardiovascular conditions, is creating sustained demand for enhanced ultrasound procedures that enable early detection and accurate characterization of disease. According to the National Cancer Institute of Thailand, liver cancer remains the most common malignancy among males and is projected to account for approximately 24,616 new cases in 2025, making hepatic imaging a critical clinical priority.
To Know More About This Report, Request a Free Sample Copy
Government support for healthcare modernization through infrastructure development programs and equipment procurement initiatives is facilitating investments in advanced ultrasound systems across public hospitals and regional medical centers. Moreover, growing awareness of non-invasive imaging options among clinicians is encouraging the adoption of contrast enhanced ultrasound as an alternative to CT and MRI for specific diagnostic applications where radiation-free imaging provides clinical advantages.
The expansion of private healthcare chains such as Bangkok Hospital Group, Bumrungrad International Hospital, and Samitivej Hospitals is driving the procurement of high-end ultrasound systems equipped with contrast-enhanced capabilities, artificial intelligence integration, and telemedicine connectivity that support both diagnostic applications and therapeutic applications. Medical tourism represents a significant market driver, as international patients visiting Thailand for healthcare services expect access to advanced diagnostic technologies comparable to those available in developed Western markets.
Thailand’s reputation as a regional medical hub attracts patients from neighboring countries, including Myanmar, Cambodia, Laos, and Vietnam, creating additional demand for sophisticated imaging services. Furthermore, increasing collaboration with international medical device companies through technology transfer agreements and local distribution partnerships is enhancing access to the latest ultrasound platforms and contrast agent formulations.
The country’s strategic geographic location and well-established healthcare infrastructure position it as an attractive market for manufacturers seeking to expand their presence across Southeast Asia. These factors, in turn, are set to boost the contrast ultrasound market growth in Thailand during the forecast period.
The Thailand contrast ultrasound market is segmented into product, type, application, and end use. The end use segment is further categorized into hospitals, clinics, and ambulatory diagnostic centers.
The clinics segment is experiencing notable growth within the Thailand contrast ultrasound market, driven by the proliferation of specialty imaging centers and outpatient diagnostic facilities across Bangkok and major provincial cities. This segment encompasses private diagnostic clinics, specialty cardiology clinics, and gastroenterology centers that offer targeted imaging services to patients seeking convenient access to advanced diagnostics without the need for hospital admission.
Clinics serve an important role in Thailand’s healthcare ecosystem by providing accessible and cost-effective diagnostic services to middle-income patients who prefer private healthcare but may find hospital-based procedures financially prohibitive. The segment benefits from Thailand’s liberal regulatory environment that permits private practice physicians to operate independent diagnostic facilities equipped with advanced ultrasound systems capable of performing contrast-enhanced studies.
Many clinics are affiliated with or operated by specialist physicians who recognize the clinical value of enhanced ultrasound for characterizing focal liver lesions in patients with chronic hepatitis B and C infections, which remain endemic in certain regions despite widespread vaccination programs. Additionally, cardiology clinics utilize contrast ultrasound to evaluate patients with suspected coronary artery disease, heart failure, or valvular abnormalities, providing rapid diagnostic information that informs treatment decisions and reduces the need for more expensive cardiac imaging modalities.
The clinics segment is witnessing investment in compact, user-friendly ultrasound systems with touchscreen interfaces and automated imaging protocols that enable efficient workflow management in busy outpatient settings. Moreover, partnerships between clinics and international contrast agent manufacturers ensure a reliable supply of microbubble-based products while providing technical support and clinical training that enhances diagnostic quality.
The growing trend toward preventive healthcare and early disease detection is driving patient demand for screening programs that include contrast ultrasound examinations, particularly among affluent urban populations concerned about cancer and cardiovascular risk. Furthermore, medical insurance coverage through private health insurance plans and corporate health benefit programs is improving patient affordability for contrast ultrasound procedures performed in clinic settings, making advanced diagnostics more accessible to employed individuals with employer-sponsored healthcare coverage.
The segment faces challenges related to competition from hospital-based imaging departments that may offer more comprehensive services and access to multidisciplinary care teams. However, clinics maintain competitive advantages through shorter wait times, flexible appointment scheduling, and personalized patient service that appeals to time-conscious professionals and international patients.
Some of the top players operating in the Thailand contrast ultrasound market include GE Healthcare, Siemens Healthineers AG, Koninklijke Philips NV, and Canon Medical Systems Corporation, among others.
Canon Medical Systems Corporation, headquartered in Tochigi, Japan, is a leading medical imaging equipment manufacturer with a strong regional presence across Southeast Asia, including Thailand. The company provides advanced ultrasound systems, CT scanners, and MRI equipment to hospitals, clinics, and ambulatory diagnostic centers through established distribution networks and service partnerships.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Product, Type, Application, End Use |
| Country Analyzed | Thailand |
| Companies Analyzed | GE HealthCare, Bracco Imaging SpA, Lantheus Holdings Inc, Siemens Healthineers AG, Koninklijke Philips NV, Bayer AG, Guerbet, Canon Medical Systems Corporation, Shenzhen Mindray Bio-Medical Electronics Co Ltd, Esaote SpA, FUJIFILM Holdings Corporation, Samsung Healthcare, Daiichi Sankyo Company Limited, Trivitron Healthcare Pvt Ltd, SuperSonic Imagine SA |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- MEDICAL TOURISM AND WELL-DEVELOPED PRIVATE HOSPITAL NETWORKS ARE SUPPORTING STEADY MARKET GROWTH
- CONTRAST ENHANCED ULTRASOUND IS INCREASINGLY USED IN HEPATIC AND CARDIAC DIAGNOSTICS
- PUBLIC HOSPITALS ARE GRADUALLY UPGRADING IMAGING INFRASTRUCTURE TO MEET RISING PATIENT DEMAND
- MARKET EXPANSION IS DRIVEN BY URBAN HEALTHCARE FACILITIES WITH LIMITED PENETRATION IN RURAL REGIONS
MARKET DYNAMICS
- KEY DRIVERS
- RISING PREVALENCE OF CHRONIC DISEASES IS INCREASING DEMAND FOR ADVANCED DIAGNOSTIC PROCEDURES
- GOVERNMENT SUPPORT FOR HEALTHCARE MODERNIZATION IS FACILITATING EQUIPMENT INVESTMENTS
- GROWING AWARENESS OF NON-INVASIVE IMAGING OPTIONS AMONG CLINICIANS IS BOOSTING ADOPTION
- EXPANSION OF PRIVATE HEALTHCARE CHAINS IS DRIVING PROCUREMENT OF HIGH-END ULTRASOUND SYSTEMS
- KEY RESTRAINTS
- LIMITED REIMBURSEMENT POLICIES FOR CONTRAST AGENTS MAY RESTRICT WIDESPREAD UTILIZATION
- DEPENDENCE ON IMPORTED IMAGING EQUIPMENT CAN LEAD TO COST PRESSURES
- SHORTAGE OF SPECIALIZED TRAINING PROGRAMS FOR ADVANCED ULTRASOUND APPLICATIONS MAY LIMIT MARKET DEPTH
- COMPETITION FROM ALTERNATIVE IMAGING MODALITIES IN COMPLEX CASES MAY AFFECT PROCEDURE SHARE
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- INCREASING COLLABORATION WITH INTERNATIONAL MEDICAL DEVICE COMPANIES IS ENHANCING TECHNOLOGY TRANSFER
- RISING FOCUS ON EARLY-STAGE LIVER CANCER DETECTION IS SUPPORTING CLINICAL DEMAND
- ADOPTION OF AI-ENABLED IMAGING SOFTWARE IS IMPROVING DIAGNOSTIC ACCURACY
- GROWING INVESTMENT IN REGIONAL HOSPITAL NETWORKS IS EXPANDING ACCESS TO ADVANCED ULTRASOUND
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR THAILAND
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SUPPLIERS
- CONTRAST AGENT MANUFACTURERS
- ULTRASOUND OEMS
- DISTRIBUTION PARTNERS
- HOSPITAL PROCUREMENT
- END-USER FACILITIES
- KEY BUYING CRITERIA
- IMAGE CLARITY
- SAFETY PROFILE
- REGULATORY APPROVAL
- COST EFFECTIVENESS
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
CONTRAST ULTRASOUND MARKET BY PRODUCT
- EQUIPMENT
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- CONTRAST AGENTS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- EQUIPMENT
CONTRAST ULTRASOUND MARKET BY TYPE
- NON-TARGETED
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- TARGETED
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- NON-TARGETED
CONTRAST ULTRASOUND MARKET BY APPLICATION
- DIAGNOSTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- THERAPEUTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DIAGNOSTIC APPLICATIONS
CONTRAST ULTRASOUND MARKET BY END USE
- HOSPITALS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- CLINICS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- AMBULATORY DIAGNOSTIC CENTERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- HOSPITALS
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- GE HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- BRACCO IMAGING SPA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- LANTHEUS HOLDINGS INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SIEMENS HEALTHINEERS AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- KONINKLIJKE PHILIPS NV
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- BAYER AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GUERBET
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- CANON MEDICAL SYSTEMS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ESAOTE SPA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- FUJIFILM HOLDINGS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SAMSUNG HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- DAIICHI SANKYO COMPANY LIMITED
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- TRIVITRON HEALTHCARE PVT LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SUPERSONIC IMAGINE SA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GE HEALTHCARE
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – CONTRAST ULTRASOUND
TABLE 2: CONTRAST ULTRASOUND MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY PRODUCT, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY PRODUCT, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: MARKET BY TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: MARKET BY TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: MARKET BY APPLICATION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: MARKET BY APPLICATION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: MARKET BY END USE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: MARKET BY END USE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: KEY PLAYERS OPERATING IN THE THAI MARKET
TABLE 12: LIST OF MERGERS & ACQUISITIONS
TABLE 13: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 14: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 15: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR THAILAND
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY PRODUCT, IN 2025
FIGURE 11: EQUIPMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: CONTRAST AGENTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY TYPE, IN 2025
FIGURE 14: NON-TARGETED MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: TARGETED MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: SEGMENT GROWTH POTENTIAL, BY APPLICATION, IN 2025
FIGURE 17: DIAGNOSTIC APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: THERAPEUTIC APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: SEGMENT GROWTH POTENTIAL, BY END USE, IN 2025
FIGURE 20: HOSPITALS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: CLINICS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: AMBULATORY DIAGNOSTIC CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
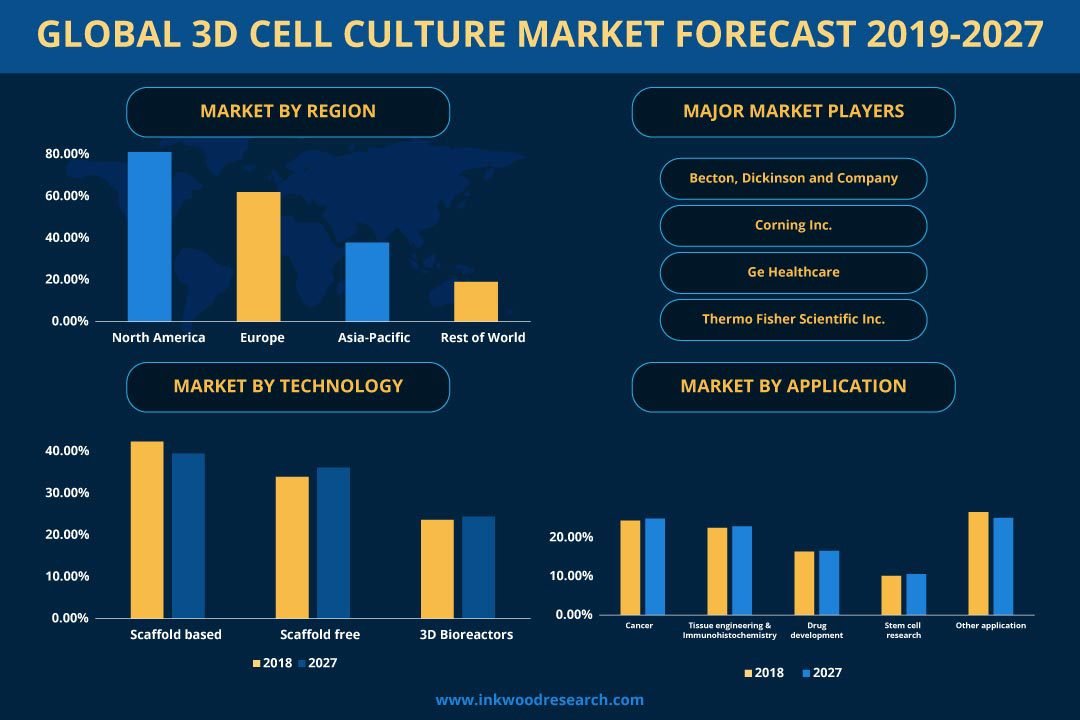
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
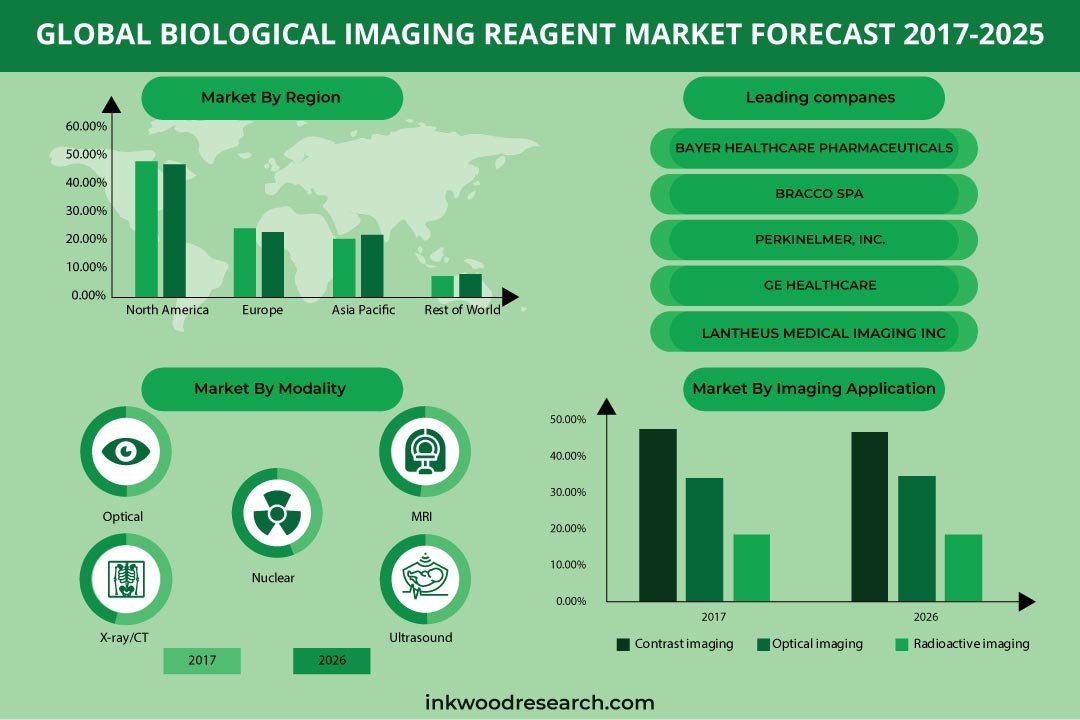
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-
UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034