
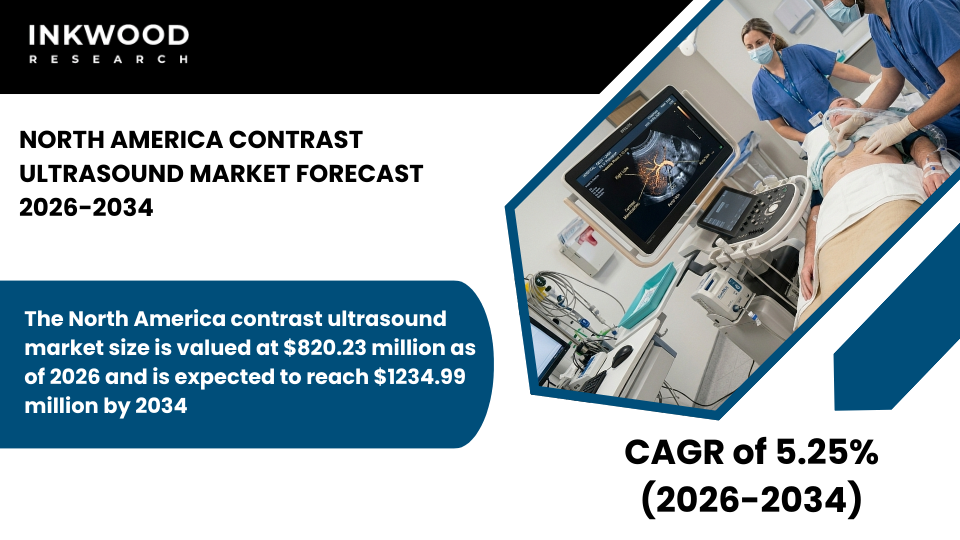
NORTH AMERICA CONTRAST ULTRASOUND MARKET FORECAST 2026-2034
SCOPE OF THE REPORT
North America Contrast Ultrasound Market by Product (Equipment, Contrast Agents) Market by Type (Non-Targeted, Targeted) Market by Application (Diagnostic Applications, Therapeutic Applications) Market by End Use (Hospitals, Clinics, Ambulatory Diagnostic Centers), by Geography
REPORTS » HEALTHCARE » MEDICAL DEVICES » NORTH AMERICA CONTRAST ULTRASOUND MARKET FORECAST 2026-2034
NORTH AMERICA CONTRAST ULTRASOUND MARKET OVERVIEW
The North America contrast ultrasound market size is valued at $820.23 million as of 2026 and is expected to reach $1234.99 million by 2034, progressing with a CAGR of 5.25% during the forecast years, 2026-2034.
North America’s contrast ultrasound market is experiencing steady growth driven by a unique convergence of clinical, regulatory, and demographic factors. The region benefits from well-established reimbursement frameworks that support the adoption of advanced imaging technologies, particularly in cardiac and oncological diagnostics.
Rising prevalence of cardiovascular diseases represents a critical growth driver, as the Centers for Disease Control and Prevention reports that heart disease remains the leading cause of death in the United States, with one person dying every 33-34 seconds from cardiovascular disease. Additionally, the aging population is creating sustained demand for enhanced ultrasound procedures that provide radiation-free diagnostic alternatives.
The U.S. Food and Drug Administration has expanded approval indications for ultrasound contrast agents beyond cardiac applications to include liver imaging and pediatric use, thereby broadening the addressable patient population. Furthermore, technological advancements in portable ultrasound devices are enabling point-of-care applications in emergency departments and intensive care units.
To Know More About This Report, Request a Free Sample Copy
Further, the integration of artificial intelligence in diagnostic imaging is improving workflow efficiency and diagnostic precision. These factors, in turn, are set to boost the contrast ultrasound market growth in North America during the forecast period.
The North America contrast ultrasound market growth assessment includes the analysis of the United States and Canada.
The United States dominates the North America contrast ultrasound market due to several structural advantages that create favorable conditions for market expansion. The country maintains a robust healthcare infrastructure with significant investments in advanced diagnostic equipment across hospitals, ambulatory surgical centers, and specialty imaging clinics.
Moreover, established clinical guidelines from organizations such as the American College of Cardiology and the Radiological Society of North America actively promote the use of contrast-enhanced ultrasound for specific indications, thereby standardizing practice patterns and encouraging adoption among healthcare providers. The presence of major medical device manufacturers and contrast agent developers within the United States accelerates innovation cycles and ensures the rapid commercialization of new technologies.
Reimbursement policies from the Centers for Medicare & Medicaid Services have evolved to cover contrast ultrasound procedures for cardiac and liver imaging applications, which reduces financial barriers for both providers and patients. The United States market also benefits from strong research and development activity, with leading academic medical centers conducting clinical trials to expand approved indications for contrast ultrasound technology.
Additionally, training programs and educational initiatives organized by professional societies are addressing the historical gap in sonographer proficiency, thereby improving the quality and consistency of contrast-enhanced studies across different healthcare settings. Plus, the shift toward value-based care models is incentivizing healthcare systems to adopt cost-effective imaging modalities that deliver accurate diagnostic information without exposing patients to ionizing radiation.
The growing emphasis on minimally invasive procedures in oncology and cardiology further supports market growth, as contrast ultrasound enables real-time visualization for guided biopsies, tumor ablations, and vascular interventions. Regulatory support from the FDA continues to play a pivotal role, with recent approvals expanding the use of microbubble-based contrast agents to pediatric populations and additional organ systems, thereby opening new revenue streams for manufacturers and creating broader clinical utility for healthcare providers.
Canada represents a smaller yet strategically important segment of the North America contrast ultrasound market, characterized by universal healthcare coverage and centralized procurement systems. Canadian healthcare authorities prioritize cost-effective diagnostic solutions that reduce wait times and improve patient outcomes, positioning contrast ultrasound as an attractive alternative to more expensive cross-sectional imaging modalities.
Provincial health ministries are gradually expanding reimbursement coverage for contrast ultrasound procedures, particularly in cardiology and hepatology, which is driving adoption across public hospitals and diagnostic imaging centers. The country’s relatively dispersed population creates opportunities for portable ultrasound systems equipped with contrast-enhanced capabilities, enabling access to advanced imaging in rural and remote communities where CT and MRI infrastructure may be limited.
The North America contrast ultrasound market is segmented into product, type, application, and end use. The product segment is further categorized into equipment and contrast agents.
The equipment segment holds significant importance within the North America contrast ultrasound market, as it encompasses the hardware infrastructure essential for performing advanced diagnostic imaging procedures. This segment includes high-end ultrasound systems equipped with specialized imaging modes such as contrast pulse sequencing, amplitude modulation, and power Doppler techniques that optimize microbubble detection while suppressing background tissue signals.
Leading manufacturers are introducing systems with integrated artificial intelligence capabilities that automate image optimization, lesion detection, and quantitative perfusion analysis, thereby reducing operator dependency and improving diagnostic consistency. The equipment segment is experiencing particularly strong growth in ambulatory diagnostic centers and outpatient clinics, where compact, user-friendly systems with touchscreen interfaces and wireless connectivity are enabling efficient workflow integration.
Moreover, technological innovations such as portable ultrasound devices with cloud-based image storage and telemedicine capabilities are expanding access to contrast-enhanced studies in emergency medicine and critical care environments. Competitive pricing strategies, flexible leasing arrangements, and equipment upgrade programs from major manufacturers are lowering barriers to entry for smaller healthcare facilities that previously lacked the capital resources to invest in advanced imaging technology.
Regulatory approvals from the FDA for expanded clinical indications are encouraging hospitals and imaging centers to replace aging ultrasound systems with next-generation platforms. These platforms are capable of supporting both diagnostic applications and emerging therapeutic applications such as targeted drug delivery and tumor ablation monitoring.
Some of the top players operating in the North America contrast ultrasound market include GE Healthcare, Lantheus Holdings Inc, Bracco Imaging SpA, and Siemens Healthineers AG, among others.
Lantheus Holdings Inc is a leading diagnostic imaging company headquartered in Bedford, Massachusetts, specializing in the development, manufacturing, and commercialization of innovative medical imaging agents and radiopharmaceuticals. The company operates through its subsidiary Lantheus Medical Imaging and maintains a focused portfolio serving cardiology, oncology, and neurology clinical pathways.
The company maintains strong commercial relationships with hospitals, imaging centers, and ambulatory surgical centers across North America, supported by dedicated sales teams and clinical education programs that train sonographers and cardiologists in optimal contrast-enhanced imaging techniques.
Lantheus differentiates itself through ongoing clinical development programs aimed at expanding approved indications for its contrast agents, strategic partnerships with ultrasound equipment manufacturers to ensure system compatibility, and investments in advanced manufacturing capabilities that ensure reliable product supply to meet growing market demand.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Product, Type, Application, End Use |
| Countries Analyzed | The United States and Canada |
| Companies Analyzed | GE HealthCare, Bracco Imaging SpA, Lantheus Holdings Inc, Siemens Healthineers AG, Koninklijke Philips NV, Bayer AG, Guerbet, Canon Medical Systems Corporation, Shenzhen Mindray Bio-Medical Electronics Co Ltd, Esaote SpA, FUJIFILM Holdings Corporation, Samsung Healthcare, Daiichi Sankyo Company Limited, Trivitron Healthcare Pvt Ltd, SuperSonic Imagine SA |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- THE CONTRAST ULTRASOUND MARKET IS EXPANDING STEADILY DUE TO RISING ADOPTION OF MICROBUBBLE-BASED IMAGING AGENTS IN CARDIOLOGY AND ONCOLOGY DIAGNOSTICS
- HOSPITALS REPRESENT THE LARGEST END-USER SEGMENT AS CONTRAST-ENHANCED ULTRASOUND IS INCREASINGLY USED FOR REAL-TIME PERFUSION ASSESSMENT
- NORTH AMERICA DRIVES MARKET REVENUE DUE TO ESTABLISHED REIMBURSEMENT FRAMEWORKS AND CLINICAL GUIDELINES
MARKET DYNAMICS
- KEY DRIVERS
- RISING PREVALENCE OF CARDIOVASCULAR DISEASES AND LIVER DISORDERS IS INCREASING DEMAND FOR ENHANCED DIAGNOSTIC ACCURACY
- GROWING PREFERENCE FOR MINIMALLY INVASIVE AND RADIATION-FREE IMAGING TECHNIQUES IS BOOSTING CONTRAST ULTRASOUND UTILIZATION
- TECHNOLOGICAL ADVANCEMENTS IN ULTRASOUND SYSTEMS ARE IMPROVING IMAGE RESOLUTION AND CLINICAL CONFIDENCE
- EXPANDING CLINICAL APPLICATIONS IN PEDIATRICS AND INTERVENTIONAL RADIOLOGY ARE BROADENING MARKET OPPORTUNITIES
- KEY RESTRAINTS
- LIMITED REIMBURSEMENT COVERAGE IN SEVERAL DEVELOPING MARKETS IS CONSTRAINING ADOPTION RATES
- REGULATORY COMPLEXITIES RELATED TO APPROVAL OF CONTRAST AGENTS CAN DELAY PRODUCT LAUNCHES
- LACK OF AWARENESS AND TRAINING AMONG SONOGRAPHERS MAY LIMIT OPTIMAL UTILIZATION
- COMPETITION FROM ALTERNATIVE IMAGING MODALITIES SUCH AS MRI AND CT SCANS MAY RESTRICT MARKET PENETRATION
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- INCREASING RESEARCH ON TARGETED MICROBUBBLE CONTRAST AGENTS IS DRIVING INNOVATION IN MOLECULAR IMAGING
- GROWING INTEGRATION OF ARTIFICIAL INTELLIGENCE IN ULTRASOUND WORKFLOWS IS ENHANCING DIAGNOSTIC PRECISION
- SHIFT TOWARD POINT-OF-CARE ULTRASOUND DEVICES IS EXPANDING ACCESS TO CONTRAST-ENHANCED STUDIES
- STRATEGIC COLLABORATIONS BETWEEN PHARMACEUTICAL AND MEDICAL DEVICE COMPANIES ARE ACCELERATING PRODUCT DEVELOPMENT
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR NORTH AMERICA
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SUPPLIERS
- CONTRAST AGENT MANUFACTURERS
- ULTRASOUND OEMS
- DISTRIBUTION PARTNERS
- HOSPITAL PROCUREMENT
- END-USER FACILITIES
- KEY BUYING CRITERIA
- IMAGE CLARITY
- SAFETY PROFILE
- REGULATORY APPROVAL
- COST EFFECTIVENESS
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
CONTRAST ULTRASOUND MARKET BY PRODUCT
- EQUIPMENT
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- CONTRAST AGENTS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- EQUIPMENT
CONTRAST ULTRASOUND MARKET BY TYPE
- NON-TARGETED
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- TARGETED
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- NON-TARGETED
CONTRAST ULTRASOUND MARKET BY APPLICATION
- DIAGNOSTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- THERAPEUTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DIAGNOSTIC APPLICATIONS
CONTRAST ULTRASOUND MARKET BY END USE
- HOSPITALS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- CLINICS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- AMBULATORY DIAGNOSTIC CENTERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- HOSPITALS
GEOGRAPHICAL ANALYSIS
- NORTH AMERICA
- MARKET SIZE & ESTIMATES
- NORTH AMERICA MARKET DRIVERS
- NORTH AMERICA MARKET CHALLENGES
- KEY PLAYERS IN NORTH AMERICA CONTRAST ULTRASOUND MARKET
- COUNTRY ANALYSIS
- UNITED STATES
- UNITED STATES MARKET SIZE & OPPORTUNITIES
- CANADA
- CANADA MARKET SIZE & OPPORTUNITIES
- UNITED STATES
- NORTH AMERICA
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- GE HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- BRACCO IMAGING SPA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- LANTHEUS HOLDINGS INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SIEMENS HEALTHINEERS AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- KONINKLIJKE PHILIPS NV
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- BAYER AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GUERBET
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- CANON MEDICAL SYSTEMS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ESAOTE SPA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- FUJIFILM HOLDINGS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SAMSUNG HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- DAIICHI SANKYO COMPANY LIMITED
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- TRIVITRON HEALTHCARE PVT LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SUPERSONIC IMAGINE SA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GE HEALTHCARE
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – CONTRAST ULTRASOUND
TABLE 2: CONTRAST ULTRASOUND MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY PRODUCT, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY PRODUCT, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: MARKET BY TYPE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: MARKET BY TYPE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: MARKET BY APPLICATION, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: MARKET BY APPLICATION, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: MARKET BY END USE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: MARKET BY END USE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: NORTH AMERICA MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 12: NORTH AMERICA MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 13: KEY PLAYERS OPERATING IN THE NORTH AMERICAN MARKET
TABLE 14: LIST OF MERGERS & ACQUISITIONS
TABLE 15: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 16: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 17: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR NORTH AMERICA
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY PRODUCT, IN 2025
FIGURE 11: EQUIPMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: CONTRAST AGENTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY TYPE, IN 2025
FIGURE 14: NON-TARGETED MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: TARGETED MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: SEGMENT GROWTH POTENTIAL, BY APPLICATION, IN 2025
FIGURE 17: DIAGNOSTIC APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: THERAPEUTIC APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: SEGMENT GROWTH POTENTIAL, BY END USE, IN 2025
FIGURE 20: HOSPITALS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: CLINICS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: AMBULATORY DIAGNOSTIC CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: NORTH AMERICA CONTRAST ULTRASOUND MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 24: UNITED STATES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: CANADA MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
EUROPE SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
NORTH AMERICA SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
SPAIN ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
MEXICO ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
ITALY ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
AUSTRALIA ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
BRAZIL ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
INDIA ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
GLOBAL ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
GLOBAL PHARMACEUTICAL 3D PRINTING MANUFACTURING MARKET FORECAST 2026-2034