India Wind Energy Market by Location / Installation Type (Onshore Wind, Offshore Wind (Fixed), Offshore Wind (Floating)), Market by Application (Utility-Scale Power Generation, Commercial & Industrial (C&I), Residential / Small Wind Turbines), Market by Turbine Capacity (Up to 1 MW, 1–3 MW, 3–10 MW, Above 10 MW), Market by End-User (Power Utilities, Independent Power Producers (IPP), Commercial Enterprises, Agricultural Users, Remote / Off-Grid Power Users), Market by Technology (Grid-Connected Systems, Off-Grid Systems), by Geography
INDIA WIND ENERGY MARKET OVERVIEW
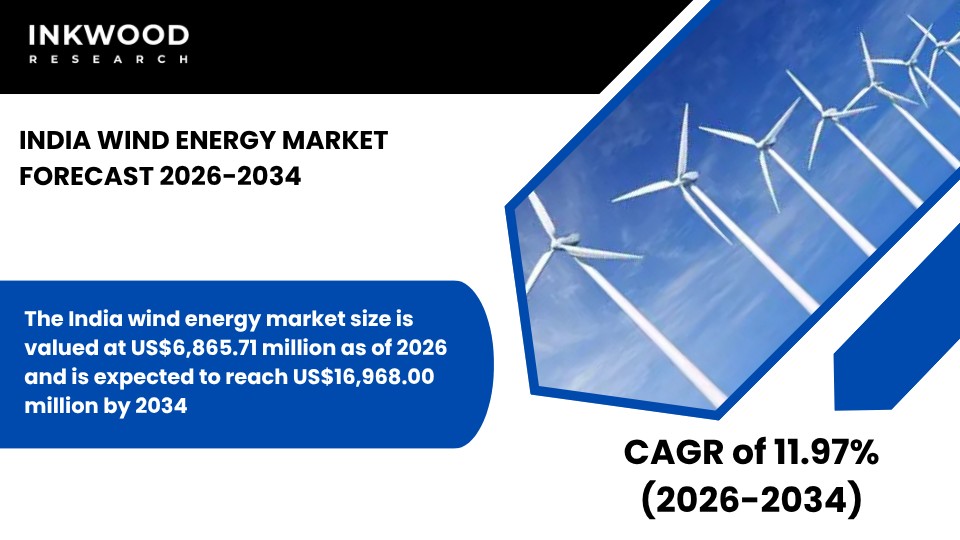
The India wind energy market size is valued at US$6,865.71 million as of 2026 and is expected to reach US$16,968.00 million by 2034, progressing with a CAGR of 11.97% during the forecast years, 2026-2034.
India’s wind energy market is experiencing robust expansion, fueled by the government’s ambitious renewable energy targets and strong commitment to achieving net-zero carbon emissions by 2070. As one of the world’s largest wind power producers, India has established significant installed capacity concentrated primarily in states like Tamil Nadu, Gujarat, Maharashtra, Karnataka, and Rajasthan, where abundant wind resources and supportive state-level policies create favorable conditions for large-scale wind farm development.
The country’s transition to auction-based tariff mechanisms has substantially improved price competitiveness, enabling wind power generation to compete effectively with conventional thermal electricity without requiring extensive subsidies. Moreover, falling turbine costs and technological advancements in rotor design have enhanced capacity factors, particularly for low and medium-wind speed sites that previously were considered economically unviable.
This technological progress has expanded the geographic scope for profitable wind energy projects beyond traditional high-wind zones. Additionally, rising corporate demand for clean electricity through open access mechanisms and corporate power purchase agreements is driving substantial private sector investment in new renewable energy installations.
Commercial enterprises across manufacturing, information technology, and industrial sectors are increasingly procuring wind power to meet sustainability goals and reduce carbon emissions from their operations. Furthermore, the integration of hybrid renewable energy projects that combine wind turbines with solar panels and battery storage systems is gaining momentum, as these configurations optimize land use and improve overall generation profiles throughout the day and across seasons.
To Know More About This Report, Request a Free Sample Copy
India’s policy framework for wind energy continues to evolve, with national and state governments implementing measures to accelerate capacity additions and address long-standing infrastructure challenges. The Ministry of New and Renewable Energy has established clear renewable energy targets that mandate significant wind power capacity additions during the forecast period, creating sustained demand for wind turbines and associated equipment.
However, the sector faces persistent challenges related to land acquisition processes, right-of-way permissions for transmission lines, and evacuation infrastructure constraints in high-wind states where grid capacity has not kept pace with generation growth. These transmission bottlenecks occasionally result in curtailment of wind power output, thereby reducing revenue potential for developers and affecting project economics.
To mitigate these risks, government authorities are investing in interstate transmission systems and green energy corridors designed to evacuate renewable electricity from generation-rich regions to demand centers in other parts of the country. Additionally, concerns about payment delays from state distribution companies (DISCOMs) continue to impact developer confidence and long-term revenue visibility, although regulatory interventions and financial reforms are gradually improving the creditworthiness of power utilities.
Despite these challenges, the shift toward larger rotor diameter wind turbines optimized for Indian wind conditions is enhancing project viability and attracting interest from both domestic and international investors. Moreover, the emergence of repowering opportunities, where aging wind farms are retrofitted with modern, higher-capacity turbines, represents a significant growth avenue that can unlock additional generation potential from existing sites without requiring new land acquisition.
Increased localization of turbine manufacturing through domestic production facilities is strengthening supply chains, reducing dependency on imports, and supporting the government’s Make in India initiative. These factors, combined with growing electricity demand from industrial and commercial sectors, are set to accelerate the wind energy market growth in India during the forecast period.
The India wind energy market is segmented into location/installation type, application, turbine capacity, end-user, and technology. The application segment is further categorized into utility-scale power generation, commercial & industrial (C&I), and residential/small wind turbines.
The commercial and industrial (C&I) segment is witnessing accelerated growth in India’s wind energy landscape, driven by corporate sustainability commitments and the availability of flexible procurement mechanisms. Unlike utility-scale projects that sell electricity primarily to power distribution companies, C&I wind installations enable commercial enterprises and industrial facilities to directly purchase renewable power through open access arrangements, captive consumption models, or group captive structures.
This segment has become increasingly attractive as regulatory frameworks have simplified the process for businesses to procure wind energy without relying solely on grid-supplied electricity from DISCOMs. Moreover, major corporations across sectors, including automotive manufacturing, pharmaceuticals, information technology, textiles, and cement production, are actively entering into long-term power purchase agreements with independent power producers to secure competitively priced wind power while reducing their operational carbon footprint.
These agreements provide revenue certainty for developers and enable commercial buyers to lock in electricity costs, thereby insulating them from volatile grid tariffs and fossil fuel price fluctuations. In addition, the C&I segment benefits from growing investor interest in renewable energy assets backed by creditworthy corporate off-takers, which improves financing terms and reduces overall project risk.
The segment also includes group captive models where multiple commercial consumers jointly invest in wind farms, sharing both the capital expenditure and the generated electricity, thereby making renewable energy projects accessible to smaller enterprises that might not have the capacity to develop standalone wind installations. Consequently, the commercial and industrial application segment is poised to capture an expanding share of new wind energy capacity additions throughout the forecast period.
Some of the top players operating in the India wind energy market include Suzlon Energy Limited, Vestas India, GE Renewable Energy, and Inox Wind Limited, etc.
Suzlon Energy Limited is a leading Indian wind turbine manufacturer headquartered in Pune, specializing in onshore wind power solutions with a strong domestic market presence and international operations. The company offers a comprehensive portfolio of wind turbines designed specifically for Indian wind conditions, along with integrated services covering project development, installation, and long-term maintenance support.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Location / Installation Type, Application, Turbine Capacity, End-User, and Technology |
| Country Analyzed | India |
| Companies Analyzed | Suzlon Energy Limited, Vestas India, GE Renewable Energy, Inox Wind Limited, Siemens Gamesa Renewable Energy, Adani Green Energy Ltd, Envision Energy |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- INDIA CONTINUES TO RANK AMONG THE TOP GLOBAL WIND POWER PRODUCERS WITH STRONG CONCENTRATION IN TAMIL NADU GUJARAT AND MAHARASHTRA
- ONSHORE WIND DOMINATES INSTALLED CAPACITY WHILE OFFSHORE DEVELOPMENT REMAINS AT A PRE-COMMERCIAL STAGE
- CAPACITY ADDITIONS HAVE BECOME MORE PRICE COMPETITIVE DUE TO AUCTION-BASED TARIFF MECHANISMS
- PRIVATE SECTOR IPPS ARE INCREASINGLY DRIVING NEW PROJECT DEVELOPMENT OVER STATE-OWNED UTILITIES
MARKET DYNAMICS
- KEY DRIVERS
- NATIONAL RENEWABLE ENERGY TARGETS AND NET ZERO COMMITMENTS ARE ACCELERATING WIND POWER DEPLOYMENT
- FALLING TURBINE COSTS AND IMPROVED CAPACITY FACTORS ARE IMPROVING PROJECT ECONOMICS
- RISING CORPORATE DEMAND FOR RENEWABLE POWER THROUGH OPEN ACCESS AND CPAS IS BOOSTING INSTALLATIONS
- GRID CONNECTED HYBRID PROJECTS COMBINING WIND AND SOLAR ARE ENHANCING UTILIZATION AND RETURNS
- KEY RESTRAINTS
- LAND ACQUISITION AND RIGHT OF WAY CHALLENGES CONTINUE TO DELAY PROJECT EXECUTION
- TRANSMISSION BOTTLENECKS IN HIGH WIND STATES LIMIT EVACUATION CAPACITY
- POLICY UNCERTAINTY AND DELAYS IN AUCTION SCHEDULING IMPACT INVESTOR CONFIDENCE
- DISCOM PAYMENT RISKS AFFECT LONG-TERM REVENUE VISIBILITY FOR DEVELOPERS
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- SHIFT TOWARD LARGER ROTOR DIAMETER TURBINES FOR LOW WIND SPEED SITES IS GAINING MOMENTUM
- WIND SOLAR HYBRID AND STORAGE LINKED PROJECTS ARE BECOMING MORE COMMON
- REPPOWERING OF OLD WIND FARMS IS EMERGING AS A LONG-TERM OPPORTUNITY
- INCREASED LOCALIZATION OF TURBINE MANUFACTURING IS SUPPORTING DOMESTIC SUPPLY CHAINS
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR INDIA
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- RAW MATERIAL & MACHINERY SUPPLIERS
- DESIGN & DEVELOPMENT SERVICES
- COMPONENT SUPPLIERS
- WIND TURBINE COMPANIES
- CONSTRUCTION AND INSTALLATION SERVICES
- WIND FARM DEVELOPERS
- KEY BUYING CRITERIA
- GOVERNMENT POLICIES AND INCENTIVES
- TECHNOLOGICAL ADVANCEMENTS
- ENVIRONMENTAL AWARENESS AND SUSTAINABILITY
- ENVIRONMENTAL AND SOCIAL IMPACT ASSESSMENTS
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
WIND ENERGY MARKET BY LOCATION / INSTALLATION TYPE
- ONSHORE WIND
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- OFFSHORE WIND (FIXED)
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- OFFSHORE WIND (FLOATING)
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- ONSHORE WIND
WIND ENERGY MARKET BY APPLICATION
- UTILITY-SCALE POWER GENERATION
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- COMMERCIAL & INDUSTRIAL (C&I)
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- RESIDENTIAL / SMALL WIND TURBINES
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- UTILITY-SCALE POWER GENERATION
WIND ENERGY MARKET BY TURBINE CAPACITY
- UP TO 1 MW
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- 1–3 MW
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- 3–10 MW
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- ABOVE 10 MW
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- UP TO 1 MW
WIND ENERGY MARKET BY END-USER
- POWER UTILITIES
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- INDEPENDENT POWER PRODUCERS (IPP)
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- COMMERCIAL ENTERPRISES
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- AGRICULTURAL USERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- REMOTE / OFF-GRID POWER USERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- POWER UTILITIES
WIND ENERGY MARKET BY TECHNOLOGY
- GRID-CONNECTED SYSTEMS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- OFF-GRID SYSTEMS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- GRID-CONNECTED SYSTEMS
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- SUZLON ENERGY LIMITED
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- VESTAS INDIA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GE RENEWABLE ENERGY
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- INOX WIND LIMITED
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SIEMENS GAMESA RENEWABLE ENERGY
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ADANI GREEN ENERGY LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ENVISION ENERGY
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SUZLON ENERGY LIMITED
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – WIND ENERGY
TABLE 2: WIND ENERGY MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY LOCATION / INSTALLATION TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY LOCATION / INSTALLATION TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: MARKET BY APPLICATION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: MARKET BY APPLICATION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: MARKET BY TURBINE CAPACITY, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: MARKET BY TURBINE CAPACITY, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: MARKET BY END-USER, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: MARKET BY END-USER, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: MARKET BY TECHNOLOGY, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 12: MARKET BY TECHNOLOGY, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 13: KEY PLAYERS OPERATING IN THE INDIAN MARKET
TABLE 14: LIST OF MERGERS & ACQUISITIONS
TABLE 15: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 16: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 17: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR INDIA
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY LOCATION / INSTALLATION TYPE, IN 2025
FIGURE 11: ONSHORE WIND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: OFFSHORE WIND (FIXED) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: OFFSHORE WIND (FLOATING) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 14: SEGMENT GROWTH POTENTIAL, BY APPLICATION, IN 2025
FIGURE 15: UTILITY-SCALE POWER GENERATION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: COMMERCIAL & INDUSTRIAL (C&I) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: RESIDENTIAL / SMALL WIND TURBINES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: SEGMENT GROWTH POTENTIAL, BY TURBINE CAPACITY, IN 2025
FIGURE 19: UP TO 1 MW MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: 1–3 MW MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: 3–10 MW MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: ABOVE 10 MW MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: SEGMENT GROWTH POTENTIAL, BY END-USER, IN 2025
FIGURE 24: POWER UTILITIES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: INDEPENDENT POWER PRODUCERS (IPP) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: COMMERCIAL ENTERPRISES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: AGRICULTURAL USERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: REMOTE / OFF-GRID POWER USERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 29: SEGMENT GROWTH POTENTIAL, BY TECHNOLOGY, IN 2025
FIGURE 30: GRID-CONNECTED SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: OFF-GRID SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
JAPAN AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
INDIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
CHINA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034