India Unified Energy Interface (UEI) EV Charging Market by Deployment (Public Charging Platforms, Private Charging Platforms), by Vehicle Type (Electric Two-Wheelers, Electric Three-Wheelers, Passenger Electric Cars, Commercial Electric Vehicles), by Charging Infrastructure Type (Public, Private, Fleet, Residential), by Installation Type (Fixed Charger, Portable Charger), and by Geography.
INDIA UNIFIED ENERGY INTERFACE (UEI) EV CHARGING MARKET OVERVIEW
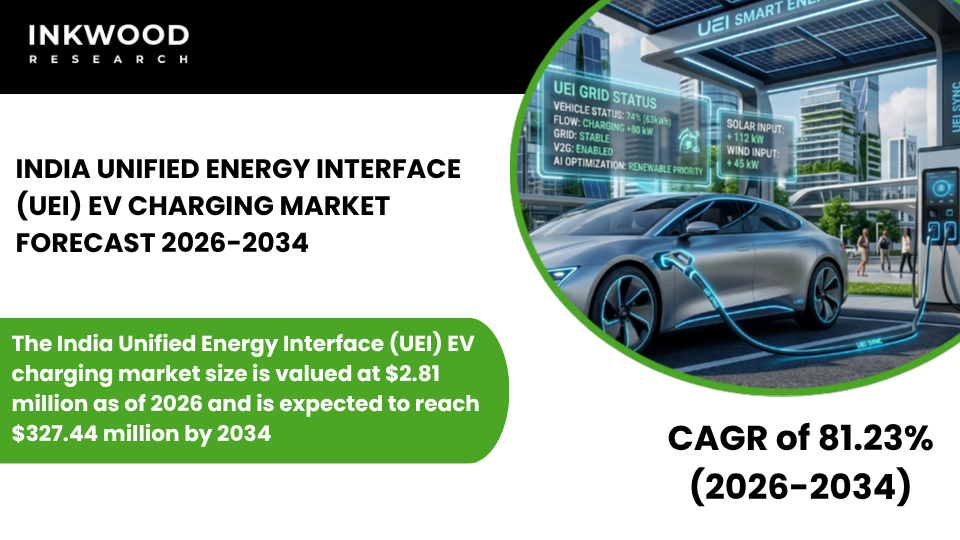
The India Unified Energy Interface (UEI) EV charging market size is valued at $2.81 million as of 2026 and is expected to reach $327.44 million by 2034, progressing with a CAGR of 81.23% during the forecast years, 2026–2034.
MARKET INSIGHTS
The Unified Energy Interface (UEI) is India’s homegrown open network protocol for EV charging interoperability, built on the Beckn Protocol, the same open-source, Made-in-India technology that powers the Open Network for Digital Commerce (ONDC). Launched formally in April 2024 by an alliance of 20 energy companies, UEI functions as a UPI-like system for EV charging, enabling any user-facing application to discover, book, and pay for charging sessions across any participating charging network, without requiring pre-existing bilateral roaming agreements between operators.
Aligning with this, founding members include ChargeZone, Pulse Energy, Kazam, Sheru, and Trinity. Critically, the Department of Science and Technology (DST), under the request of Niti Aayog, conducted a year-long consultative process with charging network players, DISCOMs, and EV OEMs, concluding unanimously that UEI is the recommended interoperability protocol for India’s EV charging ecosystem. This government endorsement, alongside advocacy from the Ministry of Power, positions UEI as the foundational digital layer for India’s rapidly expanding EV charging infrastructure.
Furthermore, the UEI ecosystem has grown rapidly since its inception. By December 2024, the UEI Alliance had expanded to 30 members and was facilitating over 13,000 EV charging sessions daily, dispersing approximately 60 MWh of energy per day. This growth is being driven by a powerful macro tailwind: India’s EV market recorded 19 lakh vehicle sales in 2024, a 19% increase over 2023, while public charging stations crossed 25,000 nationally by the end of 2024, per the International Council on Clean Transportation (ICCT).
The government’s flagship PM E-DRIVE scheme, launched in October 2024 with a total outlay of ₹10,900 crore, allocated ₹2,000 crore specifically for the rollout of 72,300 public charging stations. This infrastructure push creates the physical network on which UEI’s digital interoperability layer will operate, making the two developments mutually reinforcing and commercially complementary.
Beyond EV charging, UEI’s broader potential as an energy transaction protocol is also gaining visibility. The India Smart Grid Forum (ISGF) has highlighted UEI’s capability to enable peer-to-peer (P2P) green energy payments, potentially unlocking commercial settlements for the 10 million rooftop solar PV systems being deployed under the PM Suryoday Yojana. The UEI Alliance is also engaging with DISCOMs to bring grid-readiness into the protocol, enabling vehicle-to-grid and demand response use cases.
However, the market faces meaningful near-term barriers. Interoperability with legacy charging networks, high system integration costs, and limited awareness among smaller charge point operators (CPOs) remain friction points. Additionally, data security and trust in open-network financial reconciliation must be reinforced as transaction volumes scale.
For vendors and investors, the convergence of rapid EV adoption, government-mandated charging expansion, and UEI’s growing network effects represents one of the most compelling emerging digital infrastructure opportunities in India’s clean mobility sector. These factors, in turn, are set to influence the UEI EV charging market growth in India during the forecast period.
To Know More About This Report, Request a Free Sample Copy
SEGMENTATION ANALYSIS
The India UEI EV charging market is segmented by deployment, vehicle type, charging infrastructure type, and installation type. The vehicle type segment is further categorized into electric two-wheelers, electric three-wheelers, passenger electric cars, and commercial electric vehicles.
Electric two-wheelers represent the largest and most strategically critical vehicle type sub-segment within the India UEI EV charging market. This sub-segment encompasses all UEI-enabled charging discovery, payment, and session management transactions initiated by electric scooter and motorcycle users across India’s public and private charging networks.
Electric two-wheelers dominate India’s overall EV landscape by volume, with the PM E-DRIVE scheme alone targeting incentives for approximately 24.79 lakh e-2Ws, per the Ministry of Heavy Industries. Under the PM E-DRIVE framework, 48,400 fast chargers are being deployed specifically for e-2Ws and e-3Ws, creating a dense and rapidly expanding physical network that UEI’s interoperability layer is designed to unify.
For e-2W riders, the UEI protocol directly addresses one of the most cited barriers to EV adoption: the need to install and manage multiple operator-specific apps to access charging across different networks. By enabling seamless discovery and payment through any UEI-integrated application, including navigation platforms and OEM dashboards, UEI significantly reduces friction for this user segment.
Furthermore, the high daily charging frequency of commercial e-2Ws used in food delivery and logistics creates a substantial, high-velocity transaction volume opportunity for UEI platform providers. As more charge point operators integrate UEI compliance into their networks, the electric two-wheeler sub-segment is expected to anchor a dominant share of UEI transaction volumes throughout the forecast period.
COMPETITIVE INSIGHTS
Some of the top players operating in the India UEI EV charging market include Pulse Energy, Kazam, ChargeZone, and Sheru, among others.
Kazam is a Bengaluru-based EV technology company and a founding member of the UEI Alliance, positioned as one of the leading software enablement platforms for EV charging networks in India. Rather than operating its own charging hardware, Kazam provides a white-label software platform that empowers charge point operators, fleet managers, and energy providers to digitize and manage their charging infrastructure. Its platform enables real-time charger monitoring, session management, payment integration, and remote diagnostics, all of which are compatible with UEI’s open-network protocol.
As a UEI tech enabler, Kazam has integrated the UEI network into its platform, allowing its CPO customers to make their chargers discoverable and transactable across any UEI-connected application. This positioning makes Kazam a critical infrastructure middleware player in India’s UEI EV charging market, with the ability to onboard large numbers of chargers onto the open network rapidly through its existing CPO client base.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Deployment, Vehicle Type, Charging Infrastructure Type, Installation Type |
| Country Analyzed | India |
| Companies Analyzed | Pulse Energy, Kazam, ChargeZone, Sheru, Thunder, Turno, VerdeMobility, BrightBlu, DeCharge Network, Lioncharge E-Mobility Pvt Ltd |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE, SHARE & ESTIMATES
- MARKET OVERVIEW
- SCOPE OF STUDY
- MAJOR MARKET FINDINGS
- INDIA UNIFIED ENERGY INTERFACE ENABLES INTEROPERABLE AND STANDARDIZED EV CHARGING ECOSYSTEMS ACROSS MULTIPLE NETWORK OPERATORS
- RAPID EV ADOPTION IN URBAN CENTERS IS DRIVING DEMAND FOR SEAMLESS DIGITAL DISCOVERY AND PAYMENT SOLUTIONS THROUGH UEI
- PUBLIC AND PRIVATE SECTOR COLLABORATIONS ARE ACCELERATING DEPLOYMENT OF UEI-INTEGRATED CHARGING INFRASTRUCTURE
- UEI IS EMERGING AS A KEY ENABLER FOR SMART GRID INTEGRATION AND ENERGY MANAGEMENT IN THE EV CHARGING LANDSCAPE
MARKET DYNAMICS
- KEY DRIVERS
- GOVERNMENT INITIATIVES PROMOTING OPEN DIGITAL NETWORKS AND EV ECOSYSTEM STANDARDIZATION DRIVE UEI ADOPTION
- INCREASING EV PENETRATION AND RISING DEMAND FOR CONVENIENT CHARGING ACCESS SUPPORT MARKET EXPANSION
- GROWTH IN DIGITAL PAYMENT INFRASTRUCTURE FACILITATES SEAMLESS TRANSACTIONS ACROSS CHARGING NETWORKS
- RISING INVESTMENTS IN SMART ENERGY AND GRID DIGITALIZATION BOOST UEI-BASED PLATFORM DEVELOPMENT
- KEY RESTRAINTS
- LACK OF AWARENESS AND LIMITED EARLY-STAGE IMPLEMENTATION HINDER WIDESPREAD UEI ADOPTION
- INTEROPERABILITY CHALLENGES AMONG LEGACY CHARGING NETWORKS SLOW DOWN INTEGRATION PROCESSES
- HIGH INITIAL INVESTMENT REQUIREMENTS FOR DIGITAL INFRASTRUCTURE AND SYSTEM UPGRADES CREATE ENTRY BARRIERS
- DATA SECURITY AND PRIVACY CONCERNS MAY LIMIT TRUST AND PARTICIPATION AMONG USERS AND OPERATORS
- KEY DRIVERS
STRATEGIC MARKET ANALYTICS
- GROWTH METRICS
- TAM, SAM & SOM OPPORTUNITY ANALYSIS
- EMERGING MARKET TRENDS & PARADIGM SHIFTS
- INCREASING INTEGRATION OF UEI WITH MOBILE APPS FOR REAL-TIME CHARGING STATION DISCOVERY AND PAYMENTS
- GROWING FOCUS ON OPEN PROTOCOLS AND API-BASED ECOSYSTEMS TO ENABLE CROSS-PLATFORM INTEROPERABILITY
- EXPANSION OF UEI USE CASES INTO RENEWABLE ENERGY TRADING AND VEHICLE-TO-GRID APPLICATIONS
- RISING COLLABORATIONS BETWEEN ENERGY COMPANIES, FINTECH FIRMS, AND EV OEMS TO SCALE UEI ECOSYSTEMS
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- PESTLE ANALYSIS
- POLITICAL
- ECONOMIC
- SOCIAL LANDSCAPE
- TECHNOLOGY
- LEGAL
- ENVIRONMENTAL
- GROWTH OPPORTUNITY MAPPING & HEATMAP
- GROWTH PROSPECT MAPPING FOR INDIA
- MARKET MATURITY & LIFECYCLE ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- GROWTH METRICS
UNIFIED ENERGY INTERFACE (UEI) EV CHARGING VALUE CHAIN & DECISION FRAMEWORK
- VALUE CHAIN ANALYSIS
- HARDWARE MANUFACTURING
- SOFTWARE DEVELOPMENT
- PLATFORM INTEGRATION
- NETWORK OPERATORS
- PAYMENT PROCESSING
- END-USER SERVICES
- KEY BUYING CRITERIA
- INTEROPERABILITY LEVEL
- PLATFORM RELIABILITY
- TRANSACTION SECURITY
- SCALABILITY FEATURES
- PRICING MODELS, TARIFF STRUCTURES & CHARGING NETWORK OPTIMIZATION STRATEGIES
- REGULATORY & POLICY LANDSCAPE ANALYSIS
- VALUE CHAIN ANALYSIS
UNIFIED ENERGY INTERFACE (UEI) EV CHARGING MARKET BY DEPLOYMENT
- PUBLIC CHARGING PLATFORMS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PRIVATE CHARGING PLATFORMS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PUBLIC CHARGING PLATFORMS
UNIFIED ENERGY INTERFACE (UEI) EV CHARGING MARKET BY VEHICLE TYPE
- ELECTRIC TWO-WHEELERS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ELECTRIC THREE-WHEELERS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PASSENGER ELECTRIC CARS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- COMMERCIAL ELECTRIC VEHICLES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ELECTRIC TWO-WHEELERS
UNIFIED ENERGY INTERFACE (UEI) EV CHARGING MARKET BY CHARGING INFRASTRUCTURE TYPE
- PUBLIC
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PRIVATE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- FLEET
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- RESIDENTIAL
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PUBLIC
UNIFIED ENERGY INTERFACE (UEI) EV CHARGING MARKET BY INSTALLATION TYPE
- FIXED CHARGER
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PORTABLE CHARGER
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- FIXED CHARGER
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPETITOR POSITIONING & DIFFERENTIATION MAP
- COMPANY PROFILES
- PULSE ENERGY
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- KAZAM
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- CHARGEZONE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- SHERU
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- THUNDER
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- TURNO
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- VERDEMOBILITY
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- BRIGHTBLU
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- DECHARGE NETWORK
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- LIONCHARGE E-MOBILITY PVT LTD
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- PULSE ENERGY
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – UNIFIED ENERGY INTERFACE (UEI) EV CHARGING MARKET
TABLE 2: PRICING MODELS, TARIFF STRUCTURES & CHARGING NETWORK OPTIMIZATION STRATEGIES
TABLE 3: REGULATORY & POLICY LANDSCAPE ANALYSIS
TABLE 4: MARKET BY DEPLOYMENT, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 5: MARKET BY DEPLOYMENT, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 6: MARKET BY VEHICLE TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 7: MARKET BY VEHICLE TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 8: MARKET BY CHARGING INFRASTRUCTURE TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 9: MARKET BY CHARGING INFRASTRUCTURE TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 10: MARKET BY INSTALLATION TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 11: MARKET BY INSTALLATION TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 12: KEY PLAYERS OPERATING IN THE INDIAN MARKET
TABLE 13: LIST OF MERGERS & ACQUISITIONS
TABLE 14: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 15: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 16: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR INDIA
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY DEPLOYMENT, IN 2025
FIGURE 11: PUBLIC CHARGING PLATFORMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: PRIVATE CHARGING PLATFORMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY VEHICLE TYPE, IN 2025
FIGURE 14: ELECTRIC TWO-WHEELERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: ELECTRIC THREE-WHEELERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: PASSENGER ELECTRIC CARS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: COMMERCIAL ELECTRIC VEHICLES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: SEGMENT GROWTH POTENTIAL, BY CHARGING INFRASTRUCTURE TYPE, IN 2025
FIGURE 19: PUBLIC MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: PRIVATE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: FLEET MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: RESIDENTIAL MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: SEGMENT GROWTH POTENTIAL, BY INSTALLATION TYPE, IN 2025
FIGURE 24: FIXED CHARGER MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: PORTABLE CHARGER MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
JAPAN AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
INDIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
CHINA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034