
GLOBAL AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET FORECAST 2026-2034
SCOPE OF THE REPORT
Global Autonomous Robotic Process Automation (RPA) Bots Market by Autonomy Level (Semi-Autonomous RPA Bots, Fully Autonomous RPA Bots) Market by Capability Type (Self-Healing Automation, Self-Learning Automation, Decision-Aware Automation, Adaptive Workflow Automation) Market by Deployment Model (Cloud-Based, On-Premise, Hybrid) Market by Enterprise Size (Large Enterprises, SMEs) Market by Industry Vertical (BFSI, Healthcare, Telecom, Retail & E-Commerce, Manufacturing, Government & Public Sector)
GLOBAL AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET OVERVIEW
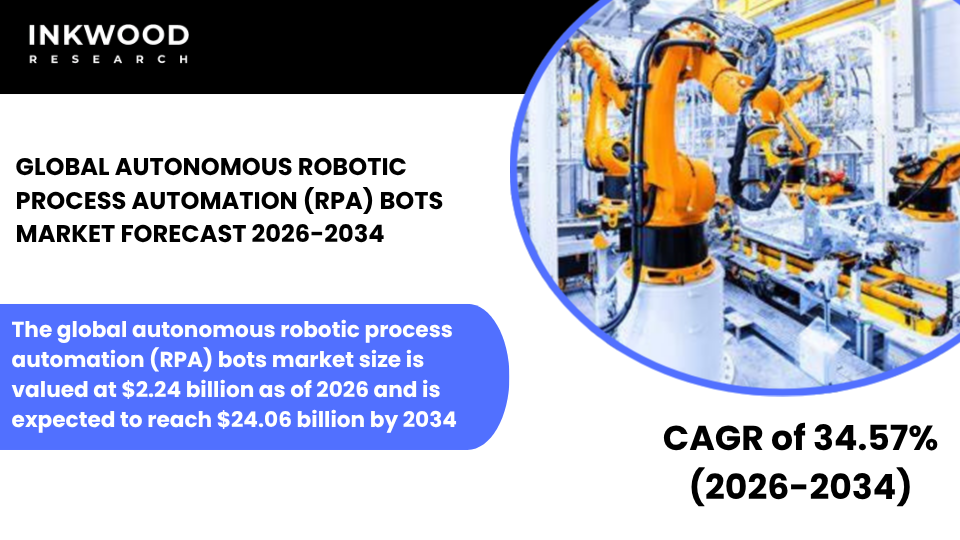
The global autonomous robotic process automation (RPA) bots market size is valued at $2.24 billion as of 2026 and is expected to reach $24.06 billion by 2034, growing at a CAGR of 34.57% during the forecast period 2026–2034. The base year considered for the study is 2025, and the forecast period is between 2026 and 2034. The market study has also analyzed the crisis impact on the autonomous robotic process automation (RPA) bots market qualitatively as well as quantitatively.
Autonomous robotic process automation bots are software-driven agents that execute complex, rule-based, and increasingly judgment-intensive business tasks without requiring constant human direction. Unlike traditional RPA, which relies on scripted workflows and human oversight to manage exceptions, autonomous RPA bots are embedded with artificial intelligence, machine learning, and natural language processing capabilities that allow them to perceive process context, adapt to changing data environments, and make independent decisions in real time.
These bots can be deployed across a wide range of enterprise functions, from invoice processing and compliance reporting to customer onboarding and IT service management, operating continuously without fatigue, downtime, or manual handoffs. As enterprises grow more complex in their digital operations, autonomous robotic process automation bots are becoming foundational components of the modern digital workforce, bridging the gap between simple task automation and fully autonomous enterprise process management.
The global autonomous RPA bots market is growing rapidly, driven by surging enterprise demand for hyperautomation, rising operational cost pressures, and the accelerating integration of AI into core business workflows. Organizations across BFSI, healthcare, manufacturing, and telecom are actively investing in intelligent RPA bots to eliminate manual bottlenecks, reduce errors, and scale operations more efficiently. The shift from rule-based automation to AI-powered RPA bots is redefining how enterprises approach digital transformation, making autonomous automation a strategic imperative rather than an optional upgrade.
To Know More About This Report, Request a Free Sample Copy
GROWTH ENABLERS
Key enablers of the global autonomous robotic process automation (RPA) bots market growth:
- Rising enterprise demand for hyperautomation is accelerating the deployment of autonomous RPA bots to streamline operations and improve workflow efficiency
- Integration of artificial intelligence and machine learning capabilities is enabling RPA bots to perform self-learning, adaptive decision-making, and continuous process optimization
- Increasing pressure to reduce operational costs and labor dependency is driving organizations to implement autonomous digital workforce solutions
- The cost reduction imperative is one of the most compelling catalysts propelling the adoption of autonomous RPA automation at scale. According to the U.S. Bureau of Labor Statistics, labor costs account for the largest share of operating expenses across service-intensive industries such as BFSI, healthcare, and retail. Enterprises deploying intelligent RPA bots to automate high-volume transactional workflows, such as accounts payable, claims adjudication, and order fulfillment, have consistently reported significant reductions in cost-per-transaction and full-time employee (FTE) dependency.
- As labor markets tighten and wage inflation persists across developed economies, the financial case for AI-powered RPA bots becomes increasingly difficult to ignore. This is particularly evident among large enterprises managing thousands of discrete process tasks daily, where autonomous automation delivers compounding efficiency gains across the entire operations stack.
- Growing adoption of cloud infrastructure and digital transformation initiatives is supporting scalable deployment of autonomous RPA systems across enterprise environments
Key growth restraining factors of the global autonomous robotic process automation (RPA) bots market:
- High initial implementation costs and integration complexities with legacy enterprise systems can slow down the adoption of autonomous RPA bots
- Concerns related to data security, governance, and regulatory compliance may limit the deployment of autonomous automation in highly regulated industries
- Limited availability of skilled professionals with expertise in AI-driven automation and RPA bot management can create implementation challenges
- Organizational resistance to automation due to fears of job displacement and change management barriers can delay enterprise-wide deployment. This restraint carries significant real-world weight. According to research published by the World Economic Forum, concerns over technology-driven job displacement remain among the top barriers to workforce automation adoption, particularly in economies with lower reskilling infrastructure.
- Employees and middle management layers may actively or passively resist the integration of next-generation RPA automation into daily workflows, creating friction during change management processes. Enterprises that underinvest in internal communication, retraining initiatives, and transition support risk encountering implementation stalls, reduced bot utilization rates, and suboptimal returns on their automation investments. This organizational inertia can substantially delay the value realization timeline for autonomous RPA solutions for enterprises, especially in the public sector and traditionally structured industries.
KEY MARKET TRENDS
Global Autonomous Robotic Process Automation (RPA) Bots Industry | Top Trends
- One of the most transformative trends reshaping the autonomous RPA bots market is the rise of self-healing and self-learning automation architectures. Traditional RPA deployments were notoriously brittle, any change in a UI element, application update, or process deviation could break a bot workflow entirely. Today, leading vendors are embedding machine learning models directly into their autonomous RPA platforms, enabling bots to detect workflow disruptions, automatically reconfigure themselves, and resume operations without human intervention. This capability dramatically reduces bot maintenance costs and downtime, making autonomous robotic process automation bots far more resilient and production-ready across dynamic enterprise environments.
- The convergence of generative AI with autonomous RPA automation is unlocking a fundamentally new class of process automation capabilities. AI-powered RPA bots can now interpret unstructured data sources, such as emails, contracts, customer chat logs, and scanned documents, and translate them into structured, actionable process outputs. According to IBM, generative AI integration into automation platforms enables bots to not only execute tasks but also summarize outcomes, generate reports, and engage in natural language interactions with enterprise systems. This trend is particularly consequential for industries like BFSI and healthcare, where large volumes of unstructured data have historically resisted automation. The integration of NLP and generative AI is, therefore, rapidly expanding the addressable use cases for intelligent RPA bots.
- Vendors across the autonomous RPA bots market are aggressively developing low-code and no-code automation interfaces to democratize bot creation beyond IT departments. Platforms such as UiPath StudioX and Microsoft Power Automate allow business analysts and process owners to design, configure, and deploy autonomous digital workforce automation workflows without deep programming expertise. This trend is significantly accelerating enterprise adoption by reducing reliance on scarce technical talent and compressing bot deployment timelines. As a result, more business units within large enterprises, from HR and finance to supply chain and customer service, are becoming active participants in the autonomous RPA automation ecosystem.
- Enterprises are increasingly moving away from purely cloud-based or purely on-premise deployments in favor of hybrid automation architectures that combine the scalability of cloud with the data sovereignty and latency advantages of on-premise infrastructure. This shift is particularly pronounced in regulated industries such as banking, insurance, and government, where sensitive process data cannot always reside on public cloud platforms. Hybrid models allow organizations to run computationally intensive AI workloads in the cloud while keeping critical transactional bots and sensitive data on-premise. As a result, the demand for flexible, enterprise-grade autonomous RPA solutions is growing steadily, with vendors investing in hybrid deployment capabilities to capture this expanding segment.
MARKET SEGMENTATION
Market Segmentation – Autonomy Level, Capability Type, Deployment Model, Enterprise Size, and Industry Vertical –
Market by Autonomy Level:
- Semi-Autonomous RPA Bots
- Semi-autonomous RPA bots represent the foundational tier of the autonomous robotic process automation bots market, operating within structured workflows that still require periodic human validation or intervention for exception handling and high-stakes decisions. These bots are typically deployed across well-defined, rule-based processes where the majority of tasks can be automated, but edge cases, such as ambiguous data inputs, compliance-sensitive approvals, or multi-system reconciliation errors, still require a human-in-the-loop model.
- Key features include pre-built workflow templates, supervised learning models, integration with enterprise ERP and CRM systems, and real-time escalation protocols that route exceptions to human agents efficiently. Their appeal lies in their lower risk profile and faster deployment timelines compared to fully autonomous alternatives, making them particularly attractive to organizations in the early stages of their automation journey.
- Demand for semi-autonomous RPA bots continues to grow steadily, supported by new platform releases from leading vendors and ongoing regulatory requirements in sectors like BFSI and healthcare that mandate human oversight for certain process categories. For instance, financial institutions subject to Basel III and GDPR compliance frameworks often opt for semi-autonomous configurations to ensure auditability and human accountability in automated decision chains.
- Fully Autonomous RPA Bots
Market by Capability Type:
- Self-Healing Automation
- Self-Learning Automation
- Decision-Aware Automation
- Adaptive Workflow Automation
Market by Deployment Model:
- Cloud-Based
- On-Premise
- Hybrid
Market by Enterprise Size:
- Large Enterprises
- SMEs
Market by Industry Vertical:
- BFSI
- Healthcare
- Telecom
- Retail & E-Commerce
- Manufacturing
- Government & Public Sector
Geographical Study based on Four Major Regions:
- North America: The United States and Canada
- The North America autonomous robotic process automation (RPA) bots market size is valued at $874.81 million as of 2026 and is expected to reach $8,557.37 million by 2034, growing at a CAGR of 32.99% during the forecast period 2026–2034.
- North America holds the largest share of the global autonomous RPA bots market, underpinned by the region’s advanced digital infrastructure, high enterprise technology spending, and a mature ecosystem of both established vendors and high-growth automation startups.
- The United States, in particular, is a dominant force; large financial institutions, healthcare networks, and technology companies have been early and aggressive adopters of AI-powered RPA bots, embedding autonomous automation deeply into back-office, compliance, and customer-facing operations.
- Canada is following closely, with growing investment in automation across its banking and public sector verticals, supported by national digitalization strategies. According to the U.S. Department of Commerce, technology investment across American enterprises continues to grow year-over-year, and enterprise automation platforms are increasingly positioned as critical productivity infrastructure.
- Europe: The United Kingdom, Germany, France, Italy, Spain, Poland, Belgium, and Rest of Europe
- The Europe autonomous robotic process automation (RPA) bots market size is valued at $623.31 million as of 2026 and is expected to reach $6,445.40 million by 2034, growing at a CAGR of 33.91% during the forecast period 2026–2034.
- Europe’s autonomous RPA automation market is experiencing strong and consistent growth, driven by the region’s intensive regulatory environment and the increasing urgency of operational efficiency improvements across its largest economies.
- The United Kingdom, despite the structural shifts of Brexit, remains a frontrunner in enterprise automation adoption, particularly within financial services, insurance, and professional services, where intelligent RPA bots are deployed to manage compliance-heavy workflows under FCA guidelines.
- Germany, as Europe’s largest industrial economy, is channeling significant investment into autonomous robotic process automation bots as part of its broader Industrie 4.0 digitalization agenda, with manufacturing, automotive, and logistics sectors representing key verticals.
- Asia-Pacific: China, India, Japan, Australia & New Zealand, South Korea, Thailand, Indonesia, Vietnam, Singapore, and Rest of Asia-Pacific
- The Asia-Pacific autonomous robotic process automation (RPA) bots market size is valued at $524.24 million as of 2026 and is expected to reach $6,938.86 million by 2034, growing at a CAGR of 38.11% during the forecast period 2026–2034.
- Asia-Pacific is the fastest-growing region in the global autonomous RPA bots market, recording the highest CAGR, driven by rapid digital transformation across China, India, Japan, and Southeast Asian emerging markets.
- China’s national AI development strategy, articulated through its New Generation Artificial Intelligence Development Plan, has created significant state-level momentum for enterprise automation, with domestic technology giants and financial institutions deploying AI-powered RPA bots at unprecedented scale.
- Japan, facing acute demographic pressures and a shrinking labor force, has emerged as one of the most receptive markets for autonomous digital workforce automation globally. Moreover, government initiatives supporting workforce automation and productivity enhancement have directly accelerated enterprise bot adoption across manufacturing, retail, and logistics sectors.
- Meanwhile, India’s rapidly expanding BPO and IT services industry is transitioning from labor-arbitrage models toward intelligent process automation bots, fundamentally reshaping the economics of outsourced service delivery across the region.
- Rest of World: Latin America, the Middle East & Africa
Our market research reports offer an in-depth analysis of individual country-level market size and growth statistics. We cover the segmentation analysis, key growth factors, and macro-economic trends within the autonomous robotic process automation (RPA) bots market, providing detailed insights into –
- Germany Autonomous Robotic Process Automation (RPA) Bots Market
- Japan Autonomous Robotic Process Automation (RPA) Bots Market
- China Autonomous Robotic Process Automation (RPA) Bots Market
- Canada Autonomous Robotic Process Automation (RPA) Bots Market
- France Autonomous Robotic Process Automation (RPA) Bots Market
- Australia Autonomous Robotic Process Automation (RPA) Bots Market
- South Korea Autonomous Robotic Process Automation (RPA) Bots Market
MAJOR PLAYERS
The major players in the global autonomous robotic process automation (RPA) bots market are:
- UiPath Inc
- Automation Anywhere Inc
- SS&C Blue Prism Limited
- Microsoft Corporation
- Pegasystems Inc
Key strategies adopted by some of these companies:
- UiPath launched its Autopilot feature within the UiPath Business Automation Platform, integrating generative AI directly into its autonomous RPA bots to enable natural language-based bot creation and process orchestration. This development significantly lowers the technical barrier for enterprise users seeking to deploy intelligent RPA bots without deep coding expertise, expanding UiPath’s reach across business-led automation initiatives.
- Automation Anywhere entered into a strategic partnership with Google Cloud to embed Google’s Vertex AI and Gemini large language models into its AI-powered RPA bots platform, enabling enterprises to deploy generative AI-enhanced autonomous automation across business-critical workflows. This collaboration accelerates the convergence of enterprise automation bots with frontier AI capabilities, making Automation Anywhere a compelling choice for organizations pursuing end-to-end autonomous digital workforce automation.
- Microsoft significantly expanded its Power Automate platform by integrating Copilot AI capabilities, enabling users to describe automation workflows in natural language and have the system generate autonomous RPA sequences automatically. This enhancement positions Microsoft as a formidable player in the next-generation RPA automation space, leveraging its existing enterprise footprint to drive widespread adoption of autonomous RPA solutions for enterprises across its global customer base.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Autonomy Level, Capability Type, Deployment Model, Enterprise Size, Industry Vertical |
| Geographies Analyzed | North America, Europe, Asia-Pacific, Rest of World |
| Companies Analyzed | UiPath Inc, Automation Anywhere Inc, SS&C Blue Prism Limited, Microsoft Corporation, Pegasystems Inc, NICE Ltd, IBM Corporation, SAP SE, Tungsten Automation, WorkFusion Inc, Appian Corporation, EdgeVerve Systems Limited |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY & KEY INSIGHTS
- MARKET SIZE, SHARE & ESTIMATES
- MARKET OVERVIEW
- SCOPE OF STUDY
- MAJOR MARKET FINDINGS
- ENTERPRISES ARE INCREASINGLY ADOPTING AUTONOMOUS RPA BOTS TO REDUCE MANUAL INTERVENTION AND ENABLE CONTINUOUS PROCESS AUTOMATION ACROSS COMPLEX DIGITAL WORKFLOWS
- FULLY AUTONOMOUS RPA BOTS ARE GAINING MOMENTUM AS ORGANIZATIONS SEEK AI-DRIVEN AUTOMATION THAT CAN HANDLE EXCEPTION MANAGEMENT AND DECISION-MAKING WITHOUT HUMAN SUPERVISION
- CLOUD-BASED DEPLOYMENT MODELS ARE DOMINATING MARKET ADOPTION DUE TO THEIR SCALABILITY, LOWER INFRASTRUCTURE COSTS, AND EASE OF INTEGRATION WITH ENTERPRISE APPLICATIONS
- BFSI AND HEALTHCARE SECTORS REPRESENT MAJOR ADOPTION HUBS AS THESE INDUSTRIES REQUIRE HIGH-VOLUME TRANSACTION PROCESSING, REGULATORY COMPLIANCE, AND DATA-INTENSIVE OPERATIONS
MARKET DYNAMICS
- KEY DRIVERS
- RISING ENTERPRISE DEMAND FOR HYPERAUTOMATION IS ACCELERATING THE DEPLOYMENT OF AUTONOMOUS RPA BOTS TO STREAMLINE OPERATIONS AND IMPROVE WORKFLOW EFFICIENCY
- INTEGRATION OF ARTIFICIAL INTELLIGENCE AND MACHINE LEARNING CAPABILITIES IS ENABLING RPA BOTS TO PERFORM SELF-LEARNING, ADAPTIVE DECISION-MAKING, AND CONTINUOUS PROCESS OPTIMIZATION
- INCREASING PRESSURE TO REDUCE OPERATIONAL COSTS AND LABOR DEPENDENCY IS DRIVING ORGANIZATIONS TO IMPLEMENT AUTONOMOUS DIGITAL WORKFORCE SOLUTIONS
- GROWING ADOPTION OF CLOUD INFRASTRUCTURE AND DIGITAL TRANSFORMATION INITIATIVES IS SUPPORTING SCALABLE DEPLOYMENT OF AUTONOMOUS RPA SYSTEMS ACROSS ENTERPRISE ENVIRONMENTS
- KEY RESTRAINTS
- HIGH INITIAL IMPLEMENTATION COSTS AND INTEGRATION COMPLEXITIES WITH LEGACY ENTERPRISE SYSTEMS CAN SLOW DOWN THE ADOPTION OF AUTONOMOUS RPA BOTS
- CONCERNS RELATED TO DATA SECURITY, GOVERNANCE, AND REGULATORY COMPLIANCE MAY LIMIT THE DEPLOYMENT OF AUTONOMOUS AUTOMATION IN HIGHLY REGULATED INDUSTRIES
- LIMITED AVAILABILITY OF SKILLED PROFESSIONALS WITH EXPERTISE IN AI-DRIVEN AUTOMATION AND RPA BOT MANAGEMENT CAN CREATE IMPLEMENTATION CHALLENGES
- ORGANIZATIONAL RESISTANCE TO AUTOMATION DUE TO FEARS OF JOB DISPLACEMENT AND CHANGE MANAGEMENT BARRIERS CAN DELAY ENTERPRISE-WIDE DEPLOYMENT
- KEY DRIVERS
STRATEGIC MARKET ANALYTICS
- GROWTH METRICS
- TAM, SAM & SOM OPPORTUNITY ANALYSIS
- EMERGING MARKET TRENDS & PARADIGM SHIFTS
- EMERGENCE OF SELF-HEALING AND SELF-LEARNING AUTOMATION CAPABILITIES IS TRANSFORMING TRADITIONAL RPA INTO INTELLIGENT AUTONOMOUS PROCESS AUTOMATION SYSTEMS
- INTEGRATION OF GENERATIVE AI AND NATURAL LANGUAGE PROCESSING IS ENABLING RPA BOTS TO HANDLE UNSTRUCTURED DATA AND CUSTOMER INTERACTION WORKFLOWS
- VENDORS ARE DEVELOPING LOW-CODE AND NO-CODE AUTOMATION PLATFORMS THAT ALLOW BUSINESS USERS TO DESIGN AND DEPLOY AUTONOMOUS BOTS WITHOUT ADVANCED PROGRAMMING SKILLS
- ENTERPRISES ARE SHIFTING TOWARD HYBRID AUTOMATION ARCHITECTURES THAT COMBINE CLOUD AND ON-PREMISE DEPLOYMENT FOR FLEXIBILITY, SECURITY, AND PERFORMANCE OPTIMIZATION
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- PESTLE ANALYSIS
- POLITICAL
- ECONOMIC
- SOCIAL LANDSCAPE
- TECHNOLOGY
- LEGAL
- ENVIRONMENTAL
- GROWTH OPPORTUNITY MAPPING & HEATMAP
- GROWTH PROSPECT MAPPING FOR NORTH AMERICA
- GROWTH PROSPECT MAPPING FOR EUROPE
- GROWTH MAPPING PROSPECT FOR ASIA-PACIFIC
- GROWTH MAPPING PROSPECT FOR REST OF WORLD
- MARKET MATURITY & LIFECYCLE ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- GROWTH METRICS
AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS VALUE CHAIN & DECISION FRAMEWORK
- VALUE CHAIN ANALYSIS
- AI MODEL DEVELOPMENT
- RPA PLATFORM DEVELOPMENT
- SYSTEM INTEGRATION SERVICES
- BOT DEPLOYMENT MANAGEMENT
- PROCESS MONITORING ANALYTICS
- ENTERPRISE SUPPORT SERVICES
- KEY BUYING CRITERIA
- AUTOMATION SCALABILITY
- AI INTEGRATION CAPABILITY
- DEPLOYMENT FLEXIBILITY
- ENTERPRISE SECURITY COMPLIANCE
- PRICING MODELS, LICENSING STRUCTURES & COST OPTIMIZATION STRATEGIES
- REGULATORY & POLICY LANDSCAPE ANALYSIS
- VALUE CHAIN ANALYSIS
AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET BY AUTONOMY LEVEL
- SEMI-AUTONOMOUS RPA BOTS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- FULLY AUTONOMOUS RPA BOTS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SEMI-AUTONOMOUS RPA BOTS
AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET BY CAPABILITY TYPE
- SELF-HEALING AUTOMATION
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SELF-LEARNING AUTOMATION
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- DECISION-AWARE AUTOMATION
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ADAPTIVE WORKFLOW AUTOMATION
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SELF-HEALING AUTOMATION
AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET BY DEPLOYMENT MODEL
- CLOUD-BASED
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ON-PREMISE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- HYBRID
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- CLOUD-BASED
AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET BY ENTERPRISE SIZE
- LARGE ENTERPRISES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SMES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- LARGE ENTERPRISES
AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET BY INDUSTRY VERTICAL
- BFSI
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- HEALTHCARE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- TELECOM
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- RETAIL & E-COMMERCE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- MANUFACTURING
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- GOVERNMENT & PUBLIC SECTOR
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- BFSI
GEOGRAPHICAL ANALYSIS
- NORTH AMERICA
- MARKET SIZE & ESTIMATES
- NORTH AMERICA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET DRIVERS
- NORTH AMERICA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET CHALLENGES
- KEY REGIONAL PLAYERS & ECOSYSTEM
- COUNTRY ANALYSIS
- UNITED STATES
- UNITED STATES AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- CANADA
- CANADA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- UNITED STATES
- EUROPE
- MARKET SIZE & ESTIMATES
- EUROPE AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET DRIVERS
- EUROPE AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET CHALLENGES
- KEY REGIONAL PLAYERS & ECOSYSTEM
- COUNTRY ANALYSIS
- UNITED KINGDOM
- UNITED KINGDOM AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- GERMANY
- GERMANY AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- FRANCE
- FRANCE AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- ITALY
- ITALY AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- SPAIN
- SPAIN AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- BELGIUM
- BELGIUM AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- POLAND
- POLAND AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- REST OF EUROPE
- REST OF EUROPE AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- UNITED KINGDOM
- ASIA-PACIFIC
- MARKET ESTIMATES & SIZES
- ASIA-PACIFIC AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET DRIVERS
- ASIA-PACIFIC AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET CHALLENGES
- KEY REGIONAL PLAYERS & ECOSYSTEM
- COUNTRY ANALYSIS
- CHINA
- CHINA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- JAPAN
- JAPAN AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- AUSTRALIA & NEW ZEALAND
- AUSTRALIA & NEW ZEALAND AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- INDIA
- INDIA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- SOUTH KOREA
- SOUTH KOREA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- INDONESIA
- INDONESIA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- THAILAND
- THAILAND AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- VIETNAM
- VIETNAM AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- SINGAPORE
- SINGAPORE AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- REST OF ASIA-PACIFIC
- REST OF ASIA-PACIFIC AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- CHINA
- REST OF WORLD
- MARKET ESTIMATES & SIZES
- REST OF WORLD AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET DRIVERS
- REST OF WORLD AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET CHALLENGES
- KEY REGIONAL PLAYERS & ECOSYSTEM
- REGIONAL ANALYSIS
- LATIN AMERICA
- LATIN AMERICA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- MIDDLE EAST & AFRICA
- MIDDLE EAST & AFRICA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET SIZE & OPPORTUNITIES
- LATIN AMERICA
- NORTH AMERICA
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPETITOR POSITIONING & DIFFERENTIATION MAP
- COMPANY PROFILES
- UIPATH INC
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- AUTOMATION ANYWHERE INC
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- SS&C BLUE PRISM LIMITED
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- MICROSOFT CORPORATION
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- PEGA SYSTEMS INC
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- NICE LTD
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- IBM CORPORATION
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- SAP SE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- TUNGSTEN AUTOMATION
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- WORKFUSION INC
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- APPIAN CORPORATION
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- EDGEVERVE SYSTEMS LIMITED
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- UIPATH INC
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS
TABLE 2: PRICING MODELS, LICENSING STRUCTURES & COST OPTIMIZATION STRATEGIES FOR AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS
TABLE 3: REGULATORY & POLICY LANDSCAPE ANALYSIS
TABLE 4: MARKET BY AUTONOMY LEVEL, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 5: MARKET BY AUTONOMY LEVEL, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 6: SEMI-AUTONOMOUS RPA BOTS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 7: SEMI-AUTONOMOUS RPA BOTS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 8: FULLY AUTONOMOUS RPA BOTS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 9: FULLY AUTONOMOUS RPA BOTS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 10: MARKET BY CAPABILITY TYPE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 11: MARKET BY CAPABILITY TYPE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 12: SELF-HEALING AUTOMATION MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 13: SELF-HEALING AUTOMATION MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 14: SELF-LEARNING AUTOMATION MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 15: SELF-LEARNING AUTOMATION MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 16: DECISION-AWARE AUTOMATION MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 17: DECISION-AWARE AUTOMATION MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 18: ADAPTIVE WORKFLOW AUTOMATION MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 19: ADAPTIVE WORKFLOW AUTOMATION MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 20: MARKET BY DEPLOYMENT MODEL, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 21: MARKET BY DEPLOYMENT MODEL, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 22: CLOUD-BASED MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 23: CLOUD-BASED MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 24: ON-PREMISE MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 25: ON-PREMISE MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 26: HYBRID MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 27: HYBRID MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 28: MARKET BY ENTERPRISE SIZE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 29: MARKET BY ENTERPRISE SIZE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 30: LARGE ENTERPRISES MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 31: LARGE ENTERPRISES MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 32: SMES MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 33: SMES MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 34: MARKET BY INDUSTRY VERTICAL, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 35: MARKET BY INDUSTRY VERTICAL, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 36: BFSI MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 37: BFSI MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 38: HEALTHCARE MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 39: HEALTHCARE MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 40: TELECOM MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 41: TELECOM MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 42: RETAIL & E-COMMERCE MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 43: RETAIL & E-COMMERCE MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 44: MANUFACTURING MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 45: MANUFACTURING MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 46: GOVERNMENT & PUBLIC SECTOR MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 47: GOVERNMENT & PUBLIC SECTOR MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 48: MARKET BY GEOGRAPHICAL ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 49: MARKET BY GEOGRAPHICAL ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 50: NORTH AMERICA MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 51: NORTH AMERICA MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 52: KEY PLAYERS OPERATING IN THE NORTH AMERICAN MARKET
TABLE 53: EUROPE MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 54: EUROPE MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 55: KEY PLAYERS OPERATING IN THE EUROPEAN MARKET
TABLE 56: ASIA-PACIFIC MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 57: ASIA-PACIFIC MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 58: KEY PLAYERS OPERATING IN THE ASIA-PACIFIC MARKET
TABLE 59: REST OF WORLD MARKET, REGIONAL ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 60: REST OF WORLD MARKET, REGIONAL ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 61: KEY PLAYERS OPERATING IN THE REST OF WORLD MARKET
TABLE 62: LIST OF MERGERS & ACQUISITIONS
TABLE 63: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 64: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 65: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR NORTH AMERICA
FIGURE 6: GROWTH PROSPECT MAPPING FOR EUROPE
FIGURE 7: GROWTH PROSPECT MAPPING FOR ASIA-PACIFIC
FIGURE 8: GROWTH PROSPECT MAPPING FOR REST OF WORLD
FIGURE 9: MARKET MATURITY ANALYSIS
FIGURE 10: MARKET CONCENTRATION ANALYSIS
FIGURE 11: VALUE CHAIN ANALYSIS
FIGURE 12: KEY BUYING CRITERIA
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY AUTONOMY LEVEL, IN 2025
FIGURE 14: SEMI-AUTONOMOUS RPA BOTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: FULLY AUTONOMOUS RPA BOTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: SEGMENT GROWTH POTENTIAL, BY CAPABILITY TYPE, IN 2025
FIGURE 17: SELF-HEALING AUTOMATION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: SELF-LEARNING AUTOMATION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: DECISION-AWARE AUTOMATION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: ADAPTIVE WORKFLOW AUTOMATION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: SEGMENT GROWTH POTENTIAL, BY DEPLOYMENT MODEL, IN 2025
FIGURE 22: CLOUD-BASED MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: ON-PREMISE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: HYBRID MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: SEGMENT GROWTH POTENTIAL, BY ENTERPRISE SIZE, IN 2025
FIGURE 26: LARGE ENTERPRISES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: SMES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: SEGMENT GROWTH POTENTIAL, BY INDUSTRY VERTICAL, IN 2025
FIGURE 29: BFSI MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: HEALTHCARE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: TELECOM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 32: RETAIL & E-COMMERCE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 33: MANUFACTURING MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 34: GOVERNMENT & PUBLIC SECTOR MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 35: NORTH AMERICA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 36: UNITED STATES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 37: CANADA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 38: EUROPE AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 39: GERMANY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 40: UNITED KINGDOM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 41: FRANCE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 42: ITALY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 43: SPAIN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 44: BELGIUM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 45: POLAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 46: REST OF EUROPE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 47: ASIA-PACIFIC AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 48: CHINA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 49: INDIA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 50: JAPAN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 51: AUSTRALIA & NEW ZEALAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 52: SOUTH KOREA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 53: THAILAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 54: INDONESIA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 55: VIETNAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 56: SINGAPORE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 57: REST OF ASIA-PACIFIC MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 58: REST OF WORLD AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET, REGIONAL OUTLOOK, 2025 & 2034 (IN %)
FIGURE 59: LATIN AMERICA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 60: MIDDLE EAST & AFRICA MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
FAQs
Autonomous robotic process automation bots are AI-powered software agents that execute complex business processes end-to-end without requiring human supervision. Unlike traditional RPA, autonomous RPA bots can make contextual decisions, handle exceptions independently, and continuously learn from process data to improve performance over time.
Traditional RPA bots follow fixed, rule-based scripts and require human intervention whenever an exception or process deviation occurs. Autonomous RPA bots, by contrast, integrate AI and machine learning to handle unstructured data, adapt to process changes, and make independent decisions, making them far more resilient and scalable for complex enterprise workflows.
Autonomous robotic process automation bots are most widely deployed in BFSI, healthcare, telecom, manufacturing, retail and e-commerce, and government sectors. These industries benefit most from autonomous automation due to their high transaction volumes, stringent compliance requirements, and extensive data-intensive operations that demand continuous, accurate processing.
Yes, AI is the defining capability that distinguishes autonomous RPA bots from conventional automation tools. AI-powered RPA bots leverage machine learning, natural language processing, computer vision, and generative AI to interpret unstructured inputs, optimize workflows, and execute judgment-based tasks without manual oversight, effectively functioning as intelligent digital workers within enterprise environments.
The key benefits of autonomous RPA bots for enterprise automation include significant reductions in operational costs, faster process cycle times, elimination of manual errors, 24/7 continuous process execution, and the ability to scale automation across complex, multi-system workflows without proportional increases in headcount. Enterprises also benefit from improved compliance auditability and enhanced workforce productivity as employees are freed from repetitive tasks.
The future of autonomous RPA automation lies in the deeper integration of generative AI, large language models, and agentic AI frameworks that will enable next-generation RPA automation platforms to plan, execute, and optimize multi-step business processes with minimal human configuration. As autonomous digital workforce automation matures, enterprises can expect bots to evolve from process executors into proactive business intelligence agents capable of identifying new automation opportunities and orchestrating enterprise-wide workflow optimization autonomously.
RELATED REPORTS
-
SOUTH KOREA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET FORECAST 2026-2034
-
JAPAN AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET FORECAST 2026-2034
-
GERMANY AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET FORECAST 2026-2034
-
FRANCE AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET FORECAST 2026-2034
-
CANADA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET FORECAST 2026-2034
-
AUSTRALIA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET FORECAST 2026-2034
-
CHINA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET FORECAST 2026-2034
-
GLOBAL ELDER CARE ASSISTIVE ROBOTS MARKET FORECAST 2025-2032
-

GERMANY AUTONOMOUS MOBILE ROBOTS (AMR) MARKET FORECAST 2025-2032
-

JAPAN AUTONOMOUS MOBILE ROBOTS (AMR) MARKET FORECAST 2025-2032