
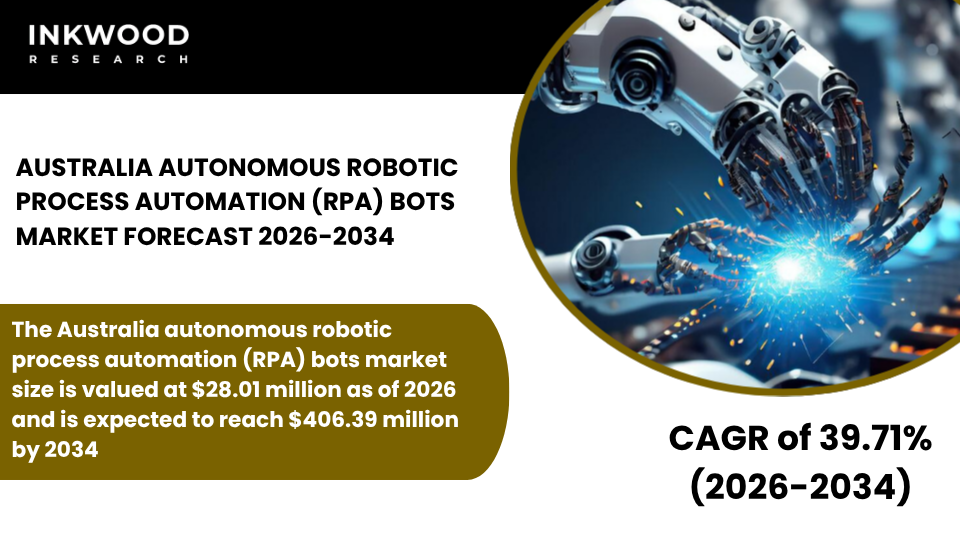
AUSTRALIA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET FORECAST 2026-2034
SCOPE OF THE REPORT
Australia Autonomous Robotic Process Automation (RPA) Bots Market by Autonomy Level (Semi-Autonomous RPA Bots, Fully Autonomous RPA Bots) Market by Capability Type (Self-Healing Automation, Self-Learning Automation, Decision-Aware Automation, Adaptive Workflow Automation) Market by Deployment Model (Cloud-Based, On-Premise, Hybrid) Market by Enterprise Size (Large Enterprises, SMEs) Market by Industry Vertical (BFSI, Healthcare, Telecom, Retail & E-Commerce, Manufacturing, Government & Public Sector)
REPORTS » REGIONAL REPORTS » COUNTRY » AUSTRALIA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET FORECAST 2026-2034
AUSTRALIA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET OVERVIEW
The Australia autonomous robotic process automation (RPA) bots market size is valued at $28.01 million as of 2026 and is expected to reach $406.39 million by 2034, progressing with a CAGR of 39.71% during the forecast years, 2026–2034.
MARKET INSIGHTS
Australia is emerging as one of the most dynamic markets for autonomous robotic process automation bots in the Asia-Pacific region, driven by a convergence of strong digital transformation investment, labor market pressures, and a proactive regulatory environment. Australian enterprises across BFSI, government, healthcare, and telecom are progressively moving beyond legacy rule-based automation, turning instead to intelligent RPA bots that can handle complex, judgment-intensive workflows without continuous human supervision.
This shift is being actively encouraged at a policy level; the Australian Government’s Digital Economy Strategy has committed significant investment toward accelerating enterprise digitalization and building a modern, technology-enabled public and private sector workforce. The regulatory landscape plays a particularly important role in shaping demand for autonomous RPA automation in Australia.
The Privacy Act 1988, currently undergoing significant reform as recommended by the Attorney-General’s Department, introduces stricter data handling requirements that are encouraging enterprises to deploy governed, auditable AI-powered RPA bots rather than manual or ad-hoc automation processes. Similarly, the Australian Prudential Regulation Authority (APRA) Prudential Standard CPS 234 on information security is driving financial institutions to invest in compliant, security-hardened autonomous RPA solutions that can automate sensitive workflows while maintaining regulatory accountability.
For vendors and investors, these regulatory tailwinds represent a compelling market entry signal. Aligning with this, organizations are not simply choosing to automate, but are increasingly required to do so within a structured compliance framework that favors intelligent, traceable autonomous RPA systems. Beyond compliance, Australia’s tight labor market is an equally powerful demand catalyst.
The Australian Bureau of Statistics (ABS) has consistently reported low unemployment and elevated labor costs across service-intensive sectors, creating a strong financial imperative for enterprises to deploy autonomous digital workforce automation at scale. Large banks, insurance providers, telecommunications companies, and government agencies are actively piloting and scaling intelligent RPA bots to reduce operational headcount dependency, accelerate service delivery, and maintain competitiveness.
The growing maturity of cloud infrastructure in Australia, supported by the Australian Signals Directorate’s (ASD) Cloud Security Guidance and major hyperscaler expansions by AWS, Microsoft Azure, and Google Cloud in Sydney and Melbourne, is further enabling scalable, enterprise-grade autonomous RPA deployments across the country. Together, these factors are set to sustain strong growth momentum in the Australia autonomous RPA bots market throughout the forecast period.
To Know More About This Report, Request a Free Sample Copy
SEGMENTATION ANALYSIS
The Australia autonomous robotic process automation (RPA) bots market is segmented by autonomy level, capability type, deployment model, enterprise size, and industry vertical. The industry vertical segment is further categorized into BFSI, healthcare, telecom, retail and e-commerce, manufacturing, and government and public sector.
The BFSI vertical stands out as a leading and strategically significant segment within the Australia autonomous RPA bots market. Australian banks, insurers, and financial services firms are under persistent pressure to reduce cost-to-income ratios, accelerate digital onboarding, and meet increasingly stringent compliance obligations set by regulators such as APRA and ASIC.
Autonomous RPA bots are being deployed extensively across loan origination, fraud detection, trade reconciliation, regulatory reporting, and customer dispute resolution workflows. These processes are high in volume, repetitive in structure, yet sensitive enough to require accurate, auditable outcomes.
Further, the sector’s appetite for AI-powered RPA bots is further amplified by the ongoing fallout from the Royal Commission into Misconduct in the Banking, Superannuation and Financial Services Industry, which has heightened accountability requirements across automated and manual processes alike. For vendors, the BFSI vertical offers the clearest near-term revenue opportunity, particularly for solutions that combine autonomous execution with robust compliance logging and governance capabilities.
COMPETITIVE INSIGHTS
Some of the top players operating in the Australia autonomous robotic process automation (RPA) bots market include UiPath Inc, Automation Anywhere Inc, Microsoft Corporation, IBM Corporation, etc.
UiPath Inc is a New York-headquartered enterprise automation platform provider and one of the most prominent players in the global and Australian autonomous RPA bots market. The company offers a comprehensive suite of AI-powered RPA bots, process mining tools, and intelligent document processing solutions under its Business Automation Platform, with purpose-built capabilities for industries such as BFSI, healthcare, and government. UiPath has an established and growing presence in Australia, serving major financial institutions and public sector agencies through both direct enterprise sales and a broad network of local implementation partners.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Autonomy Level, Capability Type, Deployment Model, Enterprise Size, Industry Vertical |
| Country Analyzed | Australia |
| Companies Analyzed | UiPath Inc, Automation Anywhere Inc, SS&C Blue Prism Limited, Microsoft Corporation, Pegasystems Inc, NICE Ltd, IBM Corporation, SAP SE, Tungsten Automation, Appian Corporation |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE, SHARE & ESTIMATES
- MARKET OVERVIEW
- SCOPE OF STUDY
- MAJOR MARKET FINDINGS
- AUSTRALIAN ENTERPRISES ARE INCREASINGLY IMPLEMENTING AUTONOMOUS RPA BOTS TO IMPROVE OPERATIONAL EFFICIENCY AND BUSINESS PROCESS AUTOMATION
- THE BFSI, GOVERNMENT, AND TELECOM SECTORS ARE AMONG THE LARGEST ADOPTERS OF INTELLIGENT AUTOMATION SOLUTIONS
- ORGANIZATIONS ARE INTEGRATING RPA WITH AI AND ADVANCED ANALYTICS TO ENABLE AUTONOMOUS DECISION-MAKING CAPABILITIES
- AUSTRALIA IS EXPERIENCING GROWING INVESTMENT IN DIGITAL TRANSFORMATION PROGRAMS THAT INCLUDE AUTOMATED DIGITAL WORKFORCES
MARKET DYNAMICS
- KEY DRIVERS
- RAPID ENTERPRISE DIGITAL TRANSFORMATION INITIATIVES ARE ACCELERATING ADOPTION OF AUTONOMOUS RPA SOLUTIONS
- INCREASING DEMAND FOR COST REDUCTION AND PROCESS EFFICIENCY IS DRIVING AUTOMATION INVESTMENTS
- EXPANSION OF CLOUD COMPUTING INFRASTRUCTURE IS SUPPORTING SCALABLE DEPLOYMENT OF INTELLIGENT AUTOMATION TECHNOLOGIES
- STRONG GOVERNMENT FOCUS ON DIGITAL GOVERNANCE AND PUBLIC SERVICE MODERNIZATION IS BOOSTING AUTOMATION ADOPTION
- KEY RESTRAINTS
- HIGH IMPLEMENTATION COSTS AND INTEGRATION COMPLEXITIES WITH EXISTING ENTERPRISE SYSTEMS RESTRAIN MARKET EXPANSION
- DATA PRIVACY AND CYBERSECURITY CONCERNS CREATE BARRIERS FOR FULLY AUTONOMOUS AUTOMATION DEPLOYMENTS
- LIMITED AVAILABILITY OF AUTOMATION SPECIALISTS AND RPA ARCHITECTS SLOWS ENTERPRISE IMPLEMENTATION
- ORGANIZATIONAL RESISTANCE TO DIGITAL WORKFORCE TRANSFORMATION LIMITS AUTOMATION INITIATIVES
- KEY DRIVERS
STRATEGIC MARKET ANALYTICS
- GROWTH METRICS
- TAM, SAM & SOM OPPORTUNITY ANALYSIS
- EMERGING MARKET TRENDS & PARADIGM SHIFTS
- ENTERPRISES ARE ADOPTING HYPERAUTOMATION STRATEGIES THAT INTEGRATE RPA WITH AI, PROCESS MINING, AND INTELLIGENT ANALYTICS
- GROWING USE OF AUTONOMOUS RPA BOTS IN FINANCE OPERATIONS, CUSTOMER SUPPORT, AND COMPLIANCE MANAGEMENT
- AUSTRALIAN ORGANIZATIONS ARE ESTABLISHING AUTOMATION CENTERS OF EXCELLENCE TO SCALE DIGITAL WORKFORCE MANAGEMENT
- RISING DEMAND FOR LOW-CODE AUTOMATION PLATFORMS IS ENABLING FASTER ENTERPRISE AUTOMATION DEVELOPMENT
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- PESTLE ANALYSIS
- POLITICAL
- ECONOMIC
- SOCIAL LANDSCAPE
- TECHNOLOGY
- LEGAL
- ENVIRONMENTAL
- GROWTH OPPORTUNITY MAPPING & HEATMAP
- GROWTH PROSPECT MAPPING FOR AUSTRALIA
- MARKET MATURITY & LIFECYCLE ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- GROWTH METRICS
AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS VALUE CHAIN & DECISION FRAMEWORK
- VALUE CHAIN ANALYSIS
- AI MODEL DEVELOPMENT
- RPA PLATFORM DEVELOPMENT
- SYSTEM INTEGRATION SERVICES
- BOT DEPLOYMENT MANAGEMENT
- PROCESS MONITORING ANALYTICS
- ENTERPRISE SUPPORT SERVICES
- KEY BUYING CRITERIA
- AUTOMATION SCALABILITY
- AI INTEGRATION CAPABILITY
- DEPLOYMENT FLEXIBILITY
- ENTERPRISE SECURITY COMPLIANCE
- PRICING MODELS, LICENSING STRUCTURES & COST OPTIMIZATION STRATEGIES
- REGULATORY & POLICY LANDSCAPE ANALYSIS
- VALUE CHAIN ANALYSIS
AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET BY AUTONOMY LEVEL
- SEMI-AUTONOMOUS RPA BOTS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- FULLY AUTONOMOUS RPA BOTS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SEMI-AUTONOMOUS RPA BOTS
AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET BY CAPABILITY TYPE
- SELF-HEALING AUTOMATION
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SELF-LEARNING AUTOMATION
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- DECISION-AWARE AUTOMATION
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ADAPTIVE WORKFLOW AUTOMATION
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SELF-HEALING AUTOMATION
AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET BY DEPLOYMENT MODEL
- CLOUD-BASED
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ON-PREMISE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- HYBRID
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- CLOUD-BASED
AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET BY ENTERPRISE SIZE
- LARGE ENTERPRISES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SMES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- LARGE ENTERPRISES
AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET BY INDUSTRY VERTICAL
- BFSI
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- HEALTHCARE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- TELECOM
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- RETAIL & E-COMMERCE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- MANUFACTURING
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- GOVERNMENT & PUBLIC SECTOR
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- BFSI
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPETITOR POSITIONING & DIFFERENTIATION MAP
- COMPANY PROFILES
- UIPATH INC
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- AUTOMATION ANYWHERE INC
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- SS&C BLUE PRISM LIMITED
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- MICROSOFT CORPORATION
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- PEGASYSTEMS INC
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- NICE LTD
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- IBM CORPORATION
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- SAP SE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- TUNGSTEN AUTOMATION
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- APPIAN CORPORATION
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- UIPATH INC
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS
TABLE 2: PRICING MODELS, LICENSING STRUCTURES & COST OPTIMIZATION STRATEGIES FOR AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS
TABLE 3: REGULATORY & POLICY LANDSCAPE ANALYSIS
TABLE 4: MARKET BY AUTONOMY LEVEL, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 5: MARKET BY AUTONOMY LEVEL, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 6: MARKET BY CAPABILITY TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 7: MARKET BY CAPABILITY TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 8: MARKET BY DEPLOYMENT MODEL, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 9: MARKET BY DEPLOYMENT MODEL, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 10: MARKET BY ENTERPRISE SIZE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 11: MARKET BY ENTERPRISE SIZE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 12: MARKET BY INDUSTRY VERTICAL, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 13: MARKET BY INDUSTRY VERTICAL, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 14: KEY PLAYERS OPERATING IN THE AUSTRALIAN MARKET
TABLE 15: LIST OF MERGERS & ACQUISITIONS
TABLE 16: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 17: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 18: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR AUSTRALIA
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY AUTONOMY LEVEL, IN 2025
FIGURE 11: SEMI-AUTONOMOUS RPA BOTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: FULLY AUTONOMOUS RPA BOTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY CAPABILITY TYPE, IN 2025
FIGURE 14: SELF-HEALING AUTOMATION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: SELF-LEARNING AUTOMATION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: DECISION-AWARE AUTOMATION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: ADAPTIVE WORKFLOW AUTOMATION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: SEGMENT GROWTH POTENTIAL, BY DEPLOYMENT MODEL, IN 2025
FIGURE 19: CLOUD-BASED MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: ON-PREMISE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: HYBRID MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: SEGMENT GROWTH POTENTIAL, BY ENTERPRISE SIZE, IN 2025
FIGURE 23: LARGE ENTERPRISES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: SMES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: SEGMENT GROWTH POTENTIAL, BY INDUSTRY VERTICAL, IN 2025
FIGURE 26: BFSI MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: HEALTHCARE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: TELECOM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 29: RETAIL & E-COMMERCE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: MANUFACTURING MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: GOVERNMENT & PUBLIC SECTOR MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
JAPAN AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
INDIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
CHINA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034