
CANADA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET FORECAST 2026-2034
SCOPE OF THE REPORT
Canada Autonomous Robotic Process Automation (RPA) Bots Market by Autonomy Level (Semi-Autonomous RPA Bots, Fully Autonomous RPA Bots) Market by Capability Type (Self-Healing Automation, Self-Learning Automation, Decision-Aware Automation, Adaptive Workflow Automation) Market by Deployment Model (Cloud-Based, On-Premise, Hybrid) Market by Enterprise Size (Large Enterprises, SMEs) Market by Industry Vertical (BFSI, Healthcare, Telecom, Retail & E-Commerce, Manufacturing, Government & Public Sector)
REPORTS » REGIONAL REPORTS » COUNTRY » CANADA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET FORECAST 2026-2034
CANADA AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET OVERVIEW
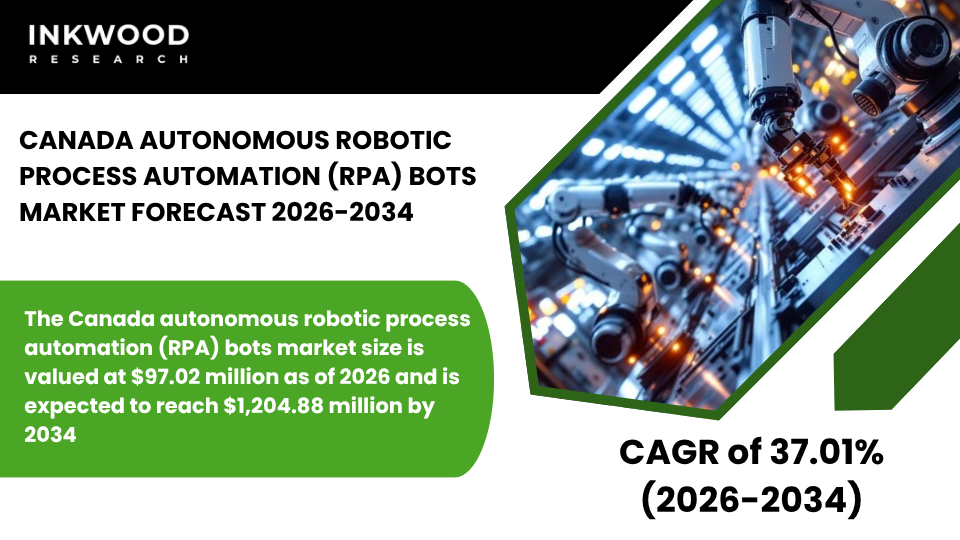
The Canada autonomous robotic process automation (RPA) bots market size is valued at $97.02 million as of 2026 and is expected to reach $1,204.88 million by 2034, progressing with a CAGR of 37.01% during the forecast years, 2026–2034.
MARKET INSIGHTS
Canada is rapidly establishing itself as a high-growth market for autonomous robotic process automation (RPA) bots, supported by a strong national commitment to digital transformation, a well-developed cloud computing ecosystem, and persistent enterprise demand for cost efficiency across its largest industries. Canadian organizations in BFSI, healthcare, telecom, and the public sector are actively accelerating their investments in intelligent RPA bots, moving beyond isolated automation pilots toward enterprise-wide autonomous digital workforce strategies.
This momentum is further reinforced by Canada’s thriving AI research ecosystem, anchored by globally recognized institutions such as the Vector Institute for Artificial Intelligence in Toronto and Mila in Montreal, which are generating practical AI capabilities that are increasingly being embedded into next-generation RPA automation platforms deployed by Canadian enterprises.
Government policy is a particularly influential force shaping the trajectory of the Canada autonomous robotic process automation (RPA) bots market. The Government of Canada’s Digital Ambition, published by the Treasury Board Secretariat, outlines a clear mandate to modernize federal public services through digital technologies, including automation and AI-powered workflow management.
At the provincial level, digital service transformation programs in Ontario, British Columbia, and Quebec are directing procurement toward enterprise automation bots that can streamline citizen-facing services, reduce administrative backlogs, and improve processing accuracy. On the regulatory side, Canada’s Personal Information Protection and Electronic Documents Act (PIPEDA) and the proposed Bill C-27 (Consumer Privacy Protection Act) are prompting enterprises to deploy governed, auditable autonomous RPA solutions that can process sensitive data within clearly defined compliance boundaries, creating a strong structural incentive for responsible automation adoption across regulated sectors.
Canada’s labor market dynamics add yet another layer of urgency to autonomous RPA adoption. According to Statistics Canada, the country faces ongoing skilled labor shortages across financial services, healthcare, and IT sectors, making the case for autonomous digital workforce automation increasingly compelling for organizations seeking to maintain service quality without proportionally expanding headcount.
The country’s well-established cloud infrastructure, including major regional data center investments by AWS, Microsoft Azure, and Google Cloud in Toronto, Montreal, and Vancouver, is further enabling scalable, low-latency deployment of AI-powered RPA bots across enterprise environments. As organizations continue to mature in their automation journeys and as AI-driven RPA capabilities become more accessible through low-code platforms, these factors are collectively set to sustain strong and accelerating growth in the Canada autonomous robotic process automation (RPA) bots market throughout the forecast period.
To Know More About This Report, Request a Free Sample Copy
SEGMENTATION ANALYSIS
The Canada autonomous robotic process automation (RPA) bots market is segmented by autonomy level, capability type, deployment model, enterprise size, and industry vertical. The deployment model segment is further categorized into cloud-based, on-premise, and hybrid.
The cloud-based sub-segment holds a commanding and growing share of the Canada autonomous robotic process automation (RPA) bots market, driven by the country’s mature public cloud infrastructure and the strong preference among Canadian enterprises for scalable, subscription-based automation architectures. Cloud-based deployment allows organizations to rapidly provision intelligent RPA bots, integrate them with existing SaaS enterprise applications, and scale bot capacity in line with fluctuating process volumes, all without the capital burden of on-premise hardware.
This model is particularly attractive to Canadian financial institutions, healthcare networks, and mid-sized enterprises that require agile, cost-efficient autonomous RPA solutions with built-in disaster recovery and geographic redundancy. Furthermore, the Canadian Centre for Cyber Security, operating under the Communications Security Establishment, has published cloud security guidance that provides enterprises with a compliance-aligned framework for deploying cloud-hosted automation workloads.
This plays a vital role in reducing a key barrier that previously caused hesitation around cloud-based autonomous RPA adoption. For vendors, the cloud-based segment represents the most accessible and highest-velocity growth opportunity in the Canadian market, particularly for those offering pre-integrated, industry-specific bot libraries and flexible consumption-based pricing models tailored to enterprise automation buyers.
COMPETITIVE INSIGHTS
Some of the top players operating in the Canada autonomous robotic process automation (RPA) bots market include UiPath Inc, Microsoft Corporation, IBM Corporation, Automation Anywhere Inc, etc.
IBM Corporation is a New York-headquartered global technology and consulting company with a significant and long-standing presence in the Canadian enterprise market. IBM offers a comprehensive portfolio of AI-powered RPA bots and intelligent automation solutions through its IBM Watson Orchestrate and IBM Robotic Process Automation platforms, enabling Canadian organizations to automate complex, data-intensive workflows across BFSI, healthcare, and government sectors. With an extensive network of Canadian offices, delivery centers, and enterprise client relationships built over decades, IBM is well-positioned to support large-scale autonomous RPA deployments that require deep systems integration, regulatory compliance capabilities, and end-to-end automation governance.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Autonomy Level, Capability Type, Deployment Model, Enterprise Size, Industry Vertical |
| Country Analyzed | Canada |
| Companies Analyzed | UiPath Inc, Automation Anywhere Inc, Microsoft Corporation, Pegasystems Inc, IBM Corporation, SAP SE, Tungsten Automation |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE, SHARE & ESTIMATES
- MARKET OVERVIEW
- SCOPE OF STUDY
- MAJOR MARKET FINDINGS
- CANADIAN ENTERPRISES ARE RAPIDLY ADOPTING AUTONOMOUS RPA BOTS TO IMPROVE OPERATIONAL EFFICIENCY AND REDUCE MANUAL PROCESS DEPENDENCY
- THE BFSI, HEALTHCARE, AND PUBLIC SECTOR INDUSTRIES ARE LEADING IMPLEMENTATION OF AUTONOMOUS AUTOMATION SOLUTIONS
- ORGANIZATIONS ARE INTEGRATING AI AND MACHINE LEARNING WITH RPA TO ENABLE INTELLIGENT DECISION-MAKING CAPABILITIES
- CANADA IS EXPERIENCING INCREASED INVESTMENT IN DIGITAL WORKFORCE MANAGEMENT AND ENTERPRISE AUTOMATION PLATFORMS
MARKET DYNAMICS
- KEY DRIVERS
- STRONG DIGITAL TRANSFORMATION INITIATIVES ACROSS ENTERPRISES ARE DRIVING DEMAND FOR AUTONOMOUS BUSINESS PROCESS AUTOMATION
- HIGH DEMAND FOR COST REDUCTION AND PRODUCTIVITY IMPROVEMENTS IS ENCOURAGING ENTERPRISE INVESTMENT IN INTELLIGENT AUTOMATION
- EXPANSION OF CLOUD COMPUTING INFRASTRUCTURE IS ENABLING SCALABLE DEPLOYMENT OF AUTONOMOUS RPA SOLUTIONS
- GROWING NEED FOR REGULATORY COMPLIANCE AUTOMATION IN BFSI AND HEALTHCARE IS ACCELERATING MARKET GROWTH
- KEY RESTRAINTS
- HIGH IMPLEMENTATION COSTS AND LIMITED TECHNICAL EXPERTISE IN SMALL ENTERPRISES SLOW DOWN RPA ADOPTION
- DATA PRIVACY REGULATIONS AND CYBERSECURITY CONCERNS CREATE CHALLENGES FOR AUTONOMOUS AUTOMATION DEPLOYMENTS
- ENTERPRISE INTEGRATION COMPLEXITIES WITH EXISTING SOFTWARE INFRASTRUCTURE LIMIT FULL-SCALE IMPLEMENTATION
- ORGANIZATIONAL CHANGE MANAGEMENT AND WORKFORCE ADAPTATION REQUIREMENTS RESTRAIN AUTOMATION TRANSFORMATION
- KEY DRIVERS
STRATEGIC MARKET ANALYTICS
- GROWTH METRICS
- TAM, SAM & SOM OPPORTUNITY ANALYSIS
- EMERGING MARKET TRENDS & PARADIGM SHIFTS
- ENTERPRISES ARE ADOPTING HYPERAUTOMATION STRATEGIES THAT COMBINE RPA WITH AI, PROCESS MINING, AND ADVANCED ANALYTICS
- INCREASING USE OF AUTONOMOUS RPA BOTS IN FINANCIAL OPERATIONS, CLAIM PROCESSING, AND CUSTOMER SERVICE AUTOMATION
- CANADIAN ORGANIZATIONS ARE DEVELOPING DIGITAL WORKFORCE GOVERNANCE MODELS TO MANAGE AUTONOMOUS BOT ECOSYSTEMS
- GROWING DEMAND FOR LOW-CODE AND NO-CODE AUTOMATION PLATFORMS IS EXPANDING ACCESS TO AUTONOMOUS RPA TECHNOLOGIES
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- PESTLE ANALYSIS
- POLITICAL
- ECONOMIC
- SOCIAL LANDSCAPE
- TECHNOLOGY
- LEGAL
- ENVIRONMENTAL
- GROWTH OPPORTUNITY MAPPING & HEATMAP
- GROWTH PROSPECT MAPPING FOR CANADA
- MARKET MATURITY & LIFECYCLE ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- GROWTH METRICS
AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS VALUE CHAIN & DECISION FRAMEWORK
- VALUE CHAIN ANALYSIS
- AI MODEL DEVELOPMENT
- RPA PLATFORM DEVELOPMENT
- SYSTEM INTEGRATION SERVICES
- BOT DEPLOYMENT MANAGEMENT
- PROCESS MONITORING ANALYTICS
- ENTERPRISE SUPPORT SERVICES
- KEY BUYING CRITERIA
- AUTOMATION SCALABILITY
- AI INTEGRATION CAPABILITY
- DEPLOYMENT FLEXIBILITY
- ENTERPRISE SECURITY COMPLIANCE
- PRICING MODELS, LICENSING STRUCTURES & COST OPTIMIZATION STRATEGIES
- REGULATORY & POLICY LANDSCAPE ANALYSIS
- VALUE CHAIN ANALYSIS
AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET BY AUTONOMY LEVEL
- SEMI-AUTONOMOUS RPA BOTS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- FULLY AUTONOMOUS RPA BOTS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SEMI-AUTONOMOUS RPA BOTS
AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET BY CAPABILITY TYPE
- SELF-HEALING AUTOMATION
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SELF-LEARNING AUTOMATION
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- DECISION-AWARE AUTOMATION
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ADAPTIVE WORKFLOW AUTOMATION
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SELF-HEALING AUTOMATION
AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET BY DEPLOYMENT MODEL
- CLOUD-BASED
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ON-PREMISE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- HYBRID
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- CLOUD-BASED
AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET BY ENTERPRISE SIZE
- LARGE ENTERPRISES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SMES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- LARGE ENTERPRISES
AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS MARKET BY INDUSTRY VERTICAL
- BFSI
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- HEALTHCARE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- TELECOM
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- RETAIL & E-COMMERCE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- MANUFACTURING
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- GOVERNMENT & PUBLIC SECTOR
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- BFSI
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPETITOR POSITIONING & DIFFERENTIATION MAP
- COMPANY PROFILES
- UIPATH INC
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- AUTOMATION ANYWHERE INC
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- MICROSOFT CORPORATION
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- PEGASYSTEMS INC
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- IBM CORPORATION
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- SAP SE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- TUNGSTEN AUTOMATION
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- UIPATH INC
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS
TABLE 2: PRICING MODELS, LICENSING STRUCTURES & COST OPTIMIZATION STRATEGIES FOR AUTONOMOUS ROBOTIC PROCESS AUTOMATION (RPA) BOTS
TABLE 3: REGULATORY & POLICY LANDSCAPE ANALYSIS
TABLE 4: MARKET BY AUTONOMY LEVEL, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 5: MARKET BY AUTONOMY LEVEL, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 6: MARKET BY CAPABILITY TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 7: MARKET BY CAPABILITY TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 8: MARKET BY DEPLOYMENT MODEL, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 9: MARKET BY DEPLOYMENT MODEL, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 10: MARKET BY ENTERPRISE SIZE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 11: MARKET BY ENTERPRISE SIZE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 12: MARKET BY INDUSTRY VERTICAL, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 13: MARKET BY INDUSTRY VERTICAL, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 14: KEY PLAYERS OPERATING IN THE CANADIAN MARKET
TABLE 15: LIST OF MERGERS & ACQUISITIONS
TABLE 16: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 17: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 18: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR CANADA
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY AUTONOMY LEVEL, IN 2025
FIGURE 11: SEMI-AUTONOMOUS RPA BOTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: FULLY AUTONOMOUS RPA BOTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY CAPABILITY TYPE, IN 2025
FIGURE 14: SELF-HEALING AUTOMATION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: SELF-LEARNING AUTOMATION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: DECISION-AWARE AUTOMATION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: ADAPTIVE WORKFLOW AUTOMATION MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: SEGMENT GROWTH POTENTIAL, BY DEPLOYMENT MODEL, IN 2025
FIGURE 19: CLOUD-BASED MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: ON-PREMISE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: HYBRID MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: SEGMENT GROWTH POTENTIAL, BY ENTERPRISE SIZE, IN 2025
FIGURE 23: LARGE ENTERPRISES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: SMES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: SEGMENT GROWTH POTENTIAL, BY INDUSTRY VERTICAL, IN 2025
FIGURE 26: BFSI MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: HEALTHCARE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: TELECOM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 29: RETAIL & E-COMMERCE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: MANUFACTURING MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: GOVERNMENT & PUBLIC SECTOR MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
JAPAN AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
INDIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-
CHINA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034