Vietnam Cardiovascular Ultrasound Market by Device Display (Color Display Systems, Black & White (B/W) Display Systems) Market by Technology (2D Ultrasound, 3D & 4D Ultrasound, Doppler Imaging) Market by Application (Diagnostic Applications, Therapeutic Applications) Market by Type (Transthoracic Echocardiogram, Transesophageal Echocardiogram, Stress Echocardiogram, Fetal Echocardiography, Other Types) Market by End-User (Hospitals, Diagnostic Centers, Ambulatory Care Centers, Other End-Users), by Geography
VIETNAM CARDIOVASCULAR ULTRASOUND MARKET OVERVIEW
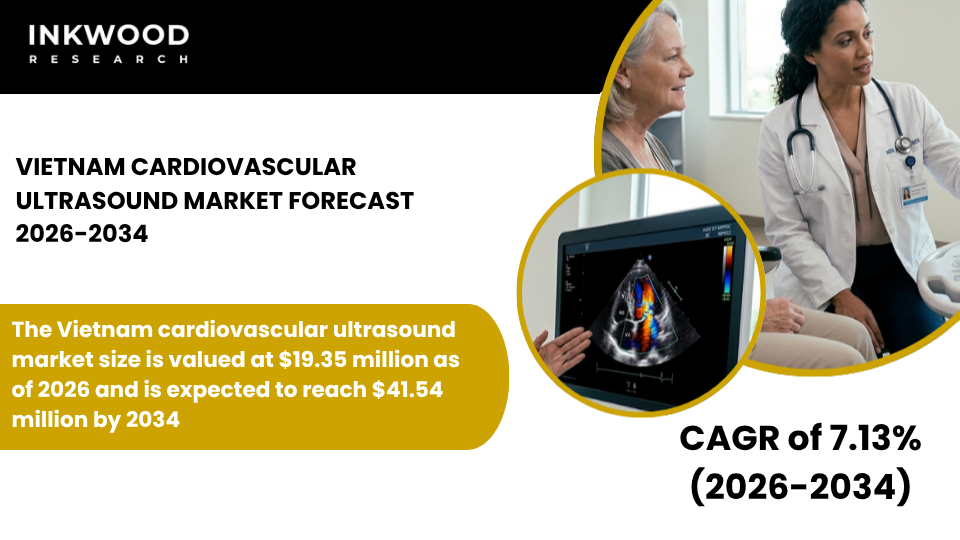
The Vietnam cardiovascular ultrasound market size is valued at $19.35 million as of 2026 and is expected to reach $41.54 million by 2034, progressing with a CAGR of 10.02% during the forecast years, 2026–2034.
Vietnam is one of Southeast Asia’s most compelling growth markets for cardiovascular ultrasound. It is driven by a worsening cardiovascular disease burden, rapid urbanization, expanding health insurance coverage, and a healthcare system undergoing meaningful structural reform. Cardiovascular disease is the leading cause of death in the country. According to the Vietnam Ministry of Health, approximately 200,000 people die from cardiovascular conditions annually, accounting for 33% of all deaths.
A report published citing Ministry of Health data further confirms that cardiovascular diseases lead all non-communicable diseases in Vietnam, contributing 20.5% of the total national disease burden. Hypertension alone affects approximately 25% of the adult population, one in four adults. This creates a persistent and large demand base for non-invasive cardiac diagnostic procedures, including the transthoracic echocardiogram, across Vietnam’s hospital and diagnostic center network.
Beyond disease burden, Vietnam’s healthcare policy environment is strongly supportive of market growth. The country has made remarkable progress on health insurance coverage; 91.1 million people, approximately 92% of the population, had health insurance coverage in 2023. This figure rose further to 93.4% in 2024, as reported by Vietnam Social Security, covering nearly 13,000 public and private health facilities.
To Know More About This Report, Request a Free Sample Copy
In November 2024, Vietnam’s National Assembly passed Law No. 51/2024/QH15, amending the Law on Health Insurance, effective July 2025. The reform eliminated administrative boundary restrictions on healthcare registration, expanded covered services, including telehealth and home-based care, and broadened access to cardiac and specialist services without requiring referrals for certain conditions. Together, these policy actions are directly expanding the insured patient base for cardiac diagnostic procedures and reinforcing hospital procurement of cardiovascular ultrasound systems.
Vietnam’s healthcare infrastructure is also expanding rapidly. As of 2024, the country operates 1,645 hospitals, including 384 private facilities, serving over 170 million outpatient visits and 17 million inpatient treatments annually, according to US-ASEAN Business Council data. However, high-quality cardiac imaging remains concentrated in major urban hospitals in Hanoi and Ho Chi Minh City. This creates a significant untapped opportunity.
Government-led healthcare decentralization and growing private hospital investment in secondary cities are gradually broadening access to advanced cardiac imaging, including 3D and 4D echocardiography, beyond the urban centers. For vendors in the cardiovascular imaging market, Vietnam represents a market where near-term volume growth, longer-term infrastructure investment, and favorable policy tailwinds converge into a strong and durable commercial opportunity.
The Vietnam cardiovascular ultrasound market is segmented by device display, technology, application, type, and end-user. The device display segment is further categorized into color display systems and black & white (B/W) display systems.
Color display systems hold the dominant share within the device display segment of the Vietnam cardiovascular ultrasound market. Their position reflects both clinical necessity and the broader direction of cardiac ultrasound technology adoption in the country. Color display systems enable real-time visualization of blood flow, cardiac chamber dynamics, and vascular structures with the color-coded precision that is essential for Doppler-based cardiac assessments.
This capability is central to diagnosing valvular disease, detecting intracardiac shunts, and assessing hemodynamic function, procedures that are performed daily in Vietnam’s hospital cardiology departments and increasingly in its growing network of diagnostic centers. As Vietnam’s hospitals invest in upgrading their imaging fleets, particularly in Hanoi, Ho Chi Minh City, and expanding secondary city centers, color display cardiovascular ultrasound systems are the standard procurement choice. They offer a materially better clinical experience and diagnostic output than older B/W units.
Moreover, the growing adoption of AI-assisted echocardiography tools and automated workflow features is available almost exclusively in color display platforms, further reinforcing their dominance. For vendors operating in the Vietnam cardiovascular imaging market, color display systems represent the highest-volume, highest-value procurement category, and the natural upgrade path as Vietnam’s public and private hospitals modernize their cardiac diagnostic infrastructure over the forecast period.
Some of the top players operating in the Vietnam cardiovascular ultrasound market include GE HealthCare, Koninklijke Philips NV, Siemens Healthineers AG, Canon Medical Systems Corporation, Mindray Medical International Limited, etc.
GE HealthCare is a Chicago, United States-headquartered medical technology company and one of the most established international players in Vietnam’s cardiovascular ultrasound market. Its cardiac ultrasound portfolio spans premium console-based systems to compact point-of-care platforms, all designed to support the full spectrum of echocardiographic procedures across diverse clinical environments. In 2024, GE HealthCare launched the Vscan Air SL, a wireless, pocket-sized dual-probe ultrasound system, and expanded its Venue family of point-of-care ultrasound platforms with AI-assisted cardiac tools.
These compact, AI-enabled platforms are particularly well-suited to Vietnam’s healthcare landscape, where demand is growing for portable cardiac imaging systems that can extend diagnostic reach beyond large urban hospitals into district-level facilities. GE HealthCare’s broad distribution network, established service infrastructure, and longstanding relationships with Vietnam’s public hospital system give it a strong competitive position in the country’s evolving cardiovascular ultrasound market.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Device Display, Technology, Type, End-User |
| Country Analyzed | Vietnam |
| Companies Analyzed | Canon Medical Systems Corporation, FUJIFILM Holdings Corporation, GE Healthcare, Koninklijke Philips NV, Mindray Medical International Limited, Samsung Medison Co Ltd, Siemens Healthineers AG, Zonare Medical Systems (part of Mindray) |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- VIETNAM IS EMERGING AS A HIGH-GROWTH MARKET FOR CARDIOVASCULAR ULTRASOUND IN SOUTHEAST ASIA
- URBAN HOSPITALS ACCOUNT FOR THE MAJORITY OF ADVANCED CARDIAC IMAGING INSTALLATIONS
- IMPORTS DOMINATE THE MARKET WITH LIMITED LOCAL MANUFACTURING CAPABILITIES
- PUBLIC HOSPITALS REPRESENT A SIGNIFICANT SHARE OF TOTAL PROCEDURE VOLUMES
MARKET DYNAMICS
- KEY DRIVERS
- INCREASING PREVALENCE OF CARDIOVASCULAR DISEASES DUE TO LIFESTYLE TRANSITIONS IS DRIVING DIAGNOSTIC NEEDS
- GOVERNMENT HEALTHCARE REFORMS ARE IMPROVING ACCESS TO ADVANCED DIAGNOSTIC EQUIPMENT
- RISING HEALTHCARE EXPENDITURE AND EXPANSION OF PRIVATE HOSPITALS ARE SUPPORTING MARKET GROWTH
- GROWING MEDICAL TOURISM IS BOOSTING DEMAND FOR HIGH QUALITY CARDIAC IMAGING SERVICES
- KEY RESTRAINTS
- BUDGET CONSTRAINTS IN PUBLIC HEALTHCARE FACILITIES LIMIT THE PROCUREMENT OF PREMIUM SYSTEMS
- DEPENDENCE ON IMPORTED EQUIPMENT INCREASES COST SENSITIVITY
- LIMITED AVAILABILITY OF SPECIALIZED CARDIAC SONOGRAPHERS AFFECTS SERVICE QUALITY
- REGULATORY AND PROCUREMENT COMPLEXITIES CAN DELAY EQUIPMENT INSTALLATION
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- RISING DEMAND FOR PORTABLE AND MID-RANGE ULTRASOUND SYSTEMS
- INCREASED FOCUS ON TRAINING PROGRAMS TO IMPROVE CARDIAC IMAGING CAPABILITIES
- GRADUAL ADOPTION OF ADVANCED 3D AND 4D ECHOCARDIOGRAPHY TECHNOLOGIES
- COLLABORATIONS BETWEEN PUBLIC HOSPITALS AND INTERNATIONAL EQUIPMENT SUPPLIERS
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR VIETNAM
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SUPPLIERS
- COMPONENT MANUFACTURERS
- SYSTEM INTEGRATORS
- DEVICE MANUFACTURERS
- DISTRIBUTION CHANNELS
- HEALTHCARE PROVIDERS
- AFTER SALES SERVICES
- KEY BUYING CRITERIA
- IMAGE RESOLUTION
- PORTABILITY FEATURES
- TOTAL COST OWNERSHIP
- SERVICE SUPPORT AVAILABILITY
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
CARDIOVASCULAR ULTRASOUND MARKET BY DEVICE DISPLAY
- COLOR DISPLAY SYSTEMS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- BLACK & WHITE (B/W) DISPLAY SYSTEMS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- COLOR DISPLAY SYSTEMS
CARDIOVASCULAR ULTRASOUND MARKET BY TECHNOLOGY
- 2D ULTRASOUND
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- 3D & 4D ULTRASOUND
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DOPPLER IMAGING
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- 2D ULTRASOUND
CARDIOVASCULAR ULTRASOUND MARKET BY APPLICATION
- DIAGNOSTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- THERAPEUTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DIAGNOSTIC APPLICATIONS
CARDIOVASCULAR ULTRASOUND MARKET BY TYPE
- TRANSTHORACIC ECHOCARDIOGRAM
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- TRANSESOPHAGEAL ECHOCARDIOGRAM
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- STRESS ECHOCARDIOGRAM
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- FETAL ECHOCARDIOGRAPHY
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- OTHER TYPES
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- TRANSTHORACIC ECHOCARDIOGRAM
CARDIOVASCULAR ULTRASOUND MARKET BY END-USER
- HOSPITALS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DIAGNOSTIC CENTERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- AMBULATORY CARE CENTERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- OTHER END-USERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- HOSPITALS
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- CANON MEDICAL SYSTEMS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- FUJIFILM HOLDINGS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GE HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- KONINKLIJKE PHILIPS NV
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- MINDRAY MEDICAL INTERNATIONAL LIMITED
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SAMSUNG MEDISON CO LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SIEMENS HEALTHINEERS AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ZONARE MEDICAL SYSTEMS (PART OF MINDRAY)
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- CANON MEDICAL SYSTEMS CORPORATION
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – CARDIOVASCULAR ULTRASOUND
TABLE 2: CARDIOVASCULAR ULTRASOUND MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY DEVICE DISPLAY, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY DEVICE DISPLAY, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: MARKET BY TECHNOLOGY, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: MARKET BY TECHNOLOGY, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: MARKET BY TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: MARKET BY TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: MARKET BY END-USER, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: MARKET BY END-USER, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: KEY PLAYERS OPERATING IN THE VIETNAMESE MARKET
TABLE 12: LIST OF MERGERS & ACQUISITIONS
TABLE 13: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 14: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 15: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR VIETNAM
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY DEVICE DISPLAY, IN 2025
FIGURE 11: COLOR DISPLAY SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: BLACK & WHITE (B/W) DISPLAY SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY TECHNOLOGY, IN 2025
FIGURE 14: 2D ULTRASOUND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: 3D & 4D ULTRASOUND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: DOPPLER IMAGING MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: SEGMENT GROWTH POTENTIAL, BY TYPE, IN 2025
FIGURE 18: TRANSTHORACIC ECHOCARDIOGRAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: TRANSESOPHAGEAL ECHOCARDIOGRAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: STRESS ECHOCARDIOGRAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: FETAL ECHOCARDIOGRAPHY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: OTHER TYPES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: SEGMENT GROWTH POTENTIAL, BY END-USER, IN 2025
FIGURE 24: HOSPITALS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: DIAGNOSTIC CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: AMBULATORY CARE CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: OTHER END-USERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
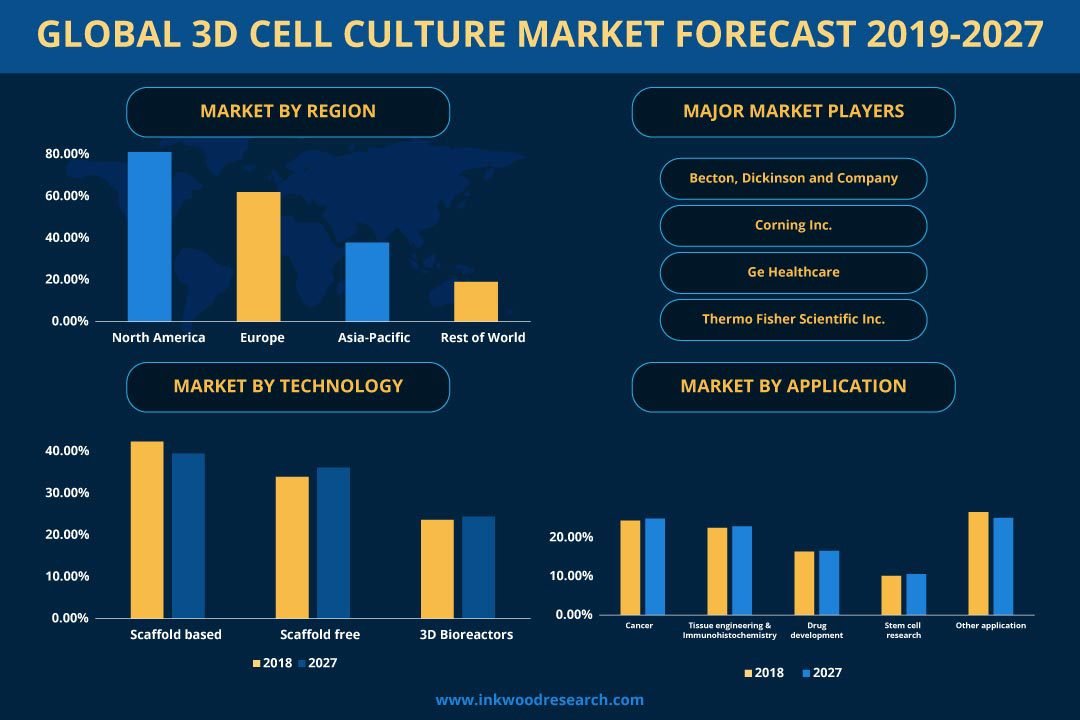
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
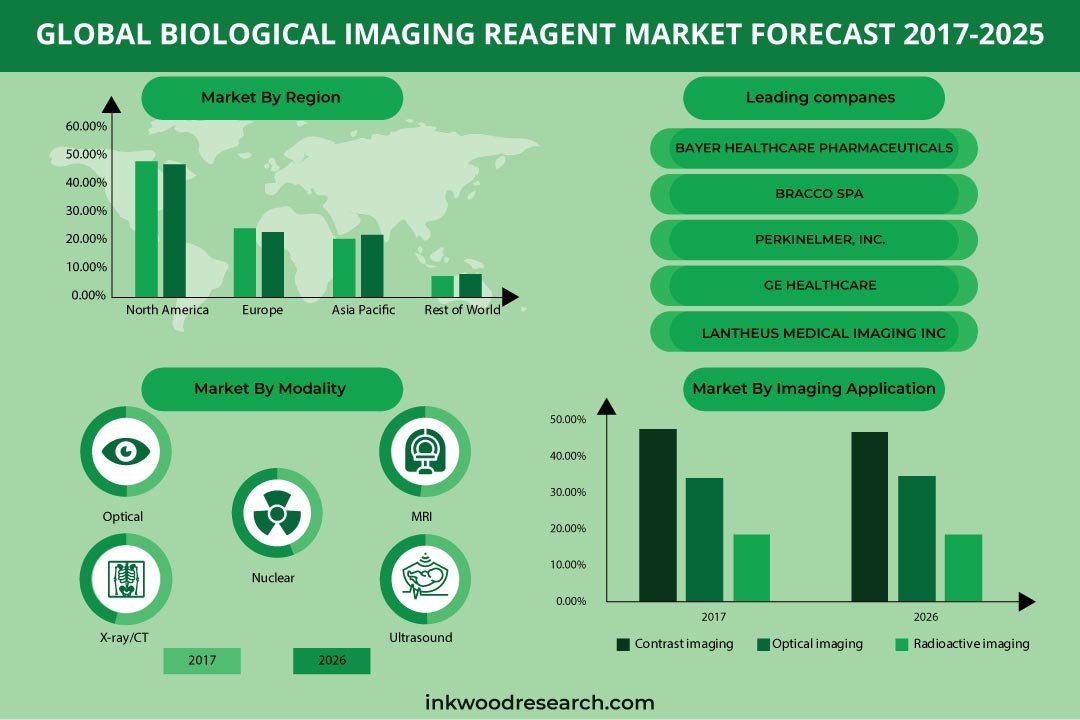
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034