United Arab Emirates (UAE) Magnetic Resonance Imaging (MRI) Systems Market by Architecture (Closed MRI Systems, Open MRI Systems) Market by Field Type (High Field System, Low-Mid Field Systems, Ultra High Field Systems) Market by Application (Brain and Neurology MRI System, Spine and Musculoskeletal MRI System, Pelvic and Abdominal MRI System, Oncology MRI System, Vascular MRI System, Cardiology MRI System, Pediatric MRI System, Gastroenterology MRI System, Other Applications), and Geography
UNITED ARAB EMIRATES (UAE) MAGNETIC RESONANCE IMAGING (MRI) SYSTEMS MARKET OVERVIEW
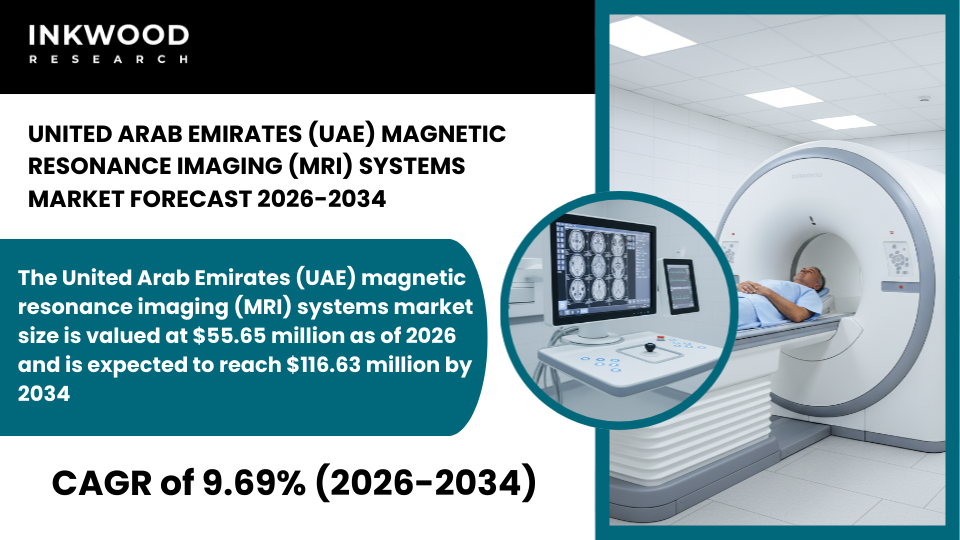
The United Arab Emirates (UAE) magnetic resonance imaging (MRI) systems market size is valued at $55.65 million as of 2026 and is expected to reach $116.63 million by 2034, progressing with a CAGR of 9.69% during the forecast years, 2026-2034.
The UAE’s ambitious healthcare transformation agenda, combined with substantial government investments, positions the country as a rapidly expanding MRI systems market regionally. The Ministry of Health and Prevention (MOHAP) regulates medical device safety and efficacy through comprehensive registration requirements aligned with international standards.
Strong demand from private hospitals and specialty clinics characterizes the market landscape, driven by affluent patient populations seeking world-class healthcare services. Moreover, the UAE’s strategic focus on medical tourism attracts international patients from across the Middle East, Africa, and South Asia seeking advanced diagnostic imaging capabilities.
High adoption rates for premium and high-field MRI systems reflect the country’s commitment to delivering cutting-edge healthcare comparable to developed nations. Furthermore, rapid technology adoption cycles and shorter equipment replacement intervals distinguish the UAE market from more conservative regional counterparts.
Government healthcare infrastructure investments expand diagnostic capacity across Abu Dhabi, Dubai, and other emirates through new hospital construction and facility modernization programs. Additionally, the growing expatriate population, combined with rising lifestyle-related disease prevalence, increases demand for comprehensive diagnostic imaging services.
To Know More About This Report, Request a Free Sample Copy
The UAE healthcare system operates through a mixed public-private model with varying regulatory frameworks across different emirates. Abu Dhabi’s Department of Health oversees healthcare regulation within that emirate, while Dubai Health Authority (DHA) manages Dubai’s healthcare sector independently. Private healthcare providers dominate the MRI systems market, operating premium facilities targeting affluent Emirati nationals and expatriate professionals.
These private hospitals invest aggressively in the latest imaging technologies to differentiate their services within highly competitive markets. Moreover, international hospital chains, including Cleveland Clinic, King’s College Hospital, and Moorfields Eye Hospital, establish specialized facilities throughout the UAE. Medical device registration requires manufacturers to appoint UAE-based authorized representatives managing regulatory submissions and post-market compliance activities.
Furthermore, ISO 13485 certification demonstrates quality management system compliance as expected by MOHAP for device registration approvals. Foreign manufacturers must obtain certificates of free sale from their home countries, verified through the UAE embassy attestation processes.
Additionally, device classification follows Global Harmonization Task Force (GHTF) guidelines, categorizing products based on risk levels from Class I through Class IV. Registration timelines typically extend 45 working days following complete application submission with supporting documentation. Consequently, manufacturers prioritize regulatory preparation, ensuring smooth approval processes and timely market entry.
The United Arab Emirates magnetic resonance imaging (MRI) systems market is segmented into architecture, field type, and application. The architecture segment is further categorized into closed MRI systems and open MRI systems.
Wide bore MRI systems, under the closed MRI systems category, demonstrate strong market penetration throughout the UAE, addressing patient comfort concerns and accommodating diverse demographics. These systems featuring 70-centimeter apertures provide superior patient experiences compared to traditional 60-centimeter standard bore configurations.
UAE healthcare providers recognize that patient satisfaction directly impacts facility reputation and competitive positioning within crowded metropolitan markets. Moreover, the expatriate population, representing over 80% of UAE residents, includes individuals from diverse ethnic backgrounds with varying body types. Wide bore architectures accommodate larger patients comfortably while reducing claustrophobia-related examination cancellations significantly.
Private hospitals emphasize luxury amenities and premium patient experiences as core value propositions, justifying premium pricing strategies. Furthermore, wide bore systems enable advanced imaging protocols, including cardiac studies and abdominal examinations requiring patient breathing instructions and positioning flexibility. Pediatric applications particularly benefit from wide bore designs, allowing parental presence during examinations, reducing child anxiety substantially.
Additionally, wide bore MRI systems support higher weight capacities essential for bariatric patient populations requiring diagnostic imaging services. The systems maintain diagnostic image quality equivalent to standard bore platforms through advanced gradient and radiofrequency coil technologies. Consequently, wide-bore magnetic resonance imaging systems represent strategic investments for UAE healthcare providers prioritizing patient-centric service delivery models.
Some of the top players operating in the United Arab Emirates magnetic resonance imaging (MRI) systems market include GE Healthcare, Siemens Healthineers, Philips Healthcare, Canon Medical Systems Corp, Fujifilm Holdings Corporation, Fonar Corporation, etc.
Fonar Corporation operates as a pioneering American medical technology company headquartered in Melville, New York, specializing in upright and open MRI system manufacturing. The company revolutionized magnetic resonance imaging by developing the first commercial MRI scanner and subsequently introducing the world’s first upright multi-position MRI system.
Fonar’s Upright Multi-Position MRI enables patients to be scanned standing, sitting, or in various positions impossible with conventional horizontal systems. This unique capability provides diagnostic insights into weight-bearing spinal conditions and dynamic joint pathology unattainable through traditional MRI architectures. Moreover, Fonar’s open configuration dramatically reduces claustrophobia concerns affecting significant patient populations refusing conventional MRI examinations.
The company maintains select international installations, including within Middle Eastern markets, serving patients seeking alternative imaging options. Fonar’s systems appeal particularly to specialty orthopedic and spine centers focusing on musculoskeletal diagnostics, where positional imaging provides clinical advantages. Additionally, the company emphasizes patient comfort through open designs accommodating anxious patients, children, and individuals with mobility restrictions requiring specialized positioning support.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Architecture, Field Type, and Application |
| Country Analyzed | The United Arab Emirates (UAE) |
| Companies Analyzed | GE HealthCare, Siemens Healthineers, Philips Healthcare, Canon Medical Systems Corporation, FUJIFILM Holdings Corporation, FONAR Corporation |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- THE UAE MRI SYSTEMS MARKET IS CHARACTERIZED BY STRONG DEMAND FROM PRIVATE HOSPITALS AND SPECIALTY CLINICS
- HIGH ADOPTION OF PREMIUM AND HIGH FIELD MRI SYSTEMS REFLECTS THE COUNTRY’S FOCUS ON ADVANCED HEALTHCARE SERVICES
- MEDICAL TOURISM AND EXPATRIATE POPULATION GROWTH ARE CONTRIBUTING TO RISING DIAGNOSTIC IMAGING DEMAND
- THE MARKET IS MARKED BY RAPID TECHNOLOGY ADOPTION AND SHORTER EQUIPMENT REPLACEMENT CYCLES
MARKET DYNAMICS
- KEY DRIVERS
- GOVERNMENT INVESTMENTS IN HEALTHCARE INFRASTRUCTURE ARE SUPPORTING THE EXPANSION OF ADVANCED DIAGNOSTIC CAPABILITIES
- RISING INCIDENCE OF LIFESTYLE-RELATED DISEASES IS INCREASING DEMAND FOR MRI-BASED DIAGNOSTICS
- GROWTH OF PRIVATE HEALTHCARE AND MEDICAL TOURISM IS DRIVING PROCUREMENT OF HIGH-END MRI SYSTEMS
- FOCUS ON WORLD-CLASS HEALTHCARE STANDARDS IS ACCELERATING ADOPTION OF LATEST MRI TECHNOLOGIES
- KEY RESTRAINTS
- HIGH CAPITAL EXPENDITURE REQUIREMENTS LIMIT MRI ADOPTION AMONG SMALLER CLINICS
- DEPENDENCE ON IMPORTED MEDICAL EQUIPMENT INCREASES COST SENSITIVITY AND SUPPLY RISKS
- SHORTAGE OF SPECIALIZED RADIOLOGY PROFESSIONALS CAN CONSTRAIN SERVICE CAPACITY
- REGULATORY APPROVAL AND COMPLIANCE REQUIREMENTS CAN EXTEND SYSTEM INSTALLATION TIMELINES
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- STRONG SHIFT TOWARD HIGH FIELD AND WIDE BORE MRI SYSTEMS IS ENHANCING PATIENT EXPERIENCE AND DIAGNOSTIC ACCURACY
- INTEGRATION OF AI-DRIVEN IMAGING SOFTWARE IS IMPROVING CLINICAL DECISION SUPPORT
- INCREASING DEPLOYMENT OF MRI SYSTEMS IN MULTISPECIALTY AND SPECIALTY CARE CENTERS IS EXPANDING ACCESS
- EMPHASIS ON PREMIUM IMAGING SERVICES IS DIFFERENTIATING PRIVATE HEALTHCARE PROVIDERS IN A COMPETITIVE MARKET
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR THE UNITED ARAB EMIRATES (UAE)
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- RAW MAGNETIC COIL MANUFACTURING
- MAGNET AND COMPONENT SUPPLY
- MRI SYSTEM ASSEMBLY
- SOFTWARE & AI INTEGRATION
- DISTRIBUTION & LOGISTICS
- INSTALLATION & VALIDATION
- TRAINING & MAINTENANCE SERVICES
- AFTERMARKET SUPPORT
- KEY BUYING CRITERIA
- IMAGE QUALITY & RESOLUTION
- TOTAL COST OF OWNERSHIP
- PATIENT COMFORT FEATURES
- SERVICE & TECHNICAL SUPPORT
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
MAGNETIC RESONANCE IMAGING (MRI) SYSTEMS MARKET BY ARCHITECTURE
- CLOSED MRI SYSTEMS
- STANDARD BORE MRI SYSTEMS
- WIDE BORE MRI SYSTEMS
- OPEN MRI SYSTEMS
- CLOSED MRI SYSTEMS
MAGNETIC RESONANCE IMAGING (MRI) SYSTEMS MARKET BY FIELD TYPE
- HIGH FIELD SYSTEMS
- 5T SYSTEM
- 3T SYSTEM
- LOW-MID FIELD SYSTEMS
- ULTRA HIGH FIELD SYSTEMS
- HIGH FIELD SYSTEMS
MAGNETIC RESONANCE IMAGING (MRI) SYSTEMS MARKET BY APPLICATION
- BRAIN AND NEUROLOGY MRI SYSTEM
- SPINE AND MUSCULOSKELETAL MRI SYSTEM
- PELVIC AND ABDOMINAL MRI SYSTEM
- ONCOLOGY MRI SYSTEM
- VASCULAR MRI SYSTEM
- CARDIOLOGY MRI SYSTEM
- PEDIATRIC MRI SYSTEM
- GASTROENTEROLOGY MRI SYSTEM
- OTHER APPLICATIONS
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- GE HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- SIEMENS HEALTHINEERS
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- PHILIPS HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- CANON MEDICAL SYSTEMS CORP
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- FUJIFILM HOLDINGS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- FONAR CORPORATION
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- GE HEALTHCARE
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – MAGNETIC RESONANCE IMAGING (MRI) SYSTEMS
TABLE 2: MARKET BY ARCHITECTURE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 3: MARKET BY ARCHITECTURE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 4: MARKET BY CLOSED MRI SYSTEMS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 5: MARKET BY CLOSED MRI SYSTEMS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 6: MARKET BY FIELD TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 7: MARKET BY FIELD TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 8: MARKET BY HIGH FIELD SYSTEMS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 9: MARKET BY HIGH FIELD SYSTEMS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 10: MARKET BY APPLICATION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 11: MARKET BY APPLICATION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 12: KEY PLAYERS OPERATING IN THE UNITED ARAB EMIRATES (UAE) MARKET
TABLE 13: LIST OF MERGERS & ACQUISITIONS
TABLE 14: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 15: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 16: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: KEY MARKET TRENDS
FIGURE 2: PORTER’S FIVE FORCES ANALYSIS
FIGURE 3: GROWTH PROSPECT MAPPING FOR THE UNITED ARAB EMIRATES (UAE)
FIGURE 4: MARKET MATURITY ANALYSIS
FIGURE 5: MARKET CONCENTRATION ANALYSIS
FIGURE 6: VALUE CHAIN ANALYSIS
FIGURE 7: KEY BUYING CRITERIA
FIGURE 8: SEGMENT GROWTH POTENTIAL, BY ARCHITECTURE, IN 2025
FIGURE 9: CLOSED MRI SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY CLOSED MRI SYSTEMS, IN 2025
FIGURE 11: STANDARD BORE MRI SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: WIDE BORE MRI SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: OPEN MRI SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 14: SEGMENT GROWTH POTENTIAL, BY FIELD TYPE, IN 2025
FIGURE 15: HIGH FIELD SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: SEGMENT GROWTH POTENTIAL, BY HIGH FIELD SYSTEMS, IN 2025
FIGURE 17: 1.5T SYSTEM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: 3T SYSTEM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: LOW-MID FIELD SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: ULTRA HIGH FIELD SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: SEGMENT GROWTH POTENTIAL, BY APPLICATION, IN 2025
FIGURE 22: BRAIN AND NEUROLOGY MRI SYSTEM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: SPINE AND MUSCULOSKELETAL MRI SYSTEM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: VASCULAR MRI SYSTEM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: PELVIC AND ABDOMINAL MRI SYSTEM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: ONCOLOGY MRI SYSTEM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: CARDIOLOGY MRI SYSTEM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: PEDIATRIC MRI SYSTEM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 29: GASTROENTEROLOGY MRI SYSTEM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: OTHER APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
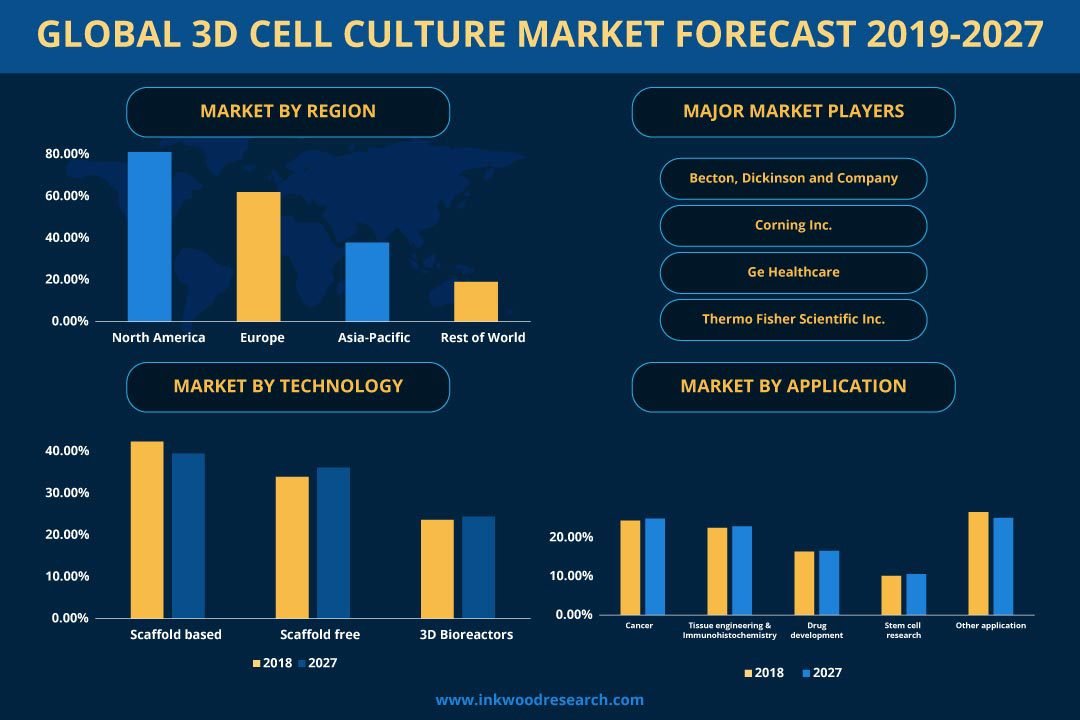
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
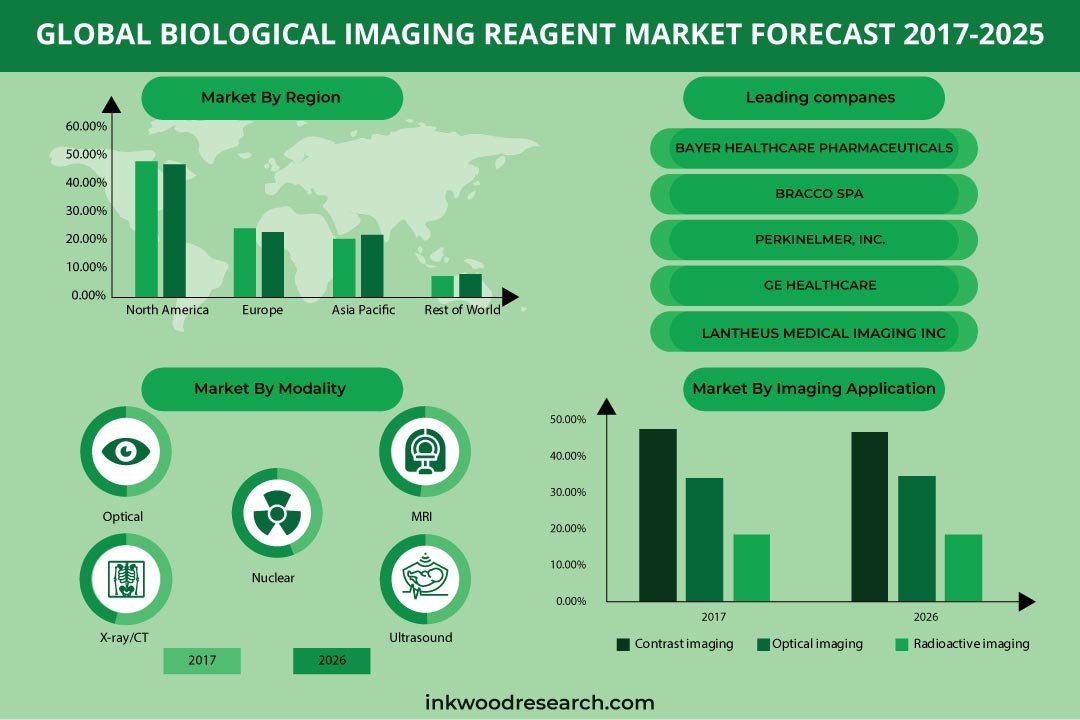
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034