United Arab Emirates Cardiovascular Ultrasound Market by Device Display (Color Display Systems, Black & White (B/W) Display Systems) Market by Technology (2D Ultrasound, 3D & 4D Ultrasound, Doppler Imaging) Market by Application (Diagnostic Applications, Therapeutic Applications) Market by Type (Transthoracic Echocardiogram, Transesophageal Echocardiogram, Stress Echocardiogram, Fetal Echocardiography, Other Types) Market by End-User (Hospitals, Diagnostic Centers, Ambulatory Care Centers, Other End-Users), by Geography
UNITED ARAB EMIRATES CARDIOVASCULAR ULTRASOUND MARKET OVERVIEW
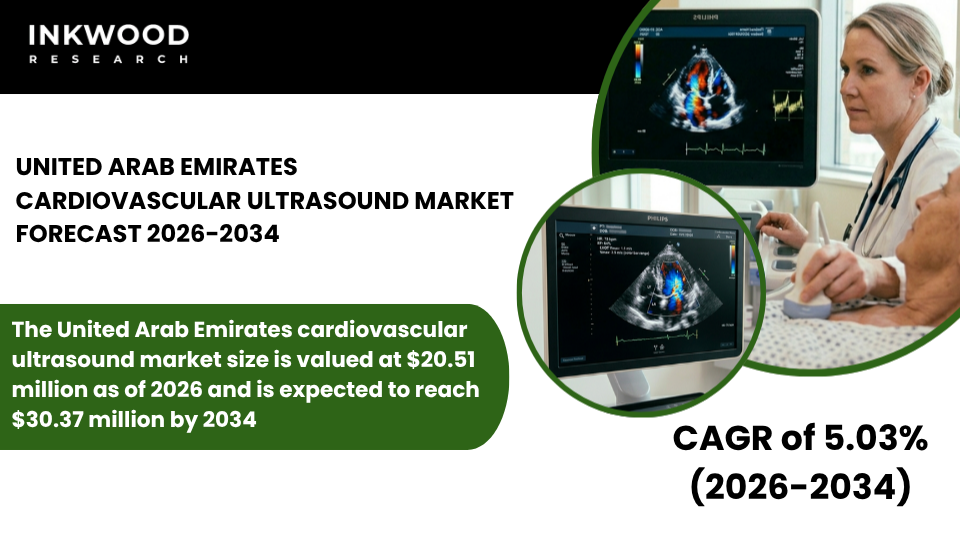
The United Arab Emirates cardiovascular ultrasound market size is valued at $20.51 million as of 2026 and is expected to reach $30.37 million by 2034, progressing with a CAGR of 5.03% during the forecast years, 2026–2034.
The United Arab Emirates represents one of the most distinctive and premium cardiovascular ultrasound markets in the Middle East, defined by high per capita healthcare spending, a well-established private hospital sector, and a government actively investing in world-class medical infrastructure. Cardiovascular disease is a significant and growing public health challenge in the country.
According to research published in BMC Cardiovascular Disorders, drawing on UAE Ministry of Health and Prevention national survey data, cardiovascular disease accounts for 40% of mortality in the UAE. Risk factors are widespread. Hypertension, obesity, dyslipidemia, and diabetes are prevalent across both Emirati nationals and the country’s large expatriate population.
This creates a broad and diverse patient base for cardiac diagnostic procedures including the transthoracic echocardiogram, echocardiogram transesophageal, and stress echocardiogram. A commentary published in Advances in Biomedical and Health Sciences (2024) further notes that the UAE has prioritized national strategies for cardiovascular disease prevention, including expanding access to early detection technologies and essential cardiac imaging capabilities across the country’s hospital network.
The UAE’s healthcare policy environment strongly supports market growth. The country’s national “We the UAE 2031” vision, formally launched in November 2022, sets an ambitious target for the UAE to rank among the world’s top healthcare systems. Moreover, health is identified as a core pillar of the national development agenda, as confirmed by the UAE Government official platform.
To Know More About This Report, Request a Free Sample Copy
Health technology, AI-driven diagnostics, and smart hospital infrastructure are central to this vision. At Arab Health 2024, the UAE Ministry of Health and Prevention reaffirmed its commitment to building a comprehensive preventive health system aligned with AI-driven population health initiatives, a policy direction that directly supports procurement of advanced cardiac imaging systems.
Private hospital expansion is adding further momentum. Burjeel Holdings opened nine new primary care clinics in late 2024 as part of an AED 20 million investment. NMC Healthcare, serving 5-6 million patients annually through 85 facilities, is expanding with nine additional hospitals and clinics. These expansions are broadening the institutional base for cardiovascular ultrasound procurement across both Abu Dhabi and Dubai, and increasingly into the Northern Emirates.
The UAE also benefits from a thriving medical tourism ecosystem. International patients seek out UAE hospitals, particularly institutions like the Cleveland Clinic Abu Dhabi and Sheikh Shakhbout Medical City, for advanced cardiac care. This drives demand for premium-tier cardiac ultrasound systems that meet international clinical standards.
Together, a high-income patient base, strong government policy tailwinds, rapid private hospital growth, and a distinctly technology-forward procurement culture make the UAE one of the most commercially attractive cardiovascular imaging markets in the broader Middle East and Africa region.
The United Arab Emirates cardiovascular ultrasound market is segmented by device display, technology, application, type, and end-user. The technology segment is further categorized into 2D ultrasound, 3D & 4D ultrasound, and Doppler imaging.
The 3D & 4D ultrasound sub-segment holds a dominant and fast-growing share within the technology segment of the UAE cardiovascular ultrasound market. This reflects the country’s distinctly premium procurement profile. The UAE is home to some of the most advanced cardiac centers in the Middle East. These institutions, including major tertiary hospitals in Abu Dhabi and Dubai, operate at international standards and consistently procure the latest imaging platforms available globally.
3D and 4D echocardiography offers capabilities that 2D platforms cannot match. It provides volumetric cardiac imaging that enables precise assessment of valvular anatomy, three-dimensional chamber quantification, and real-time guidance for structural heart interventions. These capabilities are highly relevant in the UAE, where complex cardiac procedures are performed routinely at flagship institutions and where clinical staff are trained to leverage the full depth of advanced echocardiographic technologies.
Moreover, the UAE’s growing focus on AI-enhanced diagnostics, underpinned by the national AI strategy and the “We the UAE 2031” vision, is accelerating adoption of next-generation 3D and 4D platforms that embed automated measurements and AI-assisted workflow tools. For vendors in the cardiovascular imaging market, the 3D & 4D ultrasound sub-segment represents both a premium revenue opportunity and a key differentiation battleground in the UAE, where technology leadership and clinical credibility are decisive procurement criteria.
Some of the top players operating in the UAE cardiovascular ultrasound market include Siemens Healthineers AG, GE HealthCare, Koninklijke Philips NV, Canon Medical Systems Corporation, Esaote SpA, etc.
Siemens Healthineers AG is an Erlangen, Germany-headquartered global medical technology company and one of the most strategically active players in the UAE cardiovascular ultrasound market. The company operates across diagnostic imaging, laboratory diagnostics, and cancer care, with cardiovascular ultrasound forming a core component of its imaging portfolio.
Siemens Healthineers has a direct presence in the Middle East and Africa, led by its regional managing director Vivek Kanade, and consistently uses Arab Health, the region’s flagship medical technology exhibition, held in Dubai, as a primary market engagement and product launch platform. In fiscal year 2024, Siemens Healthineers generated approximately €22.4 billion in revenue globally, a scale that supports sustained R&D, regional service infrastructure, and long-term commercial commitment to the UAE cardiovascular ultrasound market.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Device Display, Technology, Type, End-User |
| Country Analyzed | The United Arab Emirates |
| Companies Analyzed | Canon Medical Systems Corporation, Esaote SpA, FUJIFILM Holdings Corporation, GE Healthcare, Koninklijke Philips NV, Samsung Medison Co Ltd, Siemens Healthineers AG |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- THE UNITED ARAB EMIRATES MARKET IS CHARACTERIZED BY HIGH PER CAPITA HEALTHCARE SPENDING AND STRONG ADOPTION OF ADVANCED TECHNOLOGIES
- PRIVATE HOSPITALS AND SPECIALTY CARDIAC CENTERS ACCOUNT FOR A MAJOR SHARE OF SYSTEM INSTALLATIONS
- PREMIUM AND HIGH-END ULTRASOUND SYSTEMS DOMINATE THE MARKET MIX
- MEDICAL TOURISM CONTRIBUTES SIGNIFICANTLY TO CARDIAC DIAGNOSTIC PROCEDURE VOLUMES
MARKET DYNAMICS
- KEY DRIVERS
- RISING INCIDENCE OF CARDIOVASCULAR DISEASES LINKED TO LIFESTYLE FACTORS IS DRIVING DEMAND FOR EARLY DIAGNOSIS
- GOVERNMENT INVESTMENTS IN SMART HEALTHCARE INFRASTRUCTURE ARE SUPPORTING TECHNOLOGY ADOPTION
- STRONG PRESENCE OF INTERNATIONAL HOSPITAL GROUPS IS ENCOURAGING THE PROCUREMENT OF ADVANCED SYSTEMS
- GROWING MEDICAL TOURISM FLOWS ARE INCREASING DEMAND FOR HIGH QUALITY CARDIAC IMAGING
- KEY RESTRAINTS
- HIGH CAPITAL COSTS OF ADVANCED SYSTEMS CAN LIMIT PROCUREMENT BY SMALLER FACILITIES
- DEPENDENCE ON IMPORTED EQUIPMENT EXPOSES THE MARKET TO SUPPLY CHAIN DISRUPTIONS
- LIMITED LOCAL MANUFACTURING CAPABILITIES INCREASE RELIANCE ON GLOBAL SUPPLIERS
- REGULATORY COMPLIANCE REQUIREMENTS CAN EXTEND PROCUREMENT TIMELINES
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- INTEGRATION OF ARTIFICIAL INTELLIGENCE AND CLOUD CONNECTIVITY IN CARDIAC IMAGING SYSTEMS
- INCREASING USE OF HANDHELD ULTRASOUND DEVICES IN OUTPATIENT SETTINGS
- EXPANSION OF SPECIALIZED CARDIAC CENTERS EQUIPPED WITH ADVANCED 4D ECHOCARDIOGRAPHY
- FOCUS ON VALUE-BASED HEALTHCARE MODELS TO IMPROVE CLINICAL OUTCOMES AND COST EFFICIENCY
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR THE UNITED ARAB EMIRATES
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SUPPLIERS
- COMPONENT MANUFACTURERS
- SYSTEM INTEGRATORS
- DEVICE MANUFACTURERS
- DISTRIBUTION CHANNELS
- HEALTHCARE PROVIDERS
- AFTER SALES SERVICES
- KEY BUYING CRITERIA
- IMAGE RESOLUTION
- PORTABILITY FEATURES
- TOTAL COST OWNERSHIP
- SERVICE SUPPORT AVAILABILITY
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
CARDIOVASCULAR ULTRASOUND MARKET BY DEVICE DISPLAY
- COLOR DISPLAY SYSTEMS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- BLACK & WHITE (B/W) DISPLAY SYSTEMS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- COLOR DISPLAY SYSTEMS
CARDIOVASCULAR ULTRASOUND MARKET BY TECHNOLOGY
- 2D ULTRASOUND
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- 3D & 4D ULTRASOUND
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DOPPLER IMAGING
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- 2D ULTRASOUND
CARDIOVASCULAR ULTRASOUND MARKET BY APPLICATION
- DIAGNOSTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- THERAPEUTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DIAGNOSTIC APPLICATIONS
CARDIOVASCULAR ULTRASOUND MARKET BY TYPE
- TRANSTHORACIC ECHOCARDIOGRAM
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- TRANSESOPHAGEAL ECHOCARDIOGRAM
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- STRESS ECHOCARDIOGRAM
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- FETAL ECHOCARDIOGRAPHY
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- OTHER TYPES
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- TRANSTHORACIC ECHOCARDIOGRAM
CARDIOVASCULAR ULTRASOUND MARKET BY END-USER
- HOSPITALS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DIAGNOSTIC CENTERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- AMBULATORY CARE CENTERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- OTHER END-USERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- HOSPITALS
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- CANON MEDICAL SYSTEMS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ESAOTE SPA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- FUJIFILM HOLDINGS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GE HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- KONINKLIJKE PHILIPS NV
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SAMSUNG MEDISON CO LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SIEMENS HEALTHINEERS AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- CANON MEDICAL SYSTEMS CORPORATION
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – CARDIOVASCULAR ULTRASOUND
TABLE 2: CARDIOVASCULAR ULTRASOUND MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY DEVICE DISPLAY, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY DEVICE DISPLAY, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: MARKET BY TECHNOLOGY, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: MARKET BY TECHNOLOGY, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: MARKET BY TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: MARKET BY TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: MARKET BY END-USER, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: MARKET BY END-USER, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: KEY PLAYERS OPERATING IN THE UNITED ARAB EMIRATES MARKET
TABLE 12: LIST OF MERGERS & ACQUISITIONS
TABLE 13: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 14: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 15: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR UNITED ARAB EMIRATES
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY DEVICE DISPLAY, IN 2025
FIGURE 11: COLOR DISPLAY SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: BLACK & WHITE (B/W) DISPLAY SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY TECHNOLOGY, IN 2025
FIGURE 14: 2D ULTRASOUND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: 3D & 4D ULTRASOUND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: DOPPLER IMAGING MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: SEGMENT GROWTH POTENTIAL, BY TYPE, IN 2025
FIGURE 18: TRANSTHORACIC ECHOCARDIOGRAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: TRANSESOPHAGEAL ECHOCARDIOGRAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: STRESS ECHOCARDIOGRAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: FETAL ECHOCARDIOGRAPHY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: OTHER TYPES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: SEGMENT GROWTH POTENTIAL, BY END-USER, IN 2025
FIGURE 24: HOSPITALS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: DIAGNOSTIC CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: AMBULATORY CARE CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: OTHER END-USERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
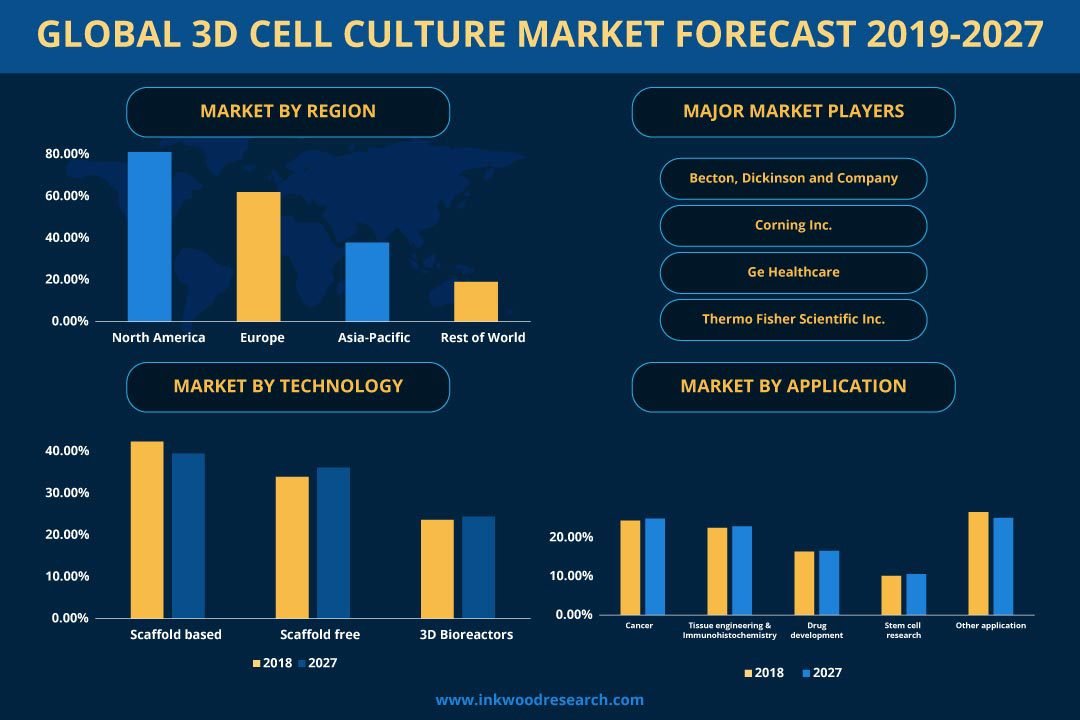
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
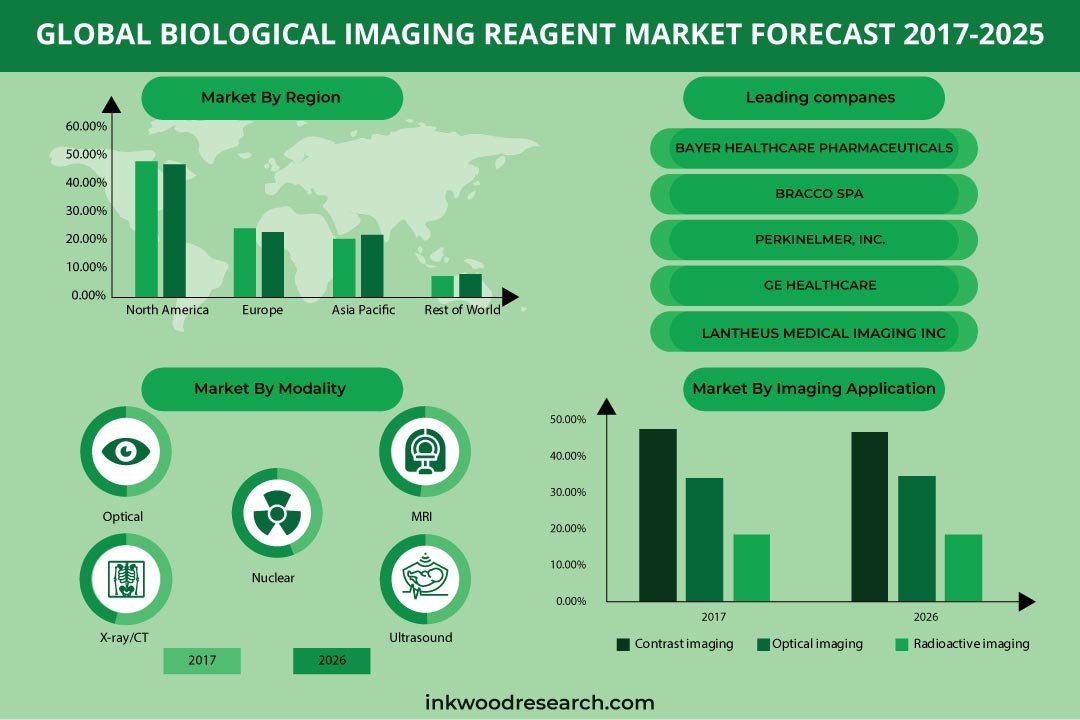
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034