South Korea Contrast Ultrasound Market by Product (Equipment, Contrast Agents) Market by Type (Non-Targeted, Targeted) Market by Application (Diagnostic Applications, Therapeutic Applications) Market by End Use (Hospitals, Clinics, Ambulatory Diagnostic Centers), by Geography
SOUTH KOREA CONTRAST ULTRASOUND MARKET OVERVIEW
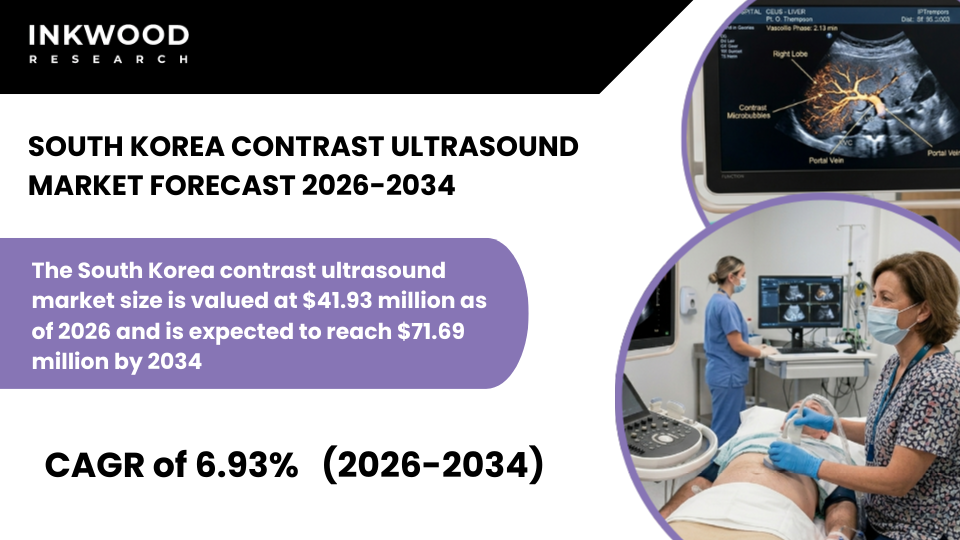
The South Korea contrast ultrasound market size is valued at $41.93 million as of 2026 and is expected to reach $71.69 million by 2034, progressing with a CAGR of 6.93% during the forecast years, 2026-2034.
South Korea’s contrast ultrasound market is experiencing steady growth driven by advanced hospital infrastructure, high diagnostic imaging utilization rates, and strong government support for digital healthcare transformation. The country benefits from one of the world’s most technologically sophisticated healthcare systems, characterized by widespread access to state-of-the-art medical equipment and highly trained medical professionals proficient in advanced imaging techniques.
The rising incidence of liver diseases and cancer is creating sustained demand for accurate, real-time diagnostic imaging solutions that can characterize focal liver lesions and assess tumor vascularity without exposing patients to ionizing radiation. According to the Korea Central Cancer Registry, liver cancer remains a significant public health concern, with projections indicating continued disease burden despite improvements in treatment outcomes.
Data also shows that liver cancer caused 20.4 deaths per 100,000 people in 2024, making it the second-leading cause of cancer-related deaths in the country. National healthcare screening programs for hepatocellular carcinoma among high-risk populations with chronic hepatitis B and C infections are driving routine use of enhanced ultrasound in surveillance protocols across tertiary hospitals and specialty liver clinics.
To Know More About This Report, Request a Free Sample Copy
Moreover, South Korea’s aging population is expanding the patient pool requiring cardiac and abdominal imaging, as elderly individuals face higher risks of cardiovascular disease, liver cirrhosis, and malignancies that necessitate frequent diagnostic monitoring. Government investment in digital healthcare infrastructure through initiatives aimed at modernizing medical facilities and expanding telemedicine capabilities is enhancing access to advanced ultrasound systems equipped with artificial intelligence and cloud-based image management.
The country’s universal health insurance system, administered through the National Health Insurance Service, provides comprehensive coverage that reduces financial barriers for patients requiring contrast ultrasound procedures. Furthermore, strategic partnerships between academic hospitals and medical device manufacturers are accelerating innovation in molecular imaging applications, where molecule-targeted microbubbles enable the detection of early-stage cancers and the assessment of treatment response. These factors, in turn, are set to boost the contrast ultrasound market growth in South Korea during the forecast period.
The South Korea contrast ultrasound market is segmented into product, type, application, and end use. The type segment is further categorized into non-targeted and targeted contrast agents.
The non-targeted segment plays a vital role in the South Korea contrast ultrasound market and represents the conventional approach to contrast-enhanced imaging, where microbubbles circulate freely through the bloodstream to enhance visualization of vascular structures and tissue perfusion patterns. Non-targeted contrast agents consist of gas-filled microbubbles with stabilizing shells that reflect ultrasound waves to produce enhanced images of blood flow in organs such as the heart, liver, kidneys, and blood vessels.
These agents are widely used in diagnostic applications across cardiology, hepatology, and radiology departments in hospitals and ambulatory diagnostic centers throughout South Korea. The segment benefits from well-established clinical guidelines and extensive physician experience with commercially available products that have demonstrated excellent safety profiles over decades of clinical use.
Korean physicians have adopted non-targeted contrast ultrasound as a first-line imaging modality for characterizing focal liver lesions in patients with cirrhosis or viral hepatitis, where early detection of hepatocellular carcinoma significantly impacts treatment planning and patient outcomes. Additionally, cardiologists routinely employ non-targeted contrast agents to improve visualization of left ventricular function in patients with technically difficult echocardiograms, enabling accurate assessment of cardiac abnormalities that would otherwise require more expensive or invasive diagnostic procedures.
The non-targeted segment is experiencing growth as hospitals upgrade their ultrasound equipment to include specialized imaging modes such as contrast pulse sequencing and harmonic imaging, which optimize microbubble detection while suppressing background tissue signals. Regulatory approvals from the Ministry of Food and Drug Safety have expanded the clinical indications for non-targeted contrast agents, encouraging broader adoption across diverse medical specialties beyond traditional cardiology and hepatology applications.
Moreover, favorable reimbursement policies from the National Health Insurance Service are making contrast ultrasound procedures more economically viable for healthcare providers, particularly in competitive urban markets where hospitals seek to differentiate their service offerings through advanced diagnostic capabilities. Also, the availability of non-targeted contrast agents from multiple manufacturers creates competitive pricing dynamics that improve affordability and accessibility for hospitals and clinics seeking cost-effective alternatives to CT and MRI for specific diagnostic applications.
Some of the top players operating in the South Korea contrast ultrasound market include Samsung Healthcare, GE Healthcare, Siemens Healthineers AG, and Bracco Imaging SpA, among others.
Samsung Healthcare, a division of Samsung Electronics headquartered in Seoul, is a leading domestic medical device manufacturer with strong market presence in South Korea’s diagnostic imaging sector. The company develops and manufactures advanced ultrasound systems with integrated contrast-enhanced imaging capabilities designed specifically for Korean healthcare facilities, ranging from large university hospitals to smaller community clinics.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Product, Type, Application, End Use |
| Country Analyzed | South Korea |
| Companies Analyzed | GE HealthCare, Bracco Imaging SpA, Lantheus Holdings Inc, Siemens Healthineers AG, Koninklijke Philips NV, Bayer AG, Guerbet, Canon Medical Systems Corporation, Shenzhen Mindray Bio-Medical Electronics Co Ltd, Esaote SpA, FUJIFILM Holdings Corporation, Samsung Healthcare, Daiichi Sankyo Company Limited, Trivitron Healthcare Pvt Ltd |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- ADVANCED HOSPITAL INFRASTRUCTURE AND HIGH DIAGNOSTIC IMAGING UTILIZATION RATES ARE SUPPORTING STEADY DEMAND FOR CONTRAST ENHANCED ULTRASOUND PROCEDURES
- CARDIOVASCULAR AND HEPATOCELLULAR CARCINOMA SCREENING PROGRAMS ARE DRIVING CLINICAL ADOPTION IN TERTIARY CARE CENTERS
- LOCAL MANUFACTURERS AND GLOBAL OEMS ARE ACTIVELY EXPANDING ULTRASOUND PORTFOLIOS WITH PREMIUM IMAGING CAPABILITIES
- REIMBURSEMENT SUPPORT FOR SELECT INDICATIONS IS IMPROVING MARKET PENETRATION ACROSS URBAN HEALTHCARE FACILITIES
MARKET DYNAMICS
- KEY DRIVERS
- RISING INCIDENCE OF LIVER DISEASES AND CANCER IS INCREASING DEMAND FOR ACCURATE AND REAL TIME IMAGING SOLUTIONS
- STRONG GOVERNMENT INVESTMENT IN DIGITAL HEALTHCARE INFRASTRUCTURE IS ENHANCING ACCESS TO ADVANCED ULTRASOUND SYSTEMS
- GROWING PREFERENCE FOR NON-IONIZING AND COST-EFFECTIVE DIAGNOSTIC MODALITIES IS BOOSTING CLINICAL UTILIZATION
- INCREASING GERIATRIC POPULATION IS EXPANDING THE PATIENT POOL REQUIRING CARDIAC AND ABDOMINAL IMAGING
- KEY RESTRAINTS
- LIMITED AWARENESS OF CONTRAST ENHANCED ULTRASOUND IN PRIMARY CARE SETTINGS IS RESTRICTING BROADER ADOPTION
- HIGH COST OF ADVANCED ULTRASOUND EQUIPMENT MAY LIMIT PROCUREMENT IN SMALLER HOSPITALS
- STRICT REGULATORY REQUIREMENTS FOR CONTRAST AGENT APPROVAL CAN DELAY PRODUCT INTRODUCTIONS
- COMPETITION FROM CT AND MRI IN COMPLEX DIAGNOSTIC CASES MAY REDUCE PROCEDURE VOLUMES
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- INTEGRATION OF ARTIFICIAL INTELLIGENCE WITH ULTRASOUND PLATFORMS IS IMPROVING DIAGNOSTIC CONFIDENCE
- EXPANSION OF POINT OF CARE ULTRASOUND IN EMERGENCY AND CRITICAL CARE SETTINGS IS SUPPORTING MARKET GROWTH
- INCREASING CLINICAL RESEARCH ON TARGETED MICROBUBBLE AGENTS IS ADVANCING MOLECULAR IMAGING APPLICATIONS
- STRATEGIC PARTNERSHIPS BETWEEN ACADEMIC HOSPITALS AND DEVICE MANUFACTURERS ARE ACCELERATING INNOVATION
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR SOUTH KOREA
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SUPPLIERS
- CONTRAST AGENT MANUFACTURERS
- ULTRASOUND OEMS
- DISTRIBUTION PARTNERS
- HOSPITAL PROCUREMENT
- END-USER FACILITIES
- KEY BUYING CRITERIA
- IMAGE CLARITY
- SAFETY PROFILE
- REGULATORY APPROVAL
- COST EFFECTIVENESS
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
CONTRAST ULTRASOUND MARKET BY PRODUCT
- EQUIPMENT
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- CONTRAST AGENTS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- EQUIPMENT
CONTRAST ULTRASOUND MARKET BY TYPE
- NON-TARGETED
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- TARGETED
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- NON-TARGETED
CONTRAST ULTRASOUND MARKET BY APPLICATION
- DIAGNOSTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- THERAPEUTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DIAGNOSTIC APPLICATIONS
CONTRAST ULTRASOUND MARKET BY END USE
- HOSPITALS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- CLINICS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- AMBULATORY DIAGNOSTIC CENTERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- HOSPITALS
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- GE HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- BRACCO IMAGING SPA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- LANTHEUS HOLDINGS INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SIEMENS HEALTHINEERS AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- KONINKLIJKE PHILIPS NV
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- BAYER AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GUERBET
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- CANON MEDICAL SYSTEMS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ESAOTE SPA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- FUJIFILM HOLDINGS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SAMSUNG HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- DAIICHI SANKYO COMPANY LIMITED
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- TRIVITRON HEALTHCARE PVT LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GE HEALTHCARE
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – CONTRAST ULTRASOUND
TABLE 2: CONTRAST ULTRASOUND MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY PRODUCT, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY PRODUCT, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: MARKET BY TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: MARKET BY TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: MARKET BY APPLICATION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: MARKET BY APPLICATION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: MARKET BY END USE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: MARKET BY END USE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: KEY PLAYERS OPERATING IN THE SOUTH KOREAN MARKET
TABLE 12: LIST OF MERGERS & ACQUISITIONS
TABLE 13: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 14: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 15: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR SOUTH KOREA
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY PRODUCT, IN 2025
FIGURE 11: EQUIPMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: CONTRAST AGENTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY TYPE, IN 2025
FIGURE 14: NON-TARGETED MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: TARGETED MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: SEGMENT GROWTH POTENTIAL, BY APPLICATION, IN 2025
FIGURE 17: DIAGNOSTIC APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: THERAPEUTIC APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: SEGMENT GROWTH POTENTIAL, BY END USE, IN 2025
FIGURE 20: HOSPITALS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: CLINICS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: AMBULATORY DIAGNOSTIC CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034