North America Integrated/Hybrid Operating Room Market by Equipment (Diagnostic Imaging Systems, Operating Room Fixtures, Other Equipment) Market by Application (Cardiovascular Surgery, Neurosurgery, Thoracic Surgery, Orthopedic Surgery, Other Applications) Market by End-User (Hospital and Surgical Centers, Outpatient Surgical Centers, Other End-Users), by Geography
NORTH AMERICA INTEGRATED/HYBRID OPERATING ROOM MARKET OVERVIEW
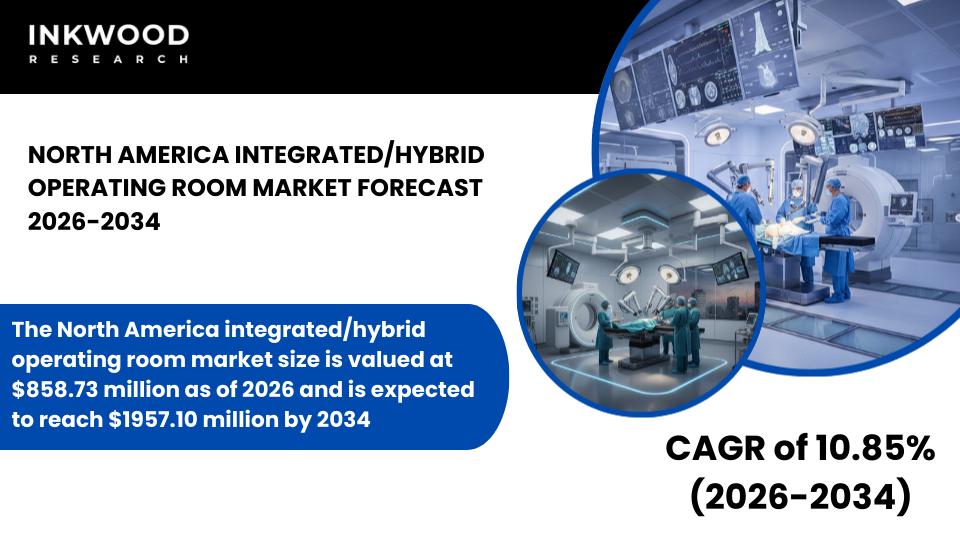
The North America integrated/hybrid operating room market size is valued at $858.73 million as of 2026 and is expected to reach $1957.10 million by 2034, progressing with a CAGR of 10.85% during the forecast years, 2026-2034.
North America continues to dominate the global hybrid operating rooms market, driven by substantial hospital investments in advanced surgical infrastructure and a well-established healthcare ecosystem. The region benefits from high per capita income levels, which enable healthcare facilities to allocate significant capital budgets toward cutting-edge medical technologies.
Moreover, the prevalence of cardiovascular diseases remains a critical driver, with the CDC reporting that one person dies every 34 seconds from cardiovascular disease in the United States. This alarming statistic underscores the urgent need for sophisticated surgical facilities equipped with real-time imaging capabilities.
Consequently, tertiary care hospitals and academic medical centers are prioritizing hybrid OR installations to address complex cardiovascular and neurosurgical procedures. Additionally, favorable reimbursement policies and ongoing technological innovations from major manufacturers headquartered in the region further accelerate market expansion.
To Know More About This Report, Request a Free Sample Copy
The North America integrated/hybrid operating room market growth assessment includes the analysis of the United States and Canada.
The United States represents the largest market for integrated hybrid operating room systems within North America, accounting for the dominant share of regional revenue. According to data from the American Hospital Association, there were 6,093 operating hospitals in the United States as of 2022, marking significant growth from 5,534 facilities in 2016. This expansion in hospital capacity directly correlates with increased demand for advanced surgical suites capable of handling complex, multi-disciplinary procedures.
Furthermore, the growing burden of chronic diseases requiring surgical intervention drives hospitals to modernize their operating room infrastructure. Healthcare facilities across major metropolitan areas are investing heavily in hybrid OR technology to attract top surgical talent and maintain competitive advantages in regional markets. The regulatory environment in the United States also supports adoption, with the FDA providing clear pathways for approval of advanced imaging systems and integrated surgical equipment.
The strong emphasis on patient safety and outcome improvement motivates hospitals to embrace technologies that reduce procedure time and minimize complications. Academic medical centers and large hospital systems lead adoption patterns, often serving as early implementers of next-generation hybrid OR platforms. These institutions recognize that hybrid operating rooms enable seamless transitions between minimally invasive and open surgical techniques within a single sterile environment.
Additionally, the shift toward value-based care models incentivizes healthcare providers to invest in technologies that demonstrably improve patient outcomes while reducing overall treatment costs. Vendors recognize the United States as a critical market for product launches and innovation, resulting in robust competition that benefits end-users through continuous technological advancement and competitive pricing strategies.
Canada’s integrated hybrid operating room market demonstrates steady growth, supported by increasing healthcare investments across both public and private sectors. According to the Canadian Institute for Health Information, total health care spending in Canada was expected to reach $372 billion in 2024, or $9,054 per Canadian. This substantial funding enables hospitals to upgrade surgical facilities and adopt advanced medical technologies. Canadian healthcare institutions prioritize patient-centered care delivery, recognizing that hybrid OR systems significantly enhance surgical precision and reduce recovery times.
Moreover, the country’s aging population creates sustained demand for cardiovascular and orthopedic procedures that benefit from hybrid OR capabilities. Provincial health authorities actively support hospital modernization initiatives, viewing advanced surgical infrastructure as essential for maintaining healthcare quality standards across the nation.
The North America integrated/hybrid operating room market is segmented into equipment, application, and end-user. The equipment segment is further categorized into diagnostic imaging systems, operating room fixtures, and other equipment.
The diagnostic imaging systems segment plays a pivotal role in the North American market, driven by the critical role these technologies play in enabling real-time surgical guidance. Angiography systems particularly command significant market share due to their indispensability in cardiovascular surgery applications, which represent the largest procedural category for hybrid OR utilization.
These advanced imaging platforms deliver high-resolution vascular visualization without requiring patient repositioning, fundamentally transforming how complex interventions are performed. Furthermore, continuous technological innovation enhances image quality while simultaneously reducing radiation exposure to both patients and surgical teams.
Major manufacturers invest heavily in research and development to integrate artificial intelligence algorithms that optimize imaging parameters automatically based on procedure type. Hospitals recognize that superior diagnostic imaging capabilities directly correlate with improved surgical outcomes and reduced complication rates.
Consequently, healthcare facilities prioritize procurement of the latest-generation angiography systems when establishing or upgrading hybrid OR facilities. The segment benefits from strong regulatory support and established clinical evidence demonstrating efficacy across multiple surgical specialties.
Some of the top players operating in the North America integrated/hybrid operating room market include Stryker Corporation, GE Healthcare, Siemens AG, Koninklijke Philips NV, etc.
Stryker Corporation stands as a prominent player in the North American integrated hybrid operating room market, headquartered in Portage, Michigan. The company operates as a leading global medical technology firm specializing in orthopedic implants, surgical equipment, and neurotechnology products.
Stryker’s hybrid OR portfolio encompasses advanced visualization systems, surgical navigation platforms, and integrated operating room furniture solutions designed for seamless workflow optimization. The company serves hospitals and surgical centers throughout North America through direct sales teams and established distributor networks.
Notably, Stryker differentiates itself through turnkey OR solutions that combine equipment, installation services, and comprehensive training programs. Recent strategic acquisitions, including mfPHD in April 2024, strengthen the company’s ability to deliver modular wall systems and embedded technologies for intelligent operating rooms, positioning Stryker as a comprehensive solutions provider in the rapidly evolving hybrid OR landscape.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Equipment, Application, and End-User |
| Countries Analyzed | The United States and Canada |
| Companies Analyzed | Arthrex Inc, Barco NV, Carl Zeiss Meditec Group, CONMED Corporation, Drägerwerk AG & Co KGaA, Fisher & Paykel Healthcare Corporation Limited, GE Healthcare, Getinge AB, Integra LifeSciences Holdings Corporation, KARL STORZ SE & Co KG, Koninklijke Philips NV, Olympus Corporation, Siemens AG, Smith & Nephew PLC, Stryker Corporation |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- HOSPITALS ARE INCREASINGLY INVESTING IN HYBRID ORS TO ENABLE MULTI-DISCIPLINARY PROCEDURES WITHIN A SINGLE SURGICAL ENVIRONMENT
- CARDIOVASCULAR AND NEUROSURGERY ACCOUNT FOR THE LARGEST SHARE OF HYBRID OR DEPLOYMENTS DUE TO IMAGING-INTENSIVE WORKFLOWS
- TERTIARY AND QUATERNARY CARE HOSPITALS DOMINATE DEMAND BECAUSE OF HIGH PROCEDURE VOLUMES AND CAPITAL AVAILABILITY
- EMERGING MARKETS ARE SHIFTING FROM CONVENTIONAL ORS TO SEMI-INTEGRATED SYSTEMS AS A STEPPING STONE TO FULL HYBRID ROOMS
MARKET DYNAMICS
- KEY DRIVERS
- RISING VOLUME OF MINIMALLY INVASIVE AND IMAGE-GUIDED SURGERIES IS ACCELERATING DEMAND FOR HYBRID ORS
- HOSPITAL FOCUS ON IMPROVING SURGICAL OUTCOMES AND REDUCING PROCEDURE TIME IS SUPPORTING ADOPTION
- TECHNOLOGICAL ADVANCES IN INTRAOPERATIVE IMAGING AND DIGITAL OR INTEGRATION ARE ENHANCING CLINICAL VALUE
- INCREASING INVESTMENTS IN SMART HOSPITAL INFRASTRUCTURE ARE FUELING MARKET EXPANSION
- KEY RESTRAINTS
- HIGH CAPITAL AND INSTALLATION COSTS LIMIT ADOPTION AMONG SMALL AND MEDIUM-SIZED HOSPITALS
- COMPLEXITY OF SYSTEM INTEGRATION REQUIRES SPECIALIZED TECHNICAL AND CLINICAL TRAINING
- SPACE AND INFRASTRUCTURE REQUIREMENTS MAKE RETROFITTING EXISTING ORS CHALLENGING
- LONG PROCUREMENT AND APPROVAL CYCLES DELAY PURCHASING DECISIONS IN PUBLIC HEALTHCARE SYSTEMS
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- INTEGRATION OF ADVANCED IMAGING WITH SURGICAL NAVIGATION IS BECOMING A STANDARD FEATURE
- MODULAR AND SCALABLE HYBRID OR DESIGNS ARE GAINING TRACTION TO REDUCE INITIAL INVESTMENT
- ARTIFICIAL INTELLIGENCE ENABLED WORKFLOW MANAGEMENT IS IMPROVING SURGICAL EFFICIENCY
- VENDORS ARE OFFERING TURNKEY SOLUTIONS INCLUDING DESIGN, INSTALLATION, AND LIFECYCLE SUPPORT
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR NORTH AMERICA
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- COMPONENT MANUFACTURERS
- IMAGING SYSTEM SUPPLIERS
- OR INTEGRATION PROVIDERS
- SOFTWARE PLATFORM DEVELOPERS
- SYSTEM INTEGRATORS
- HOSPITAL END-USERS
- KEY BUYING CRITERIA
- IMAGING COMPATIBILITY
- SYSTEM INTEROPERABILITY
- TOTAL COST OWNERSHIP
- AFTER SALES SUPPORT
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
INTEGRATED/HYBRID OPERATING ROOM MARKET BY EQUIPMENT
- DIAGNOSTIC IMAGING SYSTEMS
- ANGIOGRAPHY SYSTEMS
- MRI SYSTEMS
- CT SCANNERS
- OTHER DIAGNOSTIC IMAGING SYSTEMS
- OPERATING ROOM FIXTURES
- OPERATING TABLES
- OPERATING ROOM LIGHTS
- SURGICAL BOOMS
- OTHER OPERATING ROOM FIXTURES
- OTHER EQUIPMENT
- DIAGNOSTIC IMAGING SYSTEMS
INTEGRATED/HYBRID OPERATING ROOM MARKET BY APPLICATION
- CARDIOVASCULAR SURGERY
- NEUROSURGERY
- THORACIC SURGERY
- ORTHOPEDIC SURGERY
- OTHER APPLICATIONS
INTEGRATED/HYBRID OPERATING ROOM MARKET BY END-USER
- HOSPITAL AND SURGICAL CENTERS
- OUTPATIENT SURGICAL CENTERS
- OTHER END-USERS
GEOGRAPHICAL ANALYSIS
- NORTH AMERICA
- MARKET SIZE & ESTIMATES
- NORTH AMERICA MARKET DRIVERS
- NORTH AMERICA MARKET CHALLENGES
- KEY PLAYERS IN NORTH AMERICA INTEGRATED/HYBRID OPERATING ROOM MARKET
- COUNTRY ANALYSIS
- UNITED STATES
- UNITED STATES MARKET SIZE & OPPORTUNITIES
- CANADA
- CANADA MARKET SIZE & OPPORTUNITIES
- UNITED STATES
- NORTH AMERICA
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- ARTHREX INC
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- BARCO NV
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- CARL ZEISS MEDITEC GROUP
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- CONMED CORPORATION
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- DRAGERWERK AG & CO KGAA
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- FISHER & PAYKEL HEALTHCARE CORPORATION LIMITED
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- GE HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- GETINGE AB
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- INTEGRA LIFESCIENCES HOLDINGS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- KARL STORZ SE & CO KG
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- KONINKLIJKE PHILIPS N.V
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- OLYMPUS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- SIEMENS AG
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- SMITH & NEPHEW PLC
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- STRYKER CORPORATION
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- ARTHREX INC
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – INTEGRATED/HYBRID OPERATING ROOM
TABLE 2: INTEGRATED/HYBRID OPERATING ROOM MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY EQUIPMENT, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY EQUIPMENT, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: MARKET BY DIAGNOSTIC IMAGING SYSTEMS, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: MARKET BY DIAGNOSTIC IMAGING SYSTEMS, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: MARKET BY OPERATING ROOM FIXTURES, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: MARKET BY OPERATING ROOM FIXTURES, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: MARKET BY APPLICATION, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: MARKET BY APPLICATION, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: MARKET BY END-USER, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 12: MARKET BY END-USER, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 13: NORTH AMERICA MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 14: NORTH AMERICA MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 15: KEY PLAYERS OPERATING IN THE NORTH AMERICAN MARKET
TABLE 16: LIST OF MERGERS & ACQUISITIONS
TABLE 17: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 18: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 19: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: KEY MARKET TRENDS
FIGURE 2: PORTER’S FIVE FORCES ANALYSIS
FIGURE 3: GROWTH PROSPECT MAPPING FOR NORTH AMERICA
FIGURE 4: MARKET MATURITY ANALYSIS
FIGURE 5: MARKET CONCENTRATION ANALYSIS
FIGURE 6: VALUE CHAIN ANALYSIS
FIGURE 7: KEY BUYING CRITERIA
FIGURE 8: SEGMENT GROWTH POTENTIAL, BY EQUIPMENT, IN 2025
FIGURE 9: DIAGNOSTIC IMAGING SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY DIAGNOSTIC IMAGING SYSTEMS, IN 2025
FIGURE 11: ANGIOGRAPHY SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: MRI SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: CT SCANNERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 14: OTHER DIAGNOSTIC IMAGING SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: OPERATING ROOM FIXTURES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: SEGMENT GROWTH POTENTIAL, BY OPERATING ROOM FIXTURES, IN 2025
FIGURE 17: OPERATING TABLES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: OPERATING ROOM LIGHTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: SURGICAL BOOMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: OTHER OPERATING ROOM FIXTURES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: OTHER EQUIPMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: SEGMENT GROWTH POTENTIAL, BY APPLICATION, IN 2025
FIGURE 23: CARDIOVASCULAR SURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: NEUROSURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: THORACIC SURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: ORTHOPEDIC SURGERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: OTHER APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: SEGMENT GROWTH POTENTIAL, BY END-USER, IN 2025
FIGURE 29: HOSPITAL AND SURGICAL CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: OUTPATIENT SURGICAL CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: OTHER END-USERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 32: NORTH AMERICA INTEGRATED/HYBRID OPERATING ROOM MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 33: UNITED STATES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 34: CANADA MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-
EUROPE SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
NORTH AMERICA SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
SPAIN ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
MEXICO ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
ITALY ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
AUSTRALIA ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
BRAZIL ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034