India Food Delivery Platform Fee Structures Market by Delivery Mode (Platform-To-Consumer Delivery, Restaurant-To-Consumer Delivery), Market by Payment Method (Online Payment, Cash On Delivery (COD)), Market by Revenue Model (Commission-Based Revenue, Delivery Fee-Based Revenue, Advertising & Promotion Revenue, Subscription-Based Revenue), Market by Product Type (Meal Delivery, Grocery Delivery, Meal Kit Delivery, Alcohol Delivery, Other Product Types), by Geography
INDIA FOOD DELIVERY PLATFORM FEE STRUCTURES MARKET OVERVIEW
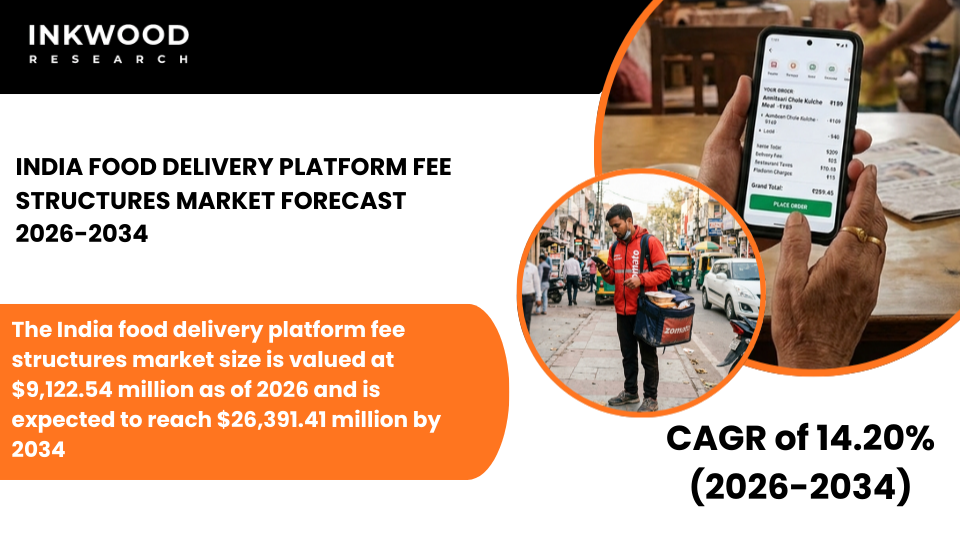
The India food delivery platform fee structures market size is valued at $9,122.54 million as of 2026 and is expected to reach $26,391.41 million by 2034, progressing with a CAGR of 14.20% during the forecast years, 2026-2034.
MARKET INSIGHTS
India is the fastest-growing major market for food delivery platform fee structures globally, fueled by a uniquely powerful combination of a young, digitally native population, rapidly expanding smartphone adoption, and the widespread penetration of the Unified Payments Interface (UPI), India’s government-backed real-time digital payment infrastructure. UPI has fundamentally transformed how Indian consumers transact online, removing friction from the food ordering process and enabling platforms to scale online payment adoption even among first-time digital commerce users.
According to the Ministry of Electronics and Information Technology (MeitY), India’s digital economy has been growing at an exceptional pace, with internet user penetration expanding steadily across both metro and non-metro geographies. This broad digital foundation has created fertile ground for food delivery platform pricing growth, as more restaurants across Tier-1, Tier-2, and Tier-3 cities turn to online food delivery platforms to access consumers they could not previously reach.
The regulatory and policy landscape in India is playing an increasingly shaping role in the food delivery platform fee structure market. The Competition Commission of India (CCI) has actively examined the practices of major online food ordering platforms, particularly around food delivery commission rates, search ranking algorithms, and the exclusivity arrangements that platforms impose on restaurant partners.
The CCI’s ongoing scrutiny signals a broader intent to ensure that food delivery platform pricing models remain competitive and do not unfairly disadvantage small and independent restaurant operators. Separately, India’s evolving gig economy policy framework, guided by the Ministry of Labour and Employment, is expected to impose greater social security obligations on platforms that rely on contract-based delivery workers, which could add upward pressure to food delivery service charges over the forecast period.
For platforms, proactively engaging with these regulatory developments will be critical to maintaining merchant relationships and sustaining platform growth. Despite these regulatory considerations, India’s food delivery marketplace presents an unmatched growth opportunity, particularly as platforms accelerate their expansion beyond large metros into smaller cities and towns where restaurant delivery commission revenue is largely untapped.
The rapid rise of quick commerce, led by platforms such as Swiggy Instamart and Zepto, is actively diversifying food delivery platform business models in India, adding grocery and convenience delivery fee income streams alongside traditional restaurant commissions. For investors and vendors, India’s 14.20% CAGR, the highest among all major markets covered in this study, signals the scale of opportunity available to those who can navigate price-sensitive consumer behaviour, infrastructure variability, and regulatory evolution with agility and strategic precision. These factors, together, are set to boost the food delivery platform fee structures market growth in India during the forecast period.
To Know More About This Report, Request a Free Sample Copy
SEGMENTATION ANALYSIS
The India food delivery platform fee structures market is segmented by delivery mode, payment method, revenue model, and product type. The payment method segment is further categorized into online payment and cash on delivery (COD).
Online payment is the fastest-growing sub-segment within the payment method segment of the India food delivery platform fee structures market, driven primarily by the extraordinary scale and accessibility of India’s UPI ecosystem. Unlike many other markets where online payment adoption was gradual, India’s government-backed digital payment infrastructure has accelerated the shift away from cash on delivery at a pace unmatched globally, enabling food delivery platforms to reduce cash-handling costs and streamline settlement processes with restaurant partners.
For online food delivery platforms, higher online payment adoption directly improves operational efficiency and reduces the risk of order cancellations associated with cash transactions, making it a structurally important enabler of food delivery platform fee structure optimisation. Platforms such as Zomato and Swiggy have further embedded online payment into their ecosystems by integrating UPI, credit and debit cards, digital wallets, and buy-now-pay-later options at checkout.
This is creating a seamless and frictionless ordering experience that reinforces consumer retention and supports higher order frequencies. As internet penetration continues to deepen across Tier-2 and Tier-3 cities, online payment adoption is expected to expand further, strengthening the revenue collection infrastructure that underpins India’s food delivery platform commission and fee monetisation models throughout the forecast period.
COMPETITIVE INSIGHTS
Some of the top players operating in the India food delivery platform fee structures market include Zomato (Eternal), Swiggy, Magicpin, Zepto, etc.
Zomato, now operating under the parent entity Eternal Limited and listed on the National Stock Exchange (NSE) of India, is the country’s largest online food ordering platform by revenue and one of the most prominent food delivery marketplace operators in Asia. Headquartered in Gurugram, Haryana, Zomato connects millions of consumers with restaurant partners across hundreds of Indian cities, operating a platform-to-consumer delivery model supported by a large network of delivery partners.
The company’s food delivery platform fee structure encompasses restaurant delivery commissions, consumer-facing delivery and platform fees, and in-app advertising products, while its Zomato Gold subscription programme adds a recurring subscription-based revenue stream, collectively reflecting a well-diversified food delivery platform business model built for scale across India’s highly varied geographic and consumer landscape.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Delivery Mode, Payment Method, Revenue Model, Product Type |
| Country Analyzed | India |
| Companies Analyzed | Zomato (Eternal), Swiggy, Magicpin, EatSure, Domino’s, Dunzo, Zepto |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE, SHARE & ESTIMATES
- MARKET OVERVIEW
- SCOPE OF STUDY
- MAJOR MARKET FINDINGS
- THE INDIA FOOD DELIVERY PLATFORM FEE STRUCTURES MARKET IS CHARACTERIZED BY RAPID DIGITAL ADOPTION AND STRONG COMPETITION BETWEEN MAJOR DELIVERY PLATFORMS
- PLATFORMS GENERATE REVENUE THROUGH COMMISSIONS, DELIVERY FEES, ADVERTISING, AND PREMIUM SUBSCRIPTION SERVICES
- THE MARKET IS EXPERIENCING RAPID EXPANSION INTO TIER-2 AND TIER-3 CITIES DRIVEN BY GROWING INTERNET PENETRATION
- DIGITAL PAYMENT SYSTEMS AND UPI ADOPTION ARE SIGNIFICANTLY INFLUENCING PLATFORM PRICING AND PAYMENT MODELS
MARKET DYNAMICS
- KEY DRIVERS
- THE RISING MIDDLE CLASS AND INCREASING DEMAND FOR CONVENIENT FOOD DELIVERY SERVICES ARE DRIVING MARKET EXPANSION
- HIGH SMARTPHONE PENETRATION AND AFFORDABLE MOBILE DATA ARE SUPPORTING APP-BASED FOOD ORDERING
- THE GROWING NUMBER OF RESTAURANTS JOINING ONLINE MARKETPLACES IS EXPANDING PLATFORM COMMISSION REVENUE
- PLATFORMS ARE EXPANDING INTO QUICK COMMERCE AND GROCERY DELIVERY TO DIVERSIFY REVENUE STREAMS
- KEY RESTRAINTS
- PRICE-SENSITIVE CONSUMERS AND HIGH DISCOUNT EXPECTATIONS ARE REDUCING PROFIT MARGINS FOR DELIVERY PLATFORMS
- RESTAURANT ASSOCIATIONS HAVE EXPRESSED CONCERNS ABOUT HIGH COMMISSION RATES AND PLATFORM DEPENDENCE
- LOGISTICS CHALLENGES IN NON-METRO AREAS CAN INCREASE DELIVERY COSTS AND AFFECT SERVICE QUALITY
- REGULATORY DISCUSSIONS REGARDING PLATFORM FEES AND GIG WORKER PROTECTIONS MAY IMPACT OPERATING MODELS
- KEY DRIVERS
STRATEGIC MARKET ANALYTICS
- GROWTH METRICS
- TAM, SAM & SOM OPPORTUNITY ANALYSIS
- EMERGING MARKET TRENDS & PARADIGM SHIFTS
- SUBSCRIPTION-BASED DELIVERY PROGRAMS WITH DISCOUNTED FEES ARE BECOMING INCREASINGLY POPULAR
- PLATFORMS ARE EXPANDING ADVERTISING AND PROMOTIONAL TOOLS TO HELP RESTAURANTS INCREASE VISIBILITY
- THE RAPID GROWTH OF QUICK COMMERCE SERVICES IS DRIVING NEW PRICING MODELS FOR DELIVERY FEES
- AI-BASED ORDER MANAGEMENT AND ROUTE OPTIMIZATION ARE IMPROVING DELIVERY SPEED AND COST EFFICIENCY
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- PESTLE ANALYSIS
- POLITICAL
- ECONOMIC
- SOCIAL LANDSCAPE
- TECHNOLOGY
- LEGAL
- ENVIRONMENTAL
- GROWTH OPPORTUNITY MAPPING & HEATMAP
- GROWTH PROSPECT MAPPING FOR INDIA
- MARKET MATURITY & LIFECYCLE ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- GROWTH METRICS
FOOD DELIVERY PLATFORM FEE STRUCTURES VALUE CHAIN & DECISION FRAMEWORK
- VALUE CHAIN ANALYSIS
- MERCHANT ONBOARDING & FEE CONTRACTING
- PLATFORM TECHNOLOGY & FEE ENGINE
- FEE STRUCTURE DESIGN & MONETIZATION
- LOGISTICS & DELIVERY COST MANAGEMENT
- MARKETING, VISIBILITY & DEMAND GENERATION
- SETTLEMENT, ANALYTICS & REGULATORY COMPLIANCE
- KEY BUYING CRITERIA
- COMMISSION LEVELS & FEE TRANSPARENCY
- IMPACT ON MERCHANT PROFITABILITY
- FLEXIBILITY OF FEE MODELS
- DEMAND REACH & ORDER POTENTIAL
- PROMOTION EFFECTIVENESS & VISIBILITY ROI
- SETTLEMENT RELIABILITY & PLATFORM CREDIBILITY
- PRICING MODELS, FEE STRUCTURES & TAKE RATE OPTIMIZATION STRATEGIES
- REGULATORY & POLICY LANDSCAPE ANALYSIS
- VALUE CHAIN ANALYSIS
FOOD DELIVERY PLATFORM FEE STRUCTURES MARKET BY DELIVERY MODE
- PLATFORM-TO-CONSUMER DELIVERY
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- RESTAURANT-TO-CONSUMER DELIVERY
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PLATFORM-TO-CONSUMER DELIVERY
FOOD DELIVERY PLATFORM FEE STRUCTURES MARKET BY PAYMENT METHOD
- ONLINE PAYMENT
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- CASH ON DELIVERY (COD)
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ONLINE PAYMENT
FOOD DELIVERY PLATFORM FEE STRUCTURES MARKET BY REVENUE MODEL
- COMMISSION-BASED REVENUE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- DELIVERY FEE-BASED REVENUE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ADVERTISING & PROMOTION REVENUE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SUBSCRIPTION-BASED REVENUE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- COMMISSION-BASED REVENUE
FOOD DELIVERY PLATFORM FEE STRUCTURES MARKET BY PRODUCT TYPE
- MEAL DELIVERY
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- GROCERY DELIVERY
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- MEAL KIT DELIVERY
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ALCOHOL DELIVERY
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER PRODUCT TYPES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- MEAL DELIVERY
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPETITOR POSITIONING & DIFFERENTIATION MAP
- COMPANY PROFILES
- ZOMATO (ETERNAL)
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- SWIGGY
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- MAGICPIN
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- EATSURE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- DOMINO’S
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- DUNZO
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- ZEPTO
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- ZOMATO (ETERNAL)
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – FOOD DELIVERY PLATFORM FEE STRUCTURES
TABLE 2: PRICING MODELS, FEE STRUCTURES & TAKE RATE OPTIMIZATION STRATEGIES
TABLE 3: REGULATORY & POLICY LANDSCAPE ANALYSIS
TABLE 4: MARKET BY DELIVERY MODE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 5: MARKET BY DELIVERY MODE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 6: MARKET BY PAYMENT METHOD, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 7: MARKET BY PAYMENT METHOD, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 8: MARKET BY REVENUE MODEL, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 9: MARKET BY REVENUE MODEL, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 10: MARKET BY PRODUCT TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 11: MARKET BY PRODUCT TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 12: KEY PLAYERS OPERATING IN THE INDIAN MARKET
TABLE 13: LIST OF MERGERS & ACQUISITIONS
TABLE 14: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 15: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 16: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR INDIA
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY DELIVERY MODE, IN 2025
FIGURE 11: PLATFORM-TO-CONSUMER DELIVERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: RESTAURANT-TO-CONSUMER DELIVERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY PAYMENT METHOD, IN 2025
FIGURE 14: ONLINE PAYMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: CASH ON DELIVERY (COD) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: SEGMENT GROWTH POTENTIAL, BY REVENUE MODEL, IN 2025
FIGURE 17: COMMISSION-BASED REVENUE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: DELIVERY FEE-BASED REVENUE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: ADVERTISING & PROMOTION REVENUE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: SUBSCRIPTION-BASED REVENUE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: SEGMENT GROWTH POTENTIAL, BY PRODUCT TYPE, IN 2025
FIGURE 22: MEAL DELIVERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: GROCERY DELIVERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: MEAL KIT DELIVERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: ALCOHOL DELIVERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: OTHER PRODUCT TYPES MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
LATIN AMERICA FACIAL RECOGNITION MARKET FORECAST 2019-2028
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

JAPAN AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

INDIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034