India Contrast Ultrasound Market by Product (Equipment, Contrast Agents) Market by Type (Non-Targeted, Targeted) Market by Application (Diagnostic Applications, Therapeutic Applications) Market by End Use (Hospitals, Clinics, Ambulatory Diagnostic Centers), by Geography
INDIA CONTRAST ULTRASOUND MARKET OVERVIEW
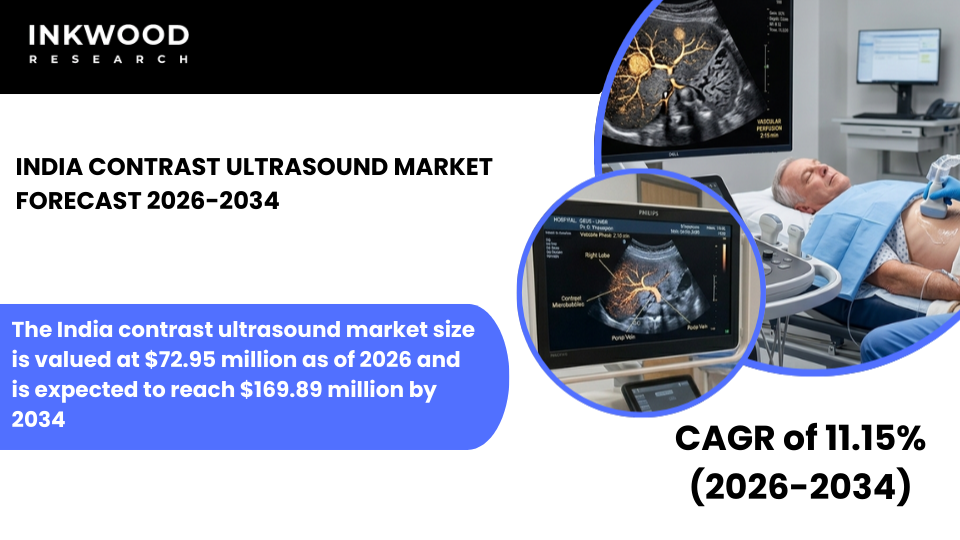
The India contrast ultrasound market size is valued at $72.95 million as of 2026 and is expected to reach $169.89 million by 2034, progressing with a CAGR of 11.15% during the forecast years, 2026-2034.
India’s contrast ultrasound market is experiencing rapid expansion driven by rising healthcare expenditure, growing burden of chronic diseases, and increasing penetration of advanced diagnostic technologies across urban and tier-2 cities. The country benefits from a large and growing patient population requiring accessible and cost-effective imaging solutions, positioning enhanced ultrasound as an attractive alternative to more expensive cross-sectional imaging modalities.
The rising incidence of liver diseases and cardiovascular conditions is creating a sustained clinical need for diagnostic applications that enable early detection, accurate characterization, and treatment monitoring. According to the Indian Council of Medical Research, cancer incidence is projected to reach 15.7 lakh new cases annually by 2025, with liver cancer representing a significant component of the disease burden.
To Know More About This Report, Request a Free Sample Copy
Additionally, cardiovascular disease accounts for more than 25% of total deaths in India, creating substantial demand for cardiac imaging services, where contrast enhanced ultrasound provides critical diagnostic information. The rapid expansion of private diagnostic centers and corporate hospital chains across major metropolitan areas is driving the procurement of premium ultrasound systems equipped with contrast-enhanced imaging capabilities, artificial intelligence integration, and cloud-based image management.
Government initiatives to strengthen public hospital infrastructure through programs such as Ayushman Bharat and Pradhan Mantri Swasthya Suraksha Yojana are supporting equipment procurement in government medical colleges and district hospitals, thereby expanding access beyond traditional urban centers. Moreover, increasing awareness among radiologists and cardiologists about the benefits of real-time perfusion imaging is encouraging clinical adoption in oncology and cardiology applications, particularly for characterizing focal liver lesions and assessing myocardial perfusion abnormalities.
The cost advantage of ultrasound procedures compared to MRI and CT scans makes enhanced ultrasound particularly attractive in price-sensitive markets where patients often bear significant out-of-pocket healthcare expenses. Furthermore, growing insurance coverage through government-sponsored health protection schemes and private health insurance plans is improving patient affordability and reducing financial barriers to accessing advanced diagnostic services. These factors, in turn, are set to boost the contrast ultrasound market growth in India during the forecast period.
The India contrast ultrasound market is segmented into product, type, application, and end use. The product segment is further categorized into equipment and contrast agents.
The contrast agents segment represents a critical component of the India contrast ultrasound market, encompassing the injectable microbubble-based pharmaceutical products that enable enhanced visualization during ultrasound procedures. This segment includes both non-targeted and targeted formulations designed to improve diagnostic accuracy across cardiology, hepatology, radiology, and oncology applications.
Contrast agents consist of gas-filled microspheres with stabilizing shells that reflect ultrasound waves to produce enhanced images of blood flow patterns, tissue perfusion, and vascular abnormalities that would otherwise be difficult or impossible to visualize with conventional grayscale ultrasound. The segment faces unique challenges in the Indian market related to regulatory requirements, import dependencies, and price sensitivities that influence adoption patterns across different healthcare settings.
Major international manufacturers dominate the contrast agents segment through established distribution partnerships with hospitals, diagnostic centers, and medical device distributors operating across metropolitan cities and regional hubs. However, dependence on imported formulations creates supply chain vulnerabilities and pricing pressures that can impact market accessibility, particularly in smaller cities and rural areas where healthcare budgets are more constrained.
Regulatory oversight by the Central Drugs Standard Control Organisation ensures that contrast agents meet safety and efficacy standards before receiving marketing approval, though lengthy approval processes can delay the introduction of newer formulations and limit the range of products available to Indian physicians. The segment benefits from increasing clinical validation through research studies conducted at leading academic medical centers such as the All India Institute of Medical Sciences and Tata Memorial Hospital, where contrast ultrasound is being evaluated for expanded indications beyond traditional cardiac and liver imaging.
Price negotiations between manufacturers and large hospital networks or group purchasing organizations are helping to improve affordability through volume-based discounting arrangements that make contrast agents more accessible to institutions serving high patient volumes. Additionally, the segment is witnessing growing interest in therapeutic applications where microbubbles serve as carriers for targeted drug delivery or facilitate ultrasound-mediated therapies such as thrombolysis and tumor ablation, though these applications remain largely investigational within the Indian market.
Government efforts to promote domestic pharmaceutical manufacturing under the Make in India initiative may eventually encourage local production of ultrasound contrast agents. This can potentially reduce import dependence and improve supply reliability while creating opportunities for more competitive pricing structures that benefit both healthcare providers and patients.
Some of the top players operating in the India contrast ultrasound market include GE Healthcare, Siemens Healthineers AG, Koninklijke Philips NV, and Trivitron Healthcare Pvt Ltd, among others.
Trivitron Healthcare Pvt Ltd, headquartered in Chennai, is India’s leading domestic medical technology company specializing in medical devices, diagnostic equipment, and laboratory solutions. The company maintains a diversified product portfolio serving hospitals, diagnostic centers, and ambulatory surgical centers across India and international markets in Asia, Africa, and Latin America.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Product, Type, Application, End Use |
| Country Analyzed | India |
| Companies Analyzed | GE HealthCare, Bracco Imaging SpA, Lantheus Holdings Inc, Siemens Healthineers AG, Koninklijke Philips NV, Bayer AG, Guerbet, Canon Medical Systems Corporation, Shenzhen Mindray Bio-Medical Electronics Co Ltd, Esaote SpA, FUJIFILM Holdings Corporation, Samsung Healthcare, Daiichi Sankyo Company Limited, Trivitron Healthcare Pvt Ltd, SuperSonic Imagine SA |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- RAPID EXPANSION OF PRIVATE DIAGNOSTIC CENTERS IS DRIVING DEMAND FOR ADVANCED ULTRASOUND TECHNOLOGIES
- URBAN TERTIARY CARE HOSPITALS ACCOUNT FOR THE MAJORITY OF CONTRAST ENHANCED ULTRASOUND PROCEDURES
- GROWING BURDEN OF LIVER DISEASES AND CARDIOVASCULAR CONDITIONS IS STRENGTHENING CLINICAL NEED
- MARKET GROWTH IS CONCENTRATED IN METROPOLITAN CITIES WITH DEVELOPING PENETRATION IN TIER TWO LOCATIONS
MARKET DYNAMICS
- KEY DRIVERS
- RISING HEALTHCARE EXPENDITURE AND INSURANCE COVERAGE ARE IMPROVING ACCESS TO ADVANCED DIAGNOSTICS
- INCREASING AWARENESS AMONG RADIOLOGISTS ABOUT THE BENEFITS OF REAL TIME PERFUSION IMAGING IS BOOSTING UTILIZATION
- COST ADVANTAGE OF ULTRASOUND COMPARED TO MRI AND CT IS ENCOURAGING ADOPTION
- GOVERNMENT INITIATIVES TO STRENGTHEN PUBLIC HOSPITAL INFRASTRUCTURE ARE SUPPORTING EQUIPMENT PROCUREMENT
- KEY RESTRAINTS
- LIMITED REIMBURSEMENT FRAMEWORK FOR CONTRAST PROCEDURES IN PUBLIC FACILITIES MAY SLOW ADOPTION
- PRICE SENSITIVITY AMONG PATIENTS CAN CONSTRAIN MARKET EXPANSION
- SHORTAGE OF TRAINED SONOGRAPHERS IN RURAL REGIONS RESTRICTS PROCEDURE VOLUMES
- REGULATORY AND IMPORT DEPENDENCY FOR CONTRAST AGENTS MAY IMPACT SUPPLY CONSISTENCY
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- INCREASING INSTALLATION OF PREMIUM ULTRASOUND SYSTEMS IN CORPORATE HOSPITAL CHAINS IS ELEVATING MARKET VALUE
- GROWTH OF DAY CARE AND AMBULATORY DIAGNOSTIC CENTERS IS EXPANDING ACCESS TO CONTRAST IMAGING
- RISING FOCUS ON EARLY CANCER DETECTION IS DRIVING CLINICAL RESEARCH AND TRAINING PROGRAMS
- ADOPTION OF PORTABLE AND HANDHELD ULTRASOUND DEVICES IS IMPROVING REACH IN SEMI-URBAN AREAS
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR INDIA
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SUPPLIERS
- CONTRAST AGENT MANUFACTURERS
- ULTRASOUND OEMS
- DISTRIBUTION PARTNERS
- HOSPITAL PROCUREMENT
- END-USER FACILITIES
- KEY BUYING CRITERIA
- IMAGE CLARITY
- SAFETY PROFILE
- REGULATORY APPROVAL
- COST EFFECTIVENESS
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
CONTRAST ULTRASOUND MARKET BY PRODUCT
- EQUIPMENT
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- CONTRAST AGENTS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- EQUIPMENT
CONTRAST ULTRASOUND MARKET BY TYPE
- NON-TARGETED
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- TARGETED
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- NON-TARGETED
CONTRAST ULTRASOUND MARKET BY APPLICATION
- DIAGNOSTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- THERAPEUTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DIAGNOSTIC APPLICATIONS
CONTRAST ULTRASOUND MARKET BY END USE
- HOSPITALS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- CLINICS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- AMBULATORY DIAGNOSTIC CENTERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- HOSPITALS
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- GE HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- BRACCO IMAGING SPA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- LANTHEUS HOLDINGS INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SIEMENS HEALTHINEERS AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- KONINKLIJKE PHILIPS NV
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- BAYER AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GUERBET
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- CANON MEDICAL SYSTEMS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ESAOTE SPA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- FUJIFILM HOLDINGS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SAMSUNG HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- DAIICHI SANKYO COMPANY LIMITED
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- TRIVITRON HEALTHCARE PVT LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SUPERSONIC IMAGINE SA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GE HEALTHCARE
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – CONTRAST ULTRASOUND
TABLE 2: CONTRAST ULTRASOUND MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY PRODUCT, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY PRODUCT, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: MARKET BY TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: MARKET BY TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: MARKET BY APPLICATION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: MARKET BY APPLICATION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: MARKET BY END USE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: MARKET BY END USE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: KEY PLAYERS OPERATING IN THE INDIAN MARKET
TABLE 12: LIST OF MERGERS & ACQUISITIONS
TABLE 13: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 14: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 15: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR INDIA
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY PRODUCT, IN 2025
FIGURE 11: EQUIPMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: CONTRAST AGENTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY TYPE, IN 2025
FIGURE 14: NON-TARGETED MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: TARGETED MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: SEGMENT GROWTH POTENTIAL, BY APPLICATION, IN 2025
FIGURE 17: DIAGNOSTIC APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: THERAPEUTIC APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: SEGMENT GROWTH POTENTIAL, BY END USE, IN 2025
FIGURE 20: HOSPITALS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: CLINICS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: AMBULATORY DIAGNOSTIC CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
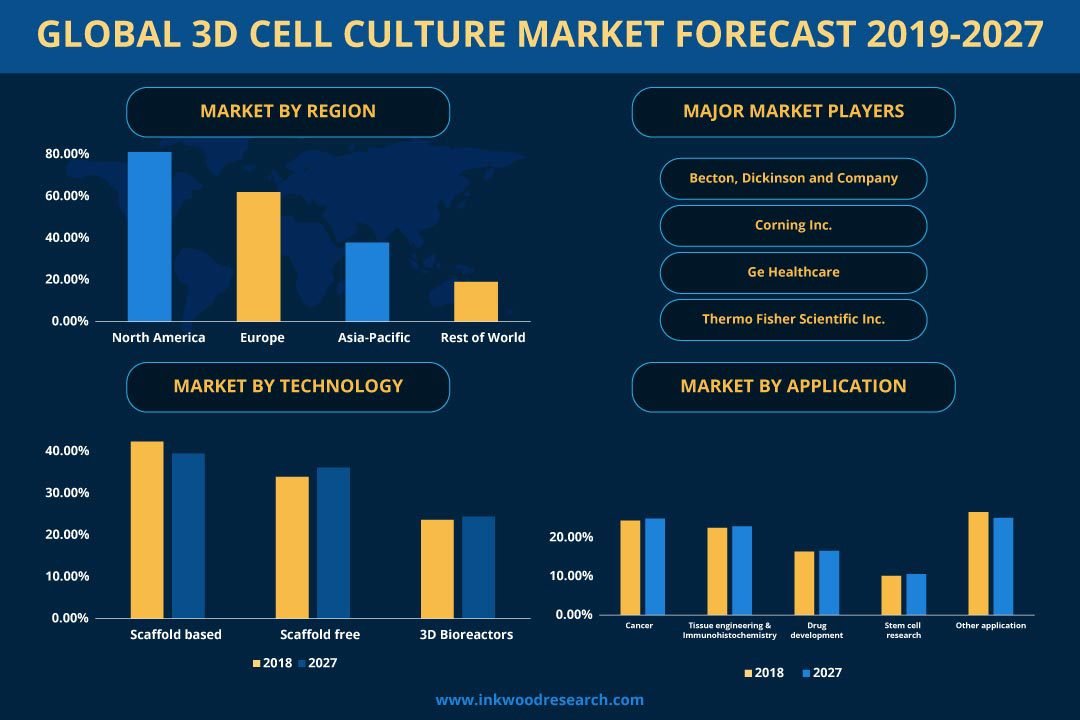
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
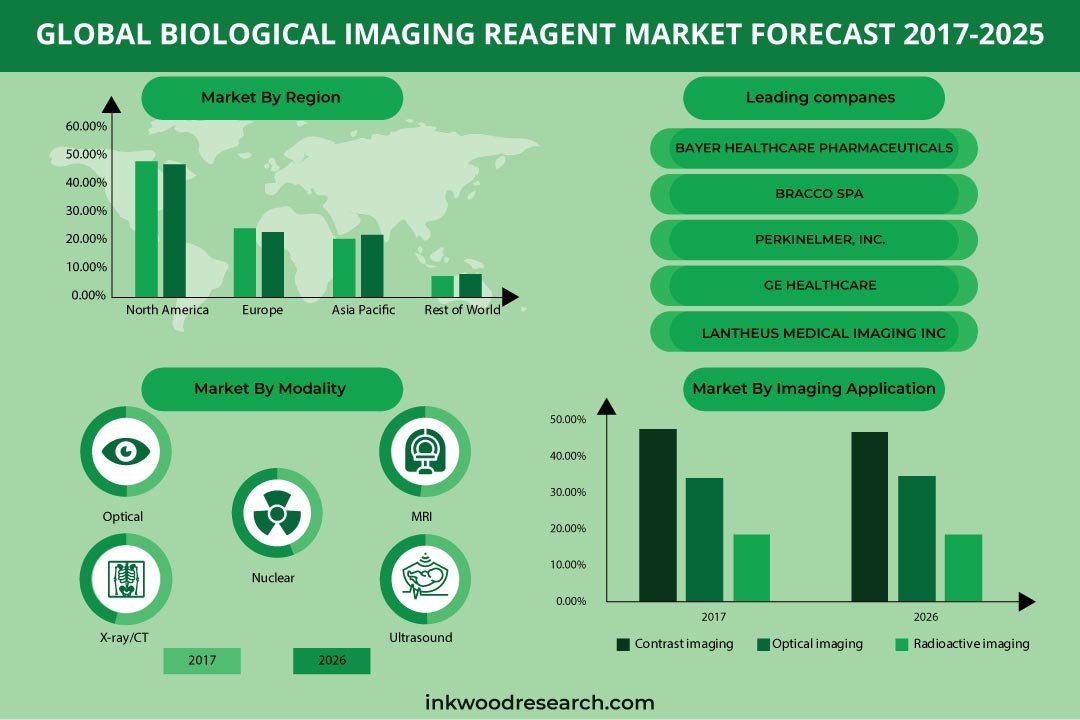
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034