India Cardiovascular Ultrasound Market by Device Display (Color Display Systems, Black & White (B/W) Display Systems) Market by Technology (2D Ultrasound, 3D & 4D Ultrasound, Doppler Imaging) Market by Application (Diagnostic Applications, Therapeutic Applications) Market by Type (Transthoracic Echocardiogram, Transesophageal Echocardiogram, Stress Echocardiogram, Fetal Echocardiography, Other Types) Market by End-User (Hospitals, Diagnostic Centers, Ambulatory Care Centers, Other End-Users), by Geography
INDIA CARDIOVASCULAR ULTRASOUND MARKET OVERVIEW
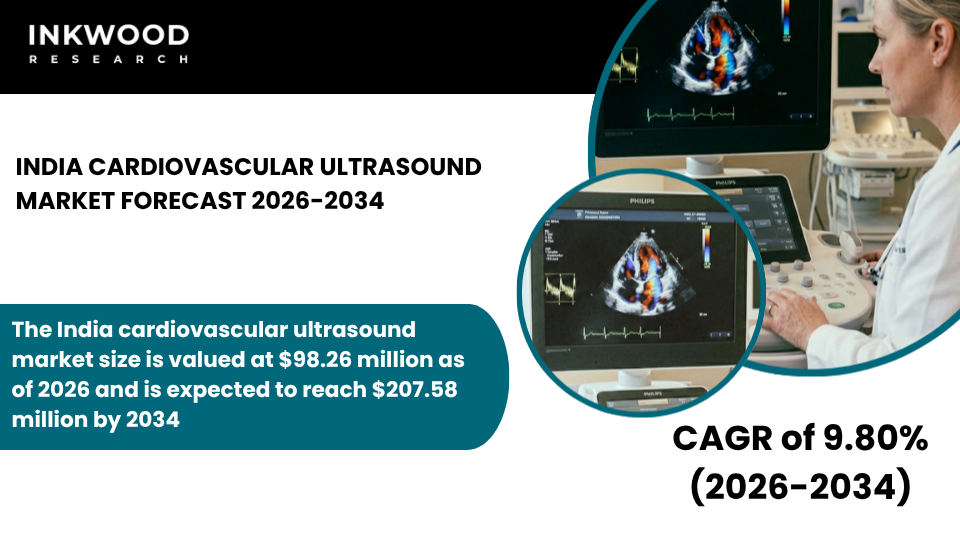
The India cardiovascular ultrasound market size is valued at $98.26 million as of 2026 and is expected to reach $207.58 million by 2034, progressing with a CAGR of 9.80% during the forecast years, 2026–2034.
India is a key emergin markets for cardiovascular ultrasound globally, underpinned by a rapidly escalating cardiovascular disease burden, a healthcare infrastructure that is expanding at scale, and a population of 1.4 billion where cardiac risk factors are growing at an alarming pace. According to the World Health Organization’s India country office, cardiovascular diseases are the leading cause of death in India.
The Ministry of Health and Family Welfare further reports that cardiovascular diseases accounted for 28.1% of all deaths in the country. A meta-analysis funded by the Indian Council of Medical Research (ICMR), published in 2025 and covering studies from 2000 to 2024, found the pooled prevalence of CVD among Indian adults to be 11%, with higher rates observed among women (14%) and urban populations (12%).
India also holds one of the world’s highest rates of acute coronary syndrome and ST-elevation myocardial infarction, creating sustained and urgent clinical demand for early, non-invasive cardiac diagnostics. Against this backdrop, the transthoracic echocardiogram remains the most widely used frontline tool for detecting and managing cardiovascular conditions across India’s hospital and diagnostic center network.
To Know More About This Report, Request a Free Sample Copy
India’s policy environment is increasingly aligned with cardiovascular disease control and diagnostic capacity building. The government’s Ayushman Bharat Pradhan Mantri Jan Arogya Yojana (PM-JAY), the world’s largest government-funded health assurance scheme, provides health coverage of up to ₹5 lakh per family per year for secondary and tertiary care, including cardiac procedures and diagnostics, to over 12 crore poor and vulnerable families, as confirmed by the National Health Authority of India.
Cardiac conditions represent a disproportionately high share of PM-JAY expenditure. According to research, while cardiac-related claims accounted for roughly 5% of all PM-JAY claims between 2018 and 2020, they consumed approximately 26% of total scheme expenditure, reflecting the clinical weight of heart disease in India’s public health system and the government’s commitment to funding cardiac care access.
In September 2024, the Union Cabinet further expanded PM-JAY coverage to all senior citizens above the age of 70, regardless of socioeconomic status, extending cardiac care access to an age group at disproportionately high cardiovascular risk. These policy actions are creating a more structured and government-supported demand environment for cardiac ultrasound systems across public hospitals nationwide.
Beyond the public sector, India’s private multispecialty hospital segment is a strong and accelerating demand driver for advanced cardiovascular imaging. Hospital chains across Tier 1 and major Tier 2 cities are actively investing in high-end cardiac ultrasound systems, including 3D and 4D platforms and AI-assisted echocardiography, to attract cardiac patients and establish centers of cardiac excellence.
At the same time, the government’s push to improve healthcare access in rural and semi-urban regions is driving demand for portable and point-of-care cardiac ultrasound systems that can function in facilities with limited specialist support. These intersecting forces, high disease burden, expanding government insurance coverage, growing private sector investment, and rural healthcare outreach, give the India cardiovascular ultrasound market a growth trajectory that is among the steepest in Asia-Pacific over the forecast period.
The India cardiovascular ultrasound market is segmented by device display, technology, application, type, and end-user. The end-user segment is further categorized into hospitals, diagnostic centers, ambulatory care centers, and other end-users.
Hospitals hold the dominant share within the end-user segment of the India cardiovascular ultrasound market, and their commanding position is rooted in both clinical and structural realities of India’s healthcare landscape. Hospitals, both public and private, are the primary sites for cardiac diagnosis and treatment in India. They house the cardiologist workforce, the imaging infrastructure, and the procedural capacity necessary to deploy and fully utilize cardiovascular ultrasound systems, including the full range of transthoracic echocardiogram, transesophageal echocardiogram, and stress echocardiogram procedures.
Public hospitals, particularly those at the district and tertiary levels, are major recipients of government-funded medical equipment under national health programs, making them important volume buyers for cardiac ultrasound systems. Meanwhile, India’s rapidly expanding private multispecialty hospital sector, led by national chains and regional tertiary centers, consistently invests in premium cardiovascular imaging platforms to support high-acuity cardiac programs and attract specialized cardiology talent.
The Ayushman Bharat framework further amplifies hospital-based demand by expanding the insured patient base, making cardiac diagnostic procedures financially accessible to a significantly wider population. For vendors, hospitals represent the most predictable, high-volume, and relationship-driven end-user segment in the India cardiovascular imaging market, one where procurement decisions, replacement cycles, and service contract structures are well-established and commercially favorable.
Some of the top players operating in the India cardiovascular ultrasound market include Samsung Medison Co Ltd, GE HealthCare, Koninklijke Philips NV, Siemens Healthineers AG, Mindray Medical International Limited, etc.
Samsung Medison Co Ltd is a Seoul, South Korea-headquartered medical imaging company and an affiliate of Samsung Electronics, with a growing and strategically important presence in the India cardiovascular ultrasound market. Founded in 1985, Samsung Medison specializes in diagnostic ultrasound systems across multiple clinical disciplines, including cardiovascular imaging, general imaging, and women’s health. Its cardiac ultrasound portfolio spans premium console-based systems to compact point-of-care platforms, with a strong focus on AI integration and workflow automation.
Its most recent major product development is the Samsung R20, an AI-enabled ultrasound system powered by Samsung’s Advanced Imaging Engine. The platform integrates advanced hardware with sophisticated software beamforming to deliver enhanced image clarity and diagnostic precision. Unveiled at RSNA 2025 in Chicago, the R20 offers more than a dozen AI-powered tools for real-time exam guidance, diagnostic assistance, workflow automation, and automated measurements.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Device Display, Technology, Type, End-User |
| Country Analyzed | India |
| Companies Analyzed | FUJIFILM Holdings Corporation (including FUJIFILM SonoSite Inc), GE Healthcare, Hitachi Medical Corporation, Koninklijke Philips NV, Mindray Medical International Limited, Samsung Medison Co Ltd, Siemens Healthineers AG, Zonare Medical Systems (part of Mindray) |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- INDIA IS EXPERIENCING STEADY MARKET GROWTH SUPPORTED BY A LARGE BURDEN OF CARDIOVASCULAR DISEASES
- PRIVATE HOSPITAL CHAINS ACCOUNT FOR A SIGNIFICANT SHARE OF HIGH-END CARDIAC ULTRASOUND INSTALLATIONS
- PRICE COMPETITIVENESS REMAINS A CRITICAL FACTOR IN PURCHASING DECISIONS ACROSS TIER 2 AND TIER 3 CITIES
- PORTABLE ULTRASOUND DEVICES ARE GAINING TRACTION IN RURAL AND SEMI-URBAN HEALTHCARE SETTINGS
MARKET DYNAMICS
- KEY DRIVERS
- INCREASING INCIDENCE OF HYPERTENSION, DIABETES, AND CORONARY ARTERY DISEASE IS DRIVING DEMAND FOR EARLY DIAGNOSTICS
- GOVERNMENT INITIATIVES TO IMPROVE PUBLIC HEALTH INFRASTRUCTURE ARE SUPPORTING EQUIPMENT PROCUREMENT
- RAPID EXPANSION OF PRIVATE MULTISPECIALTY HOSPITALS IS BOOSTING ADOPTION OF ADVANCED IMAGING SYSTEMS
- GROWING AWARENESS OF PREVENTIVE CARDIAC SCREENING IS INCREASING PROCEDURAL VOLUMES
- KEY RESTRAINTS
- LIMITED HEALTHCARE SPENDING PER CAPITA RESTRICTS PROCUREMENT OF PREMIUM SYSTEMS IN PUBLIC HOSPITALS
- SHORTAGE OF TRAINED CARDIAC IMAGING SPECIALISTS AFFECTS SERVICE DELIVERY IN RURAL REGIONS
- HIGH IMPORT DEPENDENCE CONTRIBUTES TO COST VOLATILITY
- UNEQUAL DISTRIBUTION OF HEALTHCARE INFRASTRUCTURE CREATES REGIONAL MARKET DISPARITIES
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- INCREASING DEMAND FOR COMPACT AND BATTERY-OPERATED ULTRASOUND DEVICES
- ADOPTION OF AI-BASED CARDIAC FUNCTION ASSESSMENT TO REDUCE INTERPRETATION VARIABILITY
- STRATEGIC PARTNERSHIPS BETWEEN PRIVATE HOSPITALS AND DIAGNOSTIC CENTERS TO EXPAND CARDIAC SCREENING
- RISING INVESTMENTS IN MEDICAL TRAINING PROGRAMS TO ADDRESS SKILL GAPS
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR INDIA
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SUPPLIERS
- COMPONENT MANUFACTURERS
- SYSTEM INTEGRATORS
- DEVICE MANUFACTURERS
- DISTRIBUTION CHANNELS
- HEALTHCARE PROVIDERS
- AFTER SALES SERVICES
- KEY BUYING CRITERIA
- IMAGE RESOLUTION
- PORTABILITY FEATURES
- TOTAL COST OWNERSHIP
- SERVICE SUPPORT AVAILABILITY
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
CARDIOVASCULAR ULTRASOUND MARKET BY DEVICE DISPLAY
- COLOR DISPLAY SYSTEMS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- BLACK & WHITE (B/W) DISPLAY SYSTEMS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- COLOR DISPLAY SYSTEMS
CARDIOVASCULAR ULTRASOUND MARKET BY TECHNOLOGY
- 2D ULTRASOUND
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- 3D & 4D ULTRASOUND
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DOPPLER IMAGING
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- 2D ULTRASOUND
CARDIOVASCULAR ULTRASOUND MARKET BY APPLICATION
- DIAGNOSTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- THERAPEUTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DIAGNOSTIC APPLICATIONS
CARDIOVASCULAR ULTRASOUND MARKET BY TYPE
- TRANSTHORACIC ECHOCARDIOGRAM
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- TRANSESOPHAGEAL ECHOCARDIOGRAM
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- STRESS ECHOCARDIOGRAM
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- FETAL ECHOCARDIOGRAPHY
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- OTHER TYPES
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- TRANSTHORACIC ECHOCARDIOGRAM
CARDIOVASCULAR ULTRASOUND MARKET BY END-USER
- HOSPITALS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DIAGNOSTIC CENTERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- AMBULATORY CARE CENTERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- OTHER END-USERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- HOSPITALS
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- FUJIFILM HOLDINGS CORPORATION (INCLUDING FUJIFILM SONOSITE INC)
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GE HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- HITACHI MEDICAL CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- KONINKLIJKE PHILIPS NV
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- MINDRAY MEDICAL INTERNATIONAL LIMITED
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SAMSUNG MEDISON CO LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SIEMENS HEALTHINEERS AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ZONARE MEDICAL SYSTEMS (PART OF MINDRAY)
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- FUJIFILM HOLDINGS CORPORATION (INCLUDING FUJIFILM SONOSITE INC)
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – CARDIOVASCULAR ULTRASOUND
TABLE 2: CARDIOVASCULAR ULTRASOUND MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY DEVICE DISPLAY, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY DEVICE DISPLAY, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: MARKET BY TECHNOLOGY, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: MARKET BY TECHNOLOGY, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: MARKET BY TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: MARKET BY TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: MARKET BY END-USER, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: MARKET BY END-USER, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: KEY PLAYERS OPERATING IN THE INDIAN MARKET
TABLE 12: LIST OF MERGERS & ACQUISITIONS
TABLE 13: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 14: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 15: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR INDIA
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY DEVICE DISPLAY, IN 2025
FIGURE 11: COLOR DISPLAY SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: BLACK & WHITE (B/W) DISPLAY SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY TECHNOLOGY, IN 2025
FIGURE 14: 2D ULTRASOUND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: 3D & 4D ULTRASOUND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: DOPPLER IMAGING MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: SEGMENT GROWTH POTENTIAL, BY TYPE, IN 2025
FIGURE 18: TRANSTHORACIC ECHOCARDIOGRAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: TRANSESOPHAGEAL ECHOCARDIOGRAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: STRESS ECHOCARDIOGRAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: FETAL ECHOCARDIOGRAPHY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: OTHER TYPES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: SEGMENT GROWTH POTENTIAL, BY END-USER, IN 2025
FIGURE 24: HOSPITALS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: DIAGNOSTIC CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: AMBULATORY CARE CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: OTHER END-USERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
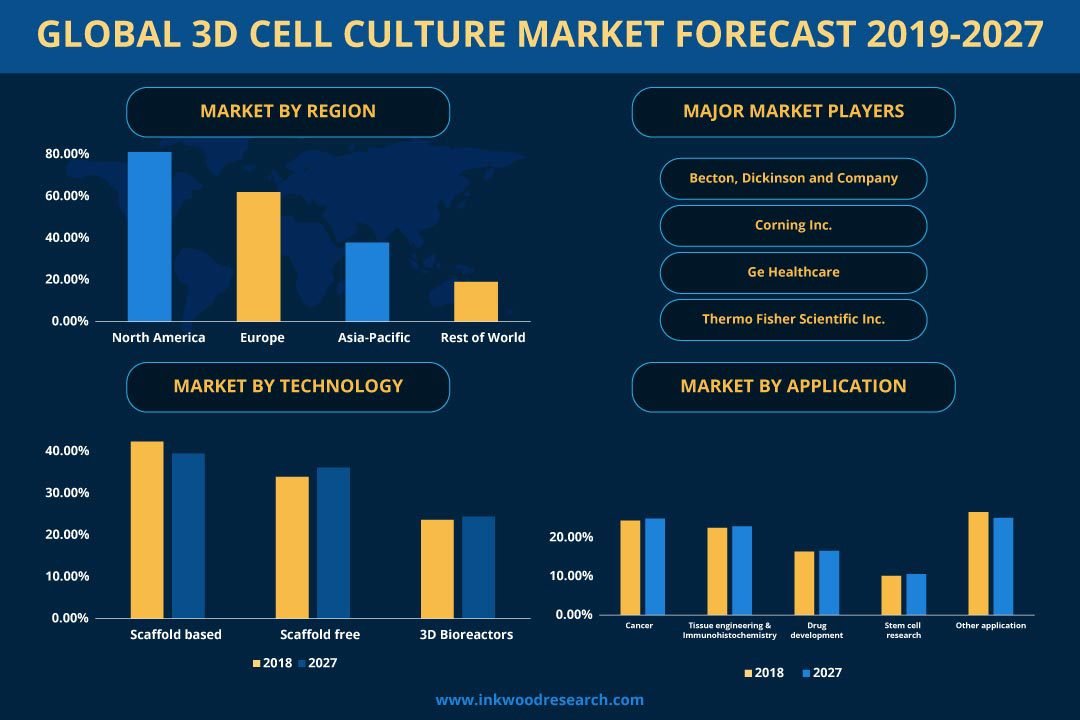
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
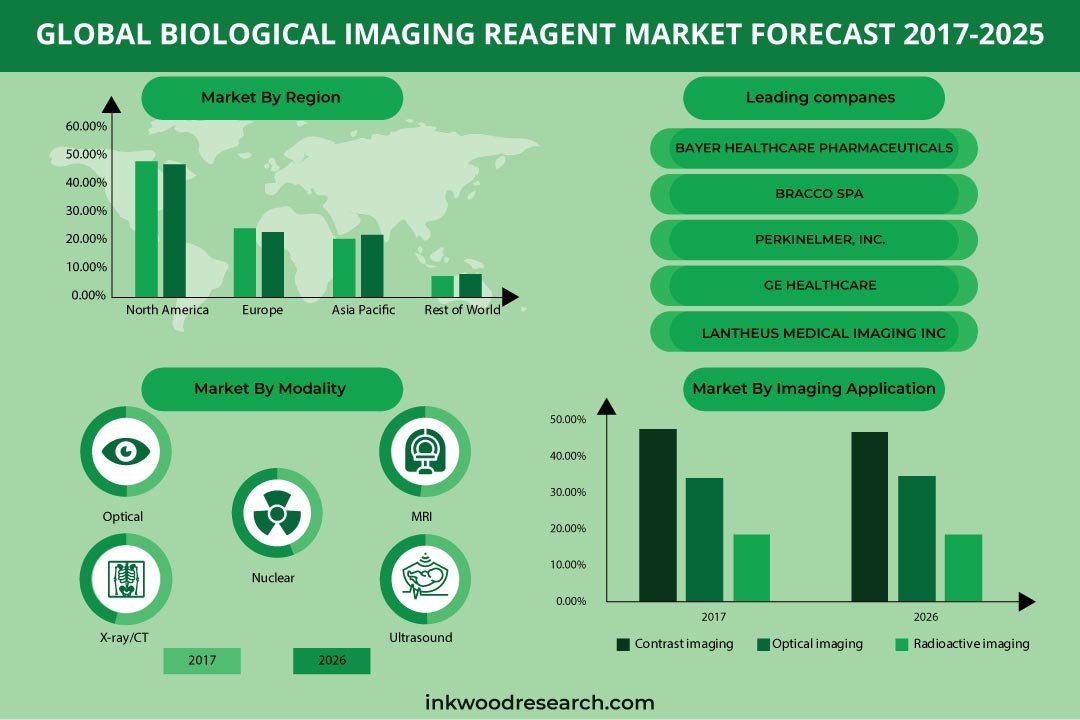
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034