
EUROPE CONTRAST ULTRASOUND MARKET FORECAST 2026-2034
SCOPE OF THE REPORT
Europe Contrast Ultrasound Market by Product (Equipment, Contrast Agents) Market by Type (Non-Targeted, Targeted) Market by Application (Diagnostic Applications, Therapeutic Applications) Market by End Use (Hospitals, Clinics, Ambulatory Diagnostic Centers), by Geography
REPORTS » HEALTHCARE » MEDICAL DEVICES » EUROPE CONTRAST ULTRASOUND MARKET FORECAST 2026-2034
EUROPE CONTRAST ULTRASOUND MARKET OVERVIEW
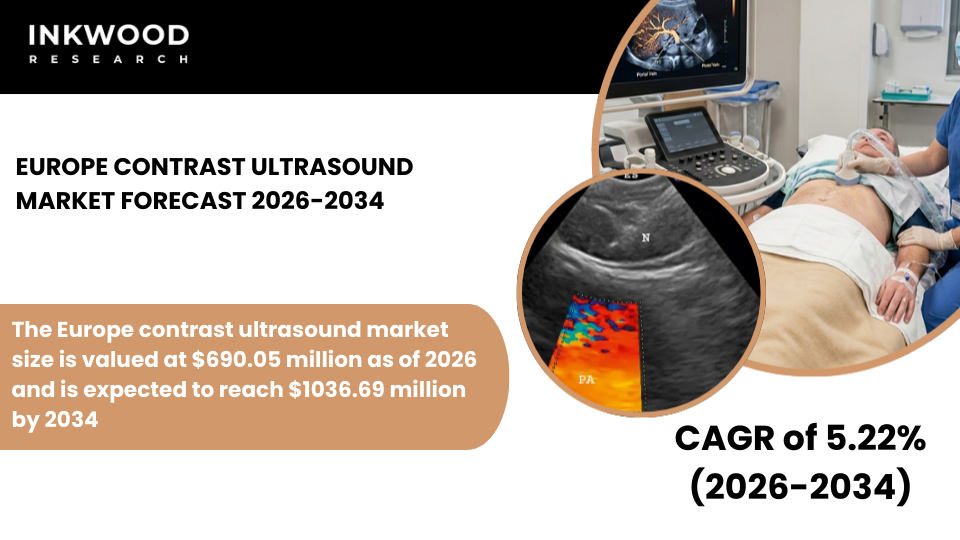
The Europe contrast ultrasound market size is valued at $690.05 million as of 2026 and is expected to reach $1036.69 million by 2034, progressing with a CAGR of 5.22% during the forecast years, 2026-2034.
Europe’s contrast ultrasound market is experiencing robust growth fueled by progressive regulatory frameworks, comprehensive healthcare coverage, and strong clinical adoption across multiple medical specialties. The region benefits from established clinical guidelines that actively promote contrast enhanced ultrasound as a first-line imaging modality for liver lesion characterization, cardiac assessments, and vascular evaluations.
European healthcare systems prioritize cost-effective diagnostic solutions that minimize radiation exposure, positioning enhanced ultrasound as an attractive alternative to computed tomography and magnetic resonance imaging for specific clinical indications. National health authorities across major European countries have implemented favorable reimbursement policies that cover contrast ultrasound procedures for oncology and cardiology applications, thereby reducing financial barriers for both healthcare providers and patients.
To Know More About This Report, Request a Free Sample Copy
Moreover, the region’s commitment to evidence-based medicine has generated extensive clinical literature demonstrating the diagnostic accuracy and safety profile of microbubble-based contrast agents, which strengthens physician confidence and encourages broader adoption. Academic medical centers and teaching hospitals throughout Europe serve as innovation hubs where new applications for therapeutic applications are being developed and validated through rigorous clinical trials.
Additionally, the European Medicines Agency’s streamlined approval pathways for contrast agents have accelerated market entry for novel formulations, including molecule-targeted microbubbles designed for molecular imaging and targeted drug delivery. The growing emphasis on patient-centered care and personalized medicine is driving demand for real-time imaging technologies that enable immediate clinical decision-making during diagnostic imaging procedures. These factors, in turn, are set to boost the contrast ultrasound market growth in Europe during the forecast period.
The Europe contrast ultrasound market growth assessment includes the analysis of the United Kingdom, Germany, France, Italy, Spain, Belgium, Poland, and Rest of Europe.
The United Kingdom represents a strategically important market within Europe, characterized by universal healthcare coverage through the National Health Service (NHS) and centralized procurement systems that influence adoption patterns across public hospitals and diagnostic centers. NHS England has recognized contrast enhanced ultrasound as a valuable diagnostic tool that can reduce reliance on more expensive imaging modalities, leading to increased integration of enhanced ultrasound protocols in clinical pathways for liver disease assessment and cardiac evaluations.
The country maintains strong research capabilities through institutions such as Imperial College London and King’s College London, where ongoing studies are expanding the evidence base for contrast ultrasound applications in pediatric imaging and interventional radiology. Furthermore, NHS procurement frameworks are encouraging suppliers to offer competitive pricing on both equipment and contrast agents, making advanced imaging technologies more accessible to smaller district hospitals and community healthcare facilities.
The UK’s regulatory environment supports innovation through the Medicines and Healthcare products Regulatory Agency, which works closely with manufacturers to ensure safe and effective contrast agent formulations reach the market efficiently. Clinical training programs organized by the British Medical Ultrasound Society are addressing historical gaps in sonographer expertise with contrast-enhanced techniques, thereby improving diagnostic quality and consistency across different healthcare settings.
The shift toward integrated care systems within the NHS is creating opportunities for portable ultrasound devices equipped with contrast-enhanced capabilities. This is particularly evident in primary care and urgent care environments where immediate diagnostic information can significantly impact patient management decisions.
Germany leads European adoption of contrast ultrasound technology due to its advanced healthcare infrastructure, strong industrial base in medical device manufacturing, and favorable reimbursement landscape. The country’s statutory health insurance system provides comprehensive coverage for contrast ultrasound procedures across multiple clinical indications, including liver imaging, cardiac assessments, and vascular diagnostics, which ensures broad patient access without significant out-of-pocket costs.
German hospitals and ambulatory surgical centers have made substantial investments in state-of-the-art ultrasound equipment, driven by the country’s emphasis on technological excellence and quality healthcare delivery. Major medical device companies headquartered in Germany, including Siemens Healthineers, maintain robust research and development programs focused on integrating artificial intelligence and advanced imaging software into ultrasound platforms, thereby enhancing the capabilities and clinical utility of contrast-enhanced studies.
Academic medical centers such as Charité in Berlin and University Hospital Munich serve as leading centers of excellence for contrast ultrasound research, conducting pivotal clinical trials that establish best practices and expand approved indications. The German Society for Ultrasound in Medicine provides comprehensive training curricula and certification programs that ensure clinicians maintain high levels of proficiency in contrast-enhanced imaging techniques.
Additionally, Germany’s regulatory environment, through the Federal Institute for Drugs and Medical Devices, supports the timely approval of innovative contrast agents while maintaining rigorous safety standards. The country’s emphasis on outpatient specialty care creates strong demand for efficient diagnostic imaging modalities that enable same-day diagnosis and treatment planning. This positions contrast ultrasound as an integral component of modern healthcare delivery across cardiology, oncology, and hepatology practices.
The Europe contrast ultrasound market is segmented into product, type, application, and end use. The application segment is further categorized into diagnostic applications and therapeutic applications.
The diagnostic applications segment dominates the Europe contrast ultrasound market and encompasses a broad range of clinical uses where enhanced ultrasound provides critical information for disease detection, characterization, and monitoring. This segment includes cardiac imaging for left ventricular opacification and endocardial border delineation in patients with technically difficult echocardiograms, liver imaging for characterization of focal liver lesions and detection of hepatocellular carcinoma in cirrhotic patients, and vascular imaging for assessment of carotid artery stenosis and peripheral arterial disease.
European clinical guidelines from organizations such as the European Federation of Societies for Ultrasound in Medicine and Biology strongly recommend contrast enhanced ultrasound as a first-line diagnostic tool for evaluating indeterminate liver lesions, particularly in patients where exposure to ionizing radiation or gadolinium-based contrast agents should be minimized. The diagnostic applications segment benefits from extensive clinical validation through multicenter European studies that have demonstrated high sensitivity and specificity for detecting malignant lesions, characterizing tumor vascularity patterns, and assessing treatment response following interventional procedures.
Moreover, the segment is experiencing growth in pediatric imaging, where radiation-free diagnostic modalities are strongly preferred for evaluating congenital heart defects, assessing renal perfusion abnormalities, and characterizing abdominal masses in children. Advanced imaging technologies, such as quantitative perfusion analysis software, are enabling objective measurement of blood flow parameters, which supports standardized reporting and facilitates comparison across serial examinations for monitoring disease progression or treatment efficacy.
The availability of contrast agents with excellent safety profiles and minimal contraindications has encouraged broader clinical adoption across diverse patient populations, including elderly patients with multiple comorbidities who may not be suitable candidates for alternative imaging modalities. Healthcare providers increasingly recognize that diagnostic applications of contrast ultrasound can reduce the need for more invasive or expensive diagnostic procedures, thereby improving care efficiency while maintaining high diagnostic accuracy and patient safety standards.
Some of the top players operating in the Europe contrast ultrasound market include Bracco Imaging SpA, Siemens Healthineers AG, GE Healthcare, and Koninklijke Philips NV, among others.
Bracco Imaging SpA, headquartered in Milan, Italy, is a global leader in diagnostic imaging with particular strength in the European contrast ultrasound market through its SonoVue brand microbubble contrast agent. The company operates manufacturing facilities in Plan-les-Ouates, Switzerland, where it recently invested over 80 million euros to triple production capacity for ultrasound contrast agents. Bracco maintains direct sales operations across major European markets and works closely with hospitals, imaging centers, and ambulatory diagnostic centers to support clinical adoption through comprehensive training programs and technical support services.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Product, Type, Application, End Use |
| Countries Analyzed | The United Kingdom, Germany, France, Italy, Spain, Poland, Belgium, and Rest of Europe |
| Companies Analyzed | GE HealthCare, Bracco Imaging SpA, Lantheus Holdings Inc, Siemens Healthineers AG, Koninklijke Philips NV, Bayer AG, Guerbet, Canon Medical Systems Corporation, Shenzhen Mindray Bio-Medical Electronics Co Ltd, Esaote SpA, FUJIFILM Holdings Corporation, Samsung Healthcare, Daiichi Sankyo Company Limited, Trivitron Healthcare Pvt Ltd, SuperSonic Imagine SA |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- THE CONTRAST ULTRASOUND MARKET IS EXPANDING STEADILY DUE TO RISING ADOPTION OF MICROBUBBLE-BASED IMAGING AGENTS IN CARDIOLOGY AND ONCOLOGY DIAGNOSTICS
- HOSPITALS REPRESENT THE LARGEST END-USER SEGMENT AS CONTRAST-ENHANCED ULTRASOUND IS INCREASINGLY USED FOR REAL-TIME PERFUSION ASSESSMENT
- EUROPE DRIVES MARKET REVENUE DUE TO ESTABLISHED REIMBURSEMENT FRAMEWORKS AND CLINICAL GUIDELINES
MARKET DYNAMICS
- KEY DRIVERS
- RISING PREVALENCE OF CARDIOVASCULAR DISEASES AND LIVER DISORDERS IS INCREASING DEMAND FOR ENHANCED DIAGNOSTIC ACCURACY
- GROWING PREFERENCE FOR MINIMALLY INVASIVE AND RADIATION-FREE IMAGING TECHNIQUES IS BOOSTING CONTRAST ULTRASOUND UTILIZATION
- TECHNOLOGICAL ADVANCEMENTS IN ULTRASOUND SYSTEMS ARE IMPROVING IMAGE RESOLUTION AND CLINICAL CONFIDENCE
- EXPANDING CLINICAL APPLICATIONS IN PEDIATRICS AND INTERVENTIONAL RADIOLOGY ARE BROADENING MARKET OPPORTUNITIES
- KEY RESTRAINTS
- LIMITED REIMBURSEMENT COVERAGE IN SEVERAL DEVELOPING MARKETS IS CONSTRAINING ADOPTION RATES
- REGULATORY COMPLEXITIES RELATED TO APPROVAL OF CONTRAST AGENTS CAN DELAY PRODUCT LAUNCHES
- LACK OF AWARENESS AND TRAINING AMONG SONOGRAPHERS MAY LIMIT OPTIMAL UTILIZATION
- COMPETITION FROM ALTERNATIVE IMAGING MODALITIES SUCH AS MRI AND CT SCANS MAY RESTRICT MARKET PENETRATION
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- INCREASING RESEARCH ON TARGETED MICROBUBBLE CONTRAST AGENTS IS DRIVING INNOVATION IN MOLECULAR IMAGING
- GROWING INTEGRATION OF ARTIFICIAL INTELLIGENCE IN ULTRASOUND WORKFLOWS IS ENHANCING DIAGNOSTIC PRECISION
- SHIFT TOWARD POINT-OF-CARE ULTRASOUND DEVICES IS EXPANDING ACCESS TO CONTRAST-ENHANCED STUDIES
- STRATEGIC COLLABORATIONS BETWEEN PHARMACEUTICAL AND MEDICAL DEVICE COMPANIES ARE ACCELERATING PRODUCT DEVELOPMENT
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR EUROPE
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SUPPLIERS
- CONTRAST AGENT MANUFACTURERS
- ULTRASOUND OEMS
- DISTRIBUTION PARTNERS
- HOSPITAL PROCUREMENT
- END-USER FACILITIES
- KEY BUYING CRITERIA
- IMAGE CLARITY
- SAFETY PROFILE
- REGULATORY APPROVAL
- COST EFFECTIVENESS
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
CONTRAST ULTRASOUND MARKET BY PRODUCT
- EQUIPMENT
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- CONTRAST AGENTS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- EQUIPMENT
CONTRAST ULTRASOUND MARKET BY TYPE
- NON-TARGETED
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- TARGETED
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- NON-TARGETED
CONTRAST ULTRASOUND MARKET BY APPLICATION
- DIAGNOSTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- THERAPEUTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DIAGNOSTIC APPLICATIONS
CONTRAST ULTRASOUND MARKET BY END USE
- HOSPITALS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- CLINICS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- AMBULATORY DIAGNOSTIC CENTERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- HOSPITALS
GEOGRAPHICAL ANALYSIS
- EUROPE
- MARKET SIZE & ESTIMATES
- EUROPE MARKET DRIVERS
- EUROPE MARKET CHALLENGES
- KEY PLAYERS IN EUROPE CONTRAST ULTRASOUND MARKET
- COUNTRY ANALYSIS
- GERMANY
- GERMANY MARKET SIZE & OPPORTUNITIES
- UNITED KINGDOM
- UNITED KINGDOM MARKET SIZE & OPPORTUNITIES
- FRANCE
- FRANCE MARKET SIZE & OPPORTUNITIES
- ITALY
- ITALY MARKET SIZE & OPPORTUNITIES
- SPAIN
- SPAIN MARKET SIZE & OPPORTUNITIES
- BELGIUM
- BELGIUM MARKET SIZE & OPPORTUNITIES
- POLAND
- POLAND MARKET SIZE & OPPORTUNITIES
- REST OF EUROPE
- REST OF EUROPE MARKET SIZE & OPPORTUNITIES
- GERMANY
- EUROPE
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- GE HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- BRACCO IMAGING SPA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- LANTHEUS HOLDINGS INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SIEMENS HEALTHINEERS AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- KONINKLIJKE PHILIPS NV
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- BAYER AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GUERBET
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- CANON MEDICAL SYSTEMS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ESAOTE SPA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- FUJIFILM HOLDINGS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SAMSUNG HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- DAIICHI SANKYO COMPANY LIMITED
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- TRIVITRON HEALTHCARE PVT LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SUPERSONIC IMAGINE SA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GE HEALTHCARE
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – CONTRAST ULTRASOUND
TABLE 2: CONTRAST ULTRASOUND MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY PRODUCT, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY PRODUCT, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: MARKET BY TYPE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: MARKET BY TYPE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: MARKET BY APPLICATION, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: MARKET BY APPLICATION, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: MARKET BY END USE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: MARKET BY END USE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: EUROPE MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 12: EUROPE MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 13: KEY PLAYERS OPERATING IN THE EUROPEAN MARKET
TABLE 14: LIST OF MERGERS & ACQUISITIONS
TABLE 15: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 16: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 17: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR EUROPE
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY PRODUCT, IN 2025
FIGURE 11: EQUIPMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: CONTRAST AGENTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY TYPE, IN 2025
FIGURE 14: NON-TARGETED MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: TARGETED MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: SEGMENT GROWTH POTENTIAL, BY APPLICATION, IN 2025
FIGURE 17: DIAGNOSTIC APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: THERAPEUTIC APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: SEGMENT GROWTH POTENTIAL, BY END USE, IN 2025
FIGURE 20: HOSPITALS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: CLINICS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: AMBULATORY DIAGNOSTIC CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: EUROPE CONTRAST ULTRASOUND MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 24: GERMANY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: UNITED KINGDOM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: FRANCE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: ITALY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: SPAIN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 29: BELGIUM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: POLAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: REST OF EUROPE MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-
EUROPE SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
NORTH AMERICA SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
SPAIN ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
MEXICO ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
ITALY ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
AUSTRALIA ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
BRAZIL ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034