China Food Delivery Platform Fee Structures Market by Delivery Mode (Platform-To-Consumer Delivery, Restaurant-To-Consumer Delivery), Market by Payment Method (Online Payment, Cash On Delivery (COD)), Market by Revenue Model (Commission-Based Revenue, Delivery Fee-Based Revenue, Advertising & Promotion Revenue, Subscription-Based Revenue), Market by Product Type (Meal Delivery, Grocery Delivery, Meal Kit Delivery, Alcohol Delivery, Other Product Types), by Geography
CHINA FOOD DELIVERY PLATFORM FEE STRUCTURES MARKET OVERVIEW
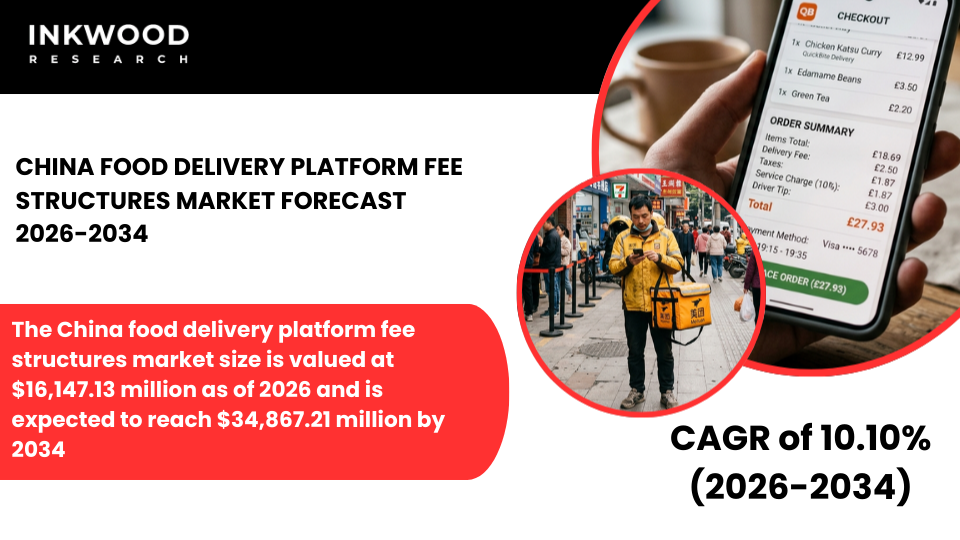
The China food delivery platform fee structures market size is valued at $16,147.13 million as of 2026 and is expected to reach $34,867.21 million by 2034, progressing with a CAGR of 10.10% during the forecast years, 2026-2034.
MARKET INSIGHTS
China is the world’s largest and most technologically advanced market for food delivery platform fee structures, underpinned by an extraordinary convergence of mass smartphone adoption, near-universal mobile payment penetration, and hyper-dense urban populations that generate some of the highest food delivery order volumes globally. The country’s online food delivery platform ecosystem is dominated by two technology giants, Meituan and Ele.me, both of which operate highly sophisticated, data-driven food delivery platform fee structures that span restaurant delivery commissions, delivery fee income, in-app advertising revenue, and membership-based subscription models.
According to the National Bureau of Statistics of China (NBS), online retail sales of physical goods in China have grown consistently as a share of total consumer spending, reflecting the depth of digital commerce integration in daily Chinese life. This structural shift in consumer behaviour has, in turn, created an immense and durable foundation for food delivery platform pricing growth across the country.
China’s regulatory environment has become an increasingly important force shaping food delivery platform fee structure design. The State Administration for Market Regulation (SAMR) has issued guidelines specifically targeting online food delivery platforms, requiring greater transparency in how food delivery service charges and restaurant delivery commissions are disclosed to merchant partners.
Recently, SAMR introduced regulations compelling platforms to offer merchants fairer and more clearly itemised food delivery platform fee structures, responding to widespread restaurant complaints about opaque commission practices and disproportionate cost burdens. Additionally, the National Development and Reform Commission (NDRC) has pushed for improved gig worker protections, which has added upward cost pressure on platforms’ logistics operations.
For platform operators, navigating these regulatory requirements demands robust compliance infrastructure, while simultaneously creating an opportunity to build merchant trust through transparent and flexible food delivery platform pricing models. Beyond regulation, China’s market presents exceptional growth opportunities, particularly in the advertising and promotion revenue segment, where platforms are deploying increasingly sophisticated in-app marketing tools that allow restaurants to boost visibility and drive order volume through sponsored placements and targeted promotions.
The integration of food delivery into broader super app ecosystems, most notably through Meituan’s and Alibaba’s platforms, further amplifies the monetization potential of online food ordering platform fees by embedding delivery services within loyalty programmes, digital payments, and retail commerce. For investors and vendors, China’s combination of unmatched scale, rapidly evolving food delivery commission rate structures, and government-driven pressure toward fee transparency represents a high-stakes but high-reward competitive landscape. These factors, together, are set to boost the food delivery platform fee structures market growth in China during the forecast period.
To Know More About This Report, Request a Free Sample Copy
SEGMENTATION ANALYSIS
The China food delivery platform fee structures market is segmented by delivery mode, payment method, revenue model, and product type. The revenue model segment is further categorized into commission-based revenue, delivery fee-based revenue, advertising and promotion revenue, and subscription-based revenue.
Advertising and promotion revenue is one of the fastest-growing sub-segments within the revenue model segment of the China food delivery platform fee structures market, reflecting the maturation of Chinese platforms beyond pure commission-based monetization. As competition among restaurants for consumer attention on crowded digital marketplaces has intensified, platforms such as Meituan and Ele.me have built out comprehensive in-app advertising ecosystems that allow merchants to purchase sponsored search placements, banner advertisements, and targeted promotional slots within the platform interface. These advertising products generate food delivery platform revenue that is entirely independent of per-order restaurant delivery commissions, providing platforms with a high-margin, scalable income stream that grows in value as the platform’s consumer base expands.
Furthermore, China’s advanced digital marketing infrastructure, including integration with Alipay, WeChat Pay, and platform-native loyalty programmes, enables highly precise audience targeting that makes advertising and promotion products exceptionally attractive to restaurant partners seeking measurable returns on their marketing spend. As a result, the food delivery platform advertising revenue model in China is evolving into a core pillar of overall platform monetization strategy, sitting alongside and increasingly rivalling commission-based income in strategic importance.
COMPETITIVE INSIGHTS
Some of the top players operating in the China food delivery platform fee structures market include Meituan Dianping, Ele.me, JD Daojia (JD.com), Koubei, etc.
Meituan Dianping is China’s dominant online food ordering platform and one of the largest food delivery marketplace operators in the world, headquartered in Beijing. Meituan connects tens of millions of consumers with restaurant partners and retail merchants across hundreds of Chinese cities, operating a platform-to-consumer delivery model supported by one of the country’s most extensive and technologically advanced logistics networks.
The company’s food delivery platform fee structure encompasses restaurant delivery commissions, consumer-facing delivery fees, in-app advertising products, and its membership subscription service Meituan Shenhui, together forming a diversified and high-scale food delivery platform revenue model that extends well beyond its core commission income.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Delivery Mode, Payment Method, Revenue Model, Product Type |
| Country Analyzed | China |
| Companies Analyzed | Meituan Dianping, Ele.me, JD Daojia (JD.com), Taobao Flash Buy, Koubei, Dianwoda, SF Express Food Delivery |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE, SHARE & ESTIMATES
- MARKET OVERVIEW
- SCOPE OF STUDY
- MAJOR MARKET FINDINGS
- THE CHINA FOOD DELIVERY PLATFORM FEE STRUCTURES MARKET IS ONE OF THE LARGEST GLOBALLY WITH HIGH ORDER VOLUMES AND ADVANCED DIGITAL PAYMENT ECOSYSTEMS
- PLATFORMS UTILIZE MULTIPLE REVENUE STREAMS INCLUDING COMMISSIONS, DELIVERY FEES, IN-APP ADVERTISING, AND PROMOTIONAL SERVICES
- SUPER APP ECOSYSTEMS ENABLE FOOD DELIVERY PLATFORMS TO INTEGRATE PAYMENT, LOYALTY PROGRAMS, AND RETAIL SERVICES
- THE MARKET IS DOMINATED BY LARGE TECHNOLOGY COMPANIES THAT CONTROL EXTENSIVE LOGISTICS NETWORKS
MARKET DYNAMICS
- KEY DRIVERS
- HIGH SMARTPHONE PENETRATION AND MOBILE PAYMENT USAGE ARE DRIVING MASS ADOPTION OF DIGITAL FOOD DELIVERY SERVICES
- STRONG URBANIZATION AND DENSE CITY POPULATIONS SUPPORT A HIGH FREQUENCY OF DELIVERY ORDERS
- THE INTEGRATION OF FOOD DELIVERY INTO SUPER APPS IS INCREASING USER ENGAGEMENT AND PLATFORM REVENUE
- ADVANCED LOGISTICS NETWORKS AND AI-DRIVEN ROUTING SYSTEMS ARE IMPROVING DELIVERY EFFICIENCY
- KEY RESTRAINTS
- REGULATORY INTERVENTIONS REGARDING PLATFORM ECONOMICS AND GIG WORKER PROTECTIONS ARE IMPACTING PLATFORM MARGINS
- INTENSE COMPETITION BETWEEN MAJOR PLATFORMS IS LEADING TO FREQUENT PRICE DISCOUNTS AND INCENTIVE PROGRAMS
- HIGH INVESTMENT REQUIREMENTS FOR LOGISTICS INFRASTRUCTURE ARE INCREASING OPERATIONAL COSTS
- RESTAURANT DEPENDENCE ON LARGE PLATFORMS IS LEADING TO NEGOTIATION PRESSURES ON COMMISSION STRUCTURES
- KEY DRIVERS
STRATEGIC MARKET ANALYTICS
- GROWTH METRICS
- TAM, SAM & SOM OPPORTUNITY ANALYSIS
- EMERGING MARKET TRENDS & PARADIGM SHIFTS
- PLATFORMS ARE INCREASINGLY USING DATA ANALYTICS TO OPTIMIZE COMMISSION STRUCTURES AND DELIVERY FEES
- THE EXPANSION OF IN-APP ADVERTISING AND MERCHANT PROMOTIONAL SERVICES IS DRIVING ADDITIONAL REVENUE
- QUICK COMMERCE AND NON-FOOD DELIVERY SERVICES ARE BEING INTEGRATED INTO FOOD DELIVERY PLATFORMS
- AUTOMATED DELIVERY TECHNOLOGIES SUCH AS ROBOTS AND DRONES ARE BEING PILOTED IN SELECT CITIES
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- PESTLE ANALYSIS
- POLITICAL
- ECONOMIC
- SOCIAL LANDSCAPE
- TECHNOLOGY
- LEGAL
- ENVIRONMENTAL
- GROWTH OPPORTUNITY MAPPING & HEATMAP
- GROWTH PROSPECT MAPPING FOR CHINA
- MARKET MATURITY & LIFECYCLE ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- GROWTH METRICS
FOOD DELIVERY PLATFORM FEE STRUCTURES VALUE CHAIN & DECISION FRAMEWORK
- VALUE CHAIN ANALYSIS
- MERCHANT ONBOARDING & FEE CONTRACTING
- PLATFORM TECHNOLOGY & FEE ENGINE
- FEE STRUCTURE DESIGN & MONETIZATION
- LOGISTICS & DELIVERY COST MANAGEMENT
- MARKETING, VISIBILITY & DEMAND GENERATION
- SETTLEMENT, ANALYTICS & REGULATORY COMPLIANCE
- KEY BUYING CRITERIA
- COMMISSION LEVELS & FEE TRANSPARENCY
- IMPACT ON MERCHANT PROFITABILITY
- FLEXIBILITY OF FEE MODELS
- DEMAND REACH & ORDER POTENTIAL
- PROMOTION EFFECTIVENESS & VISIBILITY ROI
- SETTLEMENT RELIABILITY & PLATFORM CREDIBILITY
- PRICING MODELS, FEE STRUCTURES & TAKE RATE OPTIMIZATION STRATEGIES
- REGULATORY & POLICY LANDSCAPE ANALYSIS
- VALUE CHAIN ANALYSIS
FOOD DELIVERY PLATFORM FEE STRUCTURES MARKET BY DELIVERY MODE
- PLATFORM-TO-CONSUMER DELIVERY
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- RESTAURANT-TO-CONSUMER DELIVERY
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PLATFORM-TO-CONSUMER DELIVERY
FOOD DELIVERY PLATFORM FEE STRUCTURES MARKET BY PAYMENT METHOD
- ONLINE PAYMENT
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- CASH ON DELIVERY (COD)
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ONLINE PAYMENT
FOOD DELIVERY PLATFORM FEE STRUCTURES MARKET BY REVENUE MODEL
- COMMISSION-BASED REVENUE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- DELIVERY FEE-BASED REVENUE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ADVERTISING & PROMOTION REVENUE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SUBSCRIPTION-BASED REVENUE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- COMMISSION-BASED REVENUE
FOOD DELIVERY PLATFORM FEE STRUCTURES MARKET BY PRODUCT TYPE
- MEAL DELIVERY
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- GROCERY DELIVERY
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- MEAL KIT DELIVERY
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ALCOHOL DELIVERY
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER PRODUCT TYPES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- MEAL DELIVERY
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPETITOR POSITIONING & DIFFERENTIATION MAP
- COMPANY PROFILES
- MEITUAN DIANPING
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- ME
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- JD DAOJIA (JD.COM)
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- TAOBAO FLASH BUY
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- KOUBEI
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- DIANWODA
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- SF EXPRESS FOOD DELIVERY
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- MEITUAN DIANPING
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – FOOD DELIVERY PLATFORM FEE STRUCTURES
TABLE 2: PRICING MODELS, FEE STRUCTURES & TAKE RATE OPTIMIZATION STRATEGIES
TABLE 3: REGULATORY & POLICY LANDSCAPE ANALYSIS
TABLE 4: MARKET BY DELIVERY MODE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 5: MARKET BY DELIVERY MODE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 6: MARKET BY PAYMENT METHOD, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 7: MARKET BY PAYMENT METHOD, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 8: MARKET BY REVENUE MODEL, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 9: MARKET BY REVENUE MODEL, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 10: MARKET BY PRODUCT TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 11: MARKET BY PRODUCT TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 12: KEY PLAYERS OPERATING IN THE CHINESE MARKET
TABLE 13: LIST OF MERGERS & ACQUISITIONS
TABLE 14: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 15: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 16: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR CHINA
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY DELIVERY MODE, IN 2025
FIGURE 11: PLATFORM-TO-CONSUMER DELIVERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: RESTAURANT-TO-CONSUMER DELIVERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY PAYMENT METHOD, IN 2025
FIGURE 14: ONLINE PAYMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: CASH ON DELIVERY (COD) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: SEGMENT GROWTH POTENTIAL, BY REVENUE MODEL, IN 2025
FIGURE 17: COMMISSION-BASED REVENUE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: DELIVERY FEE-BASED REVENUE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: ADVERTISING & PROMOTION REVENUE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: SUBSCRIPTION-BASED REVENUE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: SEGMENT GROWTH POTENTIAL, BY PRODUCT TYPE, IN 2025
FIGURE 22: MEAL DELIVERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: GROCERY DELIVERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: MEAL KIT DELIVERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: ALCOHOL DELIVERY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: OTHER PRODUCT TYPES MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
LATIN AMERICA FACIAL RECOGNITION MARKET FORECAST 2019-2028
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

JAPAN AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

INDIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034