China Cardiovascular Ultrasound Market by Device Display (Color Display Systems, Black & White (B/W) Display Systems) Market by Technology (2D Ultrasound, 3D & 4D Ultrasound, Doppler Imaging) Market by Application (Diagnostic Applications, Therapeutic Applications) Market by Type (Transthoracic Echocardiogram, Transesophageal Echocardiogram, Stress Echocardiogram, Fetal Echocardiography, Other Types) Market by End-User (Hospitals, Diagnostic Centers, Ambulatory Care Centers, Other End-Users), by Geography
CHINA CARDIOVASCULAR ULTRASOUND MARKET OVERVIEW
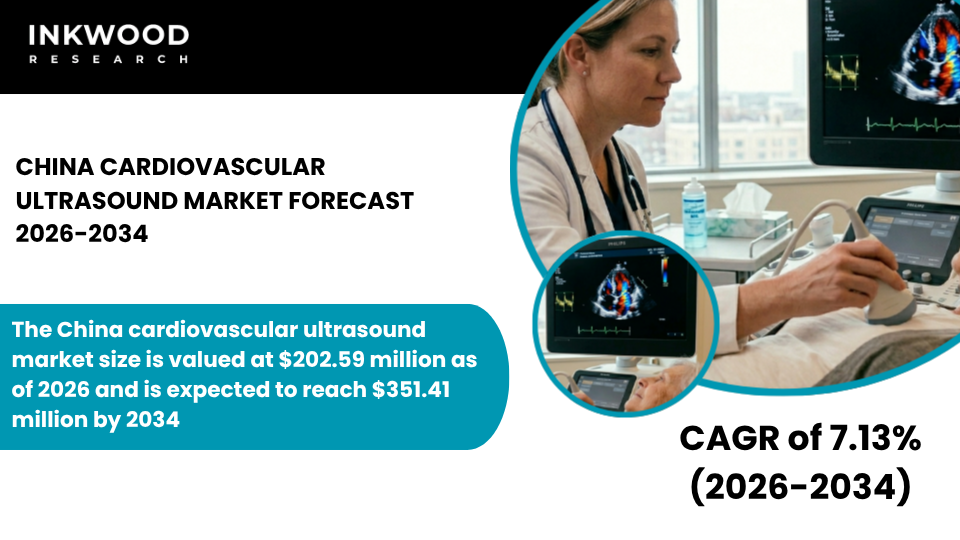
The China cardiovascular ultrasound market size is valued at $202.59 million as of 2026 and is expected to reach $351.41 million by 2034, progressing with a CAGR of 7.13% during the forecast years, 2026–2034.
China stands as a consequential national market for cardiovascular ultrasound in Asia-Pacific, driven by a cardiovascular disease burden of extraordinary scale, an accelerating national health reform agenda, and growing clinical appetite for advanced cardiac diagnostic technologies across all tiers of its healthcare system. According to the 2024 Annual Report on Cardiovascular Health and Diseases in China, published by the National Center for Cardiovascular Diseases, the crude incidence of cardiovascular and cerebrovascular diseases among Chinese residents aged 18 years and above reached 620.33 per 100,000 population.
Moreover, stroke alone accounted for 491.0 per 100,000, figures that reflect decades of rapid urbanization, dietary change, and population aging converging into an acute public health challenge. The China Health Statistics Yearbook (2022), issued by the National Health Commission, further confirms that cardiovascular disease remained the leading cause of death in 2021 in both urban and rural populations, accounting for 47.35% and 48.98% of all deaths, respectively. This means nearly one in every two deaths in China can be attributed to a cardiovascular cause, making early detection through cardiac ultrasound systems not just clinically valuable, but a public health imperative.
To Know More About This Report, Request a Free Sample Copy
China’s government has responded with decisive policy action. The Healthy China 2030 initiative explicitly targets cardiovascular disease prevention as a national priority, anchoring the expansion of cardiac diagnostic infrastructure, including cardiovascular ultrasound, within the country’s primary healthcare strengthening roadmap. Government procurement of medical imaging equipment has scaled meaningfully in recent years, with public hospitals remaining the dominant buyers through centralized tendering frameworks that influence pricing and vendor selection across the market.
At the same time, the push to extend diagnostic services into lower-tier cities and rural regions is opening new access points for portable and point-of-care cardiac ultrasound systems, broadening the market well beyond the Tier 1 city hospital clusters that have historically driven volume. These intersecting forces, a massive and growing patient pool, active government investment, and expanding geographic reach, give the China cardiovascular ultrasound market a growth profile that is both deep and durable over the forecast period.
The China cardiovascular ultrasound market is segmented by device display, technology, application, type, and end-user. The application segment is further categorized into diagnostic applications and therapeutic applications.
Diagnostic applications represent the dominant sub-segment within the application segment of the China cardiovascular ultrasound market. Their commanding position reflects the fundamental clinical role that cardiac imaging plays across the continuum of cardiovascular care in China. In a market where cardiovascular disease is the leading cause of death, and where the incidence of acute myocardial infarction, coronary heart disease, and stroke continues to rise, as confirmed by the National Health Commission’s health statistics, the demand for reliable, non-invasive cardiac diagnostics is structurally embedded into everyday clinical practice across China’s vast hospital network.
Diagnostic applications encompass a broad range of cardiac assessments, including structural evaluation through the transthoracic echocardiogram, detailed anatomical imaging via transesophageal echocardiogram, and functional cardiac stress testing. Together, these procedures form the diagnostic backbone of cardiology departments in China’s public hospitals, which account for the majority of cardiac ultrasound procurement nationwide. Adding to this, the Healthy China 2030 initiative’s focus on preventive care and early detection is further accelerating diagnostic application volumes, as primary care facilities increasingly integrate cardiovascular screening protocols into routine health management.
The growing adoption of AI-assisted diagnostic tools within cardiovascular ultrasound platforms is also enhancing throughput and consistency in clinical workflows, particularly in hospitals that face high patient volumes and constrained specialist capacity. As a result, for vendors operating in the cardiovascular imaging market, the diagnostic applications sub-segment offers both scale and longevity. It is the segment where replacement cycles are most predictable, clinical workflows are most established, and government reimbursement frameworks are best aligned with equipment investment.
Some of the top players operating in the China cardiovascular ultrasound market include CHISON Medical Technologies Co Ltd, Mindray Medical International Limited, GE HealthCare, Koninklijke Philips NV, Siemens Healthineers AG, etc.
CHISON Medical Technologies Co Ltd is a Wuxi, Jiangsu-headquartered ultrasound manufacturer and one of China’s most established domestic players in the cardiovascular ultrasound market. CHISON has built a portfolio that spans cart-based systems, portable units, and handheld devices, with dedicated cardiovascular imaging solutions designed for cardiologists across a range of clinical settings, from large public hospitals to community health centers.
The company’s cardiovascular ultrasound lineup, including the XBit 90 with advanced TEE imaging capabilities and the SonoMax system powered by its MAX++ platform, addresses the full spectrum of cardiac diagnostic procedures, from routine transthoracic echocardiogram workflows to complex structural heart assessments.
Moreover, CHISON is certified by regulatory authorities across key markets, including CE (EU), FDA (US), KFDA (South Korea), and CSA (Canada), supporting its presence in over 100 countries, while its domestic manufacturing base and competitive pricing give it a natural advantage within China’s centralized hospital procurement environment, where cost-efficiency and local support infrastructure are decisive buying criteria.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Device Display, Technology, Type, End-User |
| Country Analyzed | China |
| Companies Analyzed | Canon Medical Systems Corporation, CHISON Medical Technologies Co Ltd, Esaote SpA, FUJIFILM Holdings Corporation, GE Healthcare, Hitachi Medical Corporation, Koninklijke Philips NV, Mindray Medical International Limited, Samsung Medison Co Ltd, Siemens Healthineers AG, Zonare Medical Systems (part of Mindray) |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- CHINA REPRESENTS A KEY CARDIOVASCULAR ULTRASOUND MARKET IN ASIA-PACIFIC, DRIVEN BY ITS LARGE PATIENT POOL AND RAPIDLY AGING POPULATION
- TIER 1 AND TIER 2 CITIES ACCOUNT FOR THE MAJORITY OF ADVANCED 3D AND 4D CARDIAC ULTRASOUND SYSTEM INSTALLATIONS
- PUBLIC HOSPITALS DOMINATE PROCUREMENT, WITH CENTRALIZED TENDERING SIGNIFICANTLY INFLUENCING PRICING STRUCTURES
- DOMESTIC MANUFACTURERS ARE GAINING MARKET SHARE THROUGH COST-COMPETITIVE AND TECHNOLOGICALLY IMPROVED SYSTEMS
MARKET DYNAMICS
- KEY DRIVERS
- RISING PREVALENCE OF CARDIOVASCULAR DISEASES ASSOCIATED WITH URBANIZATION AND LIFESTYLE CHANGES IS DRIVING DIAGNOSTIC DEMAND
- GOVERNMENT INVESTMENTS IN HEALTHCARE INFRASTRUCTURE UNDER NATIONAL HEALTH REFORM PROGRAMS ARE EXPANDING EQUIPMENT PROCUREMENT
- INCREASING ADOPTION OF PORTABLE AND POINT OF CARE ULTRASOUND DEVICES IS IMPROVING ACCESS IN RURAL REGIONS
- TECHNOLOGICAL ADVANCEMENTS, INCLUDING AI-ENABLED IMAGE ANALYSIS, ARE ENHANCING CLINICAL EFFICIENCY AND DIAGNOSTIC ACCURACY
- KEY RESTRAINTS
- PRICE SENSITIVITY IN LOWER TIER CITIES LIMITS ADOPTION OF PREMIUM CARDIOVASCULAR ULTRASOUND SYSTEMS
- REGULATORY APPROVAL PROCESSES CAN DELAY MARKET ENTRY FOR FOREIGN MANUFACTURERS
- SHORTAGE OF HIGHLY TRAINED CARDIAC SONOGRAPHERS IN RURAL AREAS RESTRICTS FULL UTILIZATION OF ADVANCED SYSTEMS
- INTENSE PRICE COMPETITION FROM DOMESTIC BRANDS PUTS PRESSURE ON PROFIT MARGINS
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- INCREASING INTEGRATION OF ARTIFICIAL INTELLIGENCE FOR AUTOMATED MEASUREMENTS AND WORKFLOW OPTIMIZATION
- RISING DEMAND FOR HANDHELD ULTRASOUND DEVICES IN EMERGENCY AND PRIMARY CARE SETTINGS
- EXPANSION OF TELECARDIOLOGY SERVICES SUPPORTING REMOTE DIAGNOSIS IN UNDERDEVELOPED REGIONS
- STRONG FOCUS ON LOCALIZED MANUFACTURING TO REDUCE DEPENDENCE ON IMPORTED MEDICAL DEVICES
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR CHINA
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SUPPLIERS
- COMPONENT MANUFACTURERS
- SYSTEM INTEGRATORS
- DEVICE MANUFACTURERS
- DISTRIBUTION CHANNELS
- HEALTHCARE PROVIDERS
- AFTER SALES SERVICES
- KEY BUYING CRITERIA
- IMAGE RESOLUTION
- PORTABILITY FEATURES
- TOTAL CO ST OWNERSHIP
- SERVICE SUPPORT AVAILABILITY
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
CARDIOVASCULAR ULTRASOUND MARKET BY DEVICE DISPLAY
- COLOR DISPLAY SYSTEMS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- BLACK & WHITE (B/W) DISPLAY SYSTEMS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- COLOR DISPLAY SYSTEMS
CARDIOVASCULAR ULTRASOUND MARKET BY TECHNOLOGY
- 2D ULTRASOUND
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- 3D & 4D ULTRASOUND
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DOPPLER IMAGING
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- 2D ULTRASOUND
CARDIOVASCULAR ULTRASOUND MARKET BY APPLICATION
- DIAGNOSTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- THERAPEUTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DIAGNOSTIC APPLICATIONS
CARDIOVASCULAR ULTRASOUND MARKET BY TYPE
- TRANSTHORACIC ECHOCARDIOGRAM
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- TRANSESOPHAGEAL ECHOCARDIOGRAM
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- STRESS ECHOCARDIOGRAM
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- FETAL ECHOCARDIOGRAPHY
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- OTHER TYPES
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- TRANSTHORACIC ECHOCARDIOGRAM
CARDIOVASCULAR ULTRASOUND MARKET BY END-USER
- HOSPITALS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DIAGNOSTIC CENTERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- AMBULATORY CARE CENTERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- OTHER END-USERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- HOSPITALS
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- CANON MEDICAL SYSTEMS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- CHISON MEDICAL TECHNOLOGIES CO LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ESAOTE SPA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- FUJIFILM HOLDINGS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GE HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- HITACHI MEDICAL CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- KONINKLIJKE PHILIPS NV
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- MINDRAY MEDICAL INTERNATIONAL LIMITED
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SAMSUNG MEDISON CO LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SIEMENS HEALTHINEERS AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ZONARE MEDICAL SYSTEMS (PART OF MINDRAY)
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- CANON MEDICAL SYSTEMS CORPORATION
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – CARDIOVASCULAR ULTRASOUND
TABLE 2: CARDIOVASCULAR ULTRASOUND MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY DEVICE DISPLAY, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY DEVICE DISPLAY, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: MARKET BY TECHNOLOGY, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: MARKET BY TECHNOLOGY, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: MARKET BY TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: MARKET BY TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: MARKET BY END-USER, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: MARKET BY END-USER, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: KEY PLAYERS OPERATING IN THE CHINESE MARKET
TABLE 12: LIST OF MERGERS & ACQUISITIONS
TABLE 13: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 14: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 15: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR CHINA
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY DEVICE DISPLAY, IN 2025
FIGURE 11: COLOR DISPLAY SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: BLACK & WHITE (B/W) DISPLAY SYSTEMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY TECHNOLOGY, IN 2025
FIGURE 14: 2D ULTRASOUND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: 3D & 4D ULTRASOUND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: DOPPLER IMAGING MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: SEGMENT GROWTH POTENTIAL, BY TYPE, IN 2025
FIGURE 18: TRANSTHORACIC ECHOCARDIOGRAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: TRANSESOPHAGEAL ECHOCARDIOGRAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: STRESS ECHOCARDIOGRAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: FETAL ECHOCARDIOGRAPHY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: OTHER TYPES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: SEGMENT GROWTH POTENTIAL, BY END-USER, IN 2025
FIGURE 24: HOSPITALS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: DIAGNOSTIC CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: AMBULATORY CARE CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: OTHER END-USERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034