
ASIA-PACIFIC CONTRAST ULTRASOUND MARKET FORECAST 2026-2034
SCOPE OF THE REPORT
Asia-Pacific Contrast Ultrasound Market by Product (Equipment, Contrast Agents) Market by Type (Non-Targeted, Targeted) Market by Application (Diagnostic Applications, Therapeutic Applications) Market by End Use (Hospitals, Clinics, Ambulatory Diagnostic Centers), by Geography
REPORTS » HEALTHCARE » MEDICAL DEVICES » ASIA-PACIFIC CONTRAST ULTRASOUND MARKET FORECAST 2026-2034
ASIA-PACIFIC CONTRAST ULTRASOUND MARKET OVERVIEW
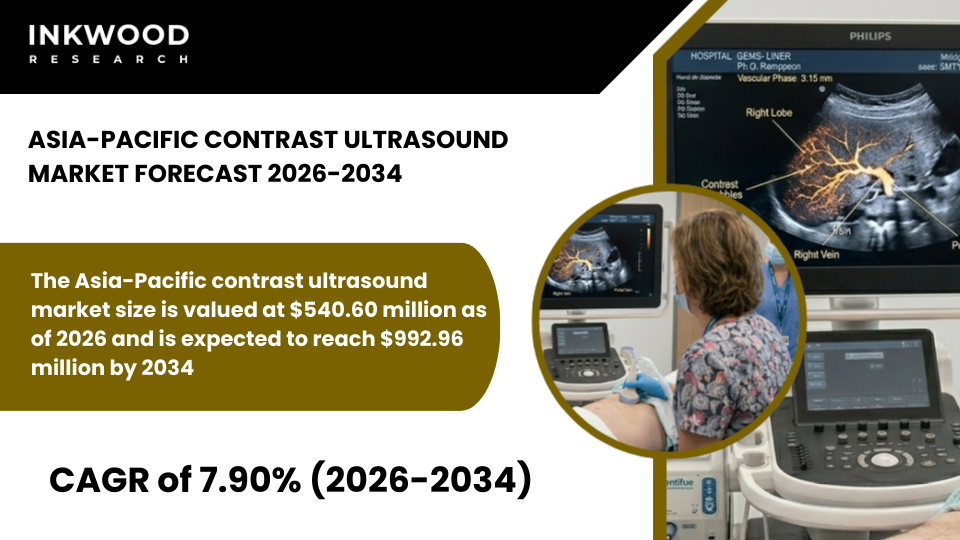
The Asia-Pacific contrast ultrasound market size is valued at $540.60 million as of 2026 and is expected to reach $992.96 million by 2034, progressing with a CAGR of 7.90% during the forecast years, 2026-2034.
Asia-Pacific’s contrast ultrasound market is experiencing the fastest growth globally, driven by rapid healthcare infrastructure expansion, rising incidence of chronic diseases, and increasing government investments in advanced diagnostic technologies. The region benefits from large patient populations requiring accessible and affordable imaging solutions, which positions enhanced ultrasound as an attractive alternative to more expensive cross-sectional imaging modalities.
National healthcare reforms across major economies are prioritizing the deployment of radiation-free diagnostic imaging capabilities to reduce long-term health risks associated with repeated CT scans and fluoroscopy procedures. Moreover, growing awareness among healthcare providers about the clinical benefits of contrast enhanced ultrasound for oncology and cardiology applications is accelerating adoption in tertiary hospitals and specialty imaging centers.
The region’s demographic trends, particularly rapid population aging in countries like Japan and China, are creating sustained demand for cardiovascular imaging and liver disease diagnostics, where contrast ultrasound provides critical clinical information. Government initiatives aimed at improving rural healthcare access are driving procurement of portable ultrasound devices equipped with contrast-enhanced capabilities, thereby extending advanced diagnostic services beyond major urban centers.
To Know More About This Report, Request a Free Sample Copy
Additionally, domestic medical device manufacturers are introducing cost-competitive ultrasound systems tailored to local market needs, which is improving affordability and accessibility across diverse economic segments. Regulatory agencies throughout Asia-Pacific are streamlining approval pathways for contrast agents and imaging equipment, reducing time-to-market for innovative products and encouraging multinational companies to expand their regional presence.
The growing prevalence of liver diseases, including hepatitis-related cirrhosis and hepatocellular carcinoma, is particularly significant in driving demand for diagnostic applications of contrast ultrasound in screening and surveillance programs. These factors, in turn, are set to boost the contrast ultrasound market growth in Asia-Pacific during the forecast period.
The Asia-Pacific contrast ultrasound market growth assessment includes the analysis of China, Japan, India, South Korea, Indonesia, Vietnam, Thailand, Australia & New Zealand, and Rest of Asia-Pacific.
China represents a key market within Asia-Pacific, driven by government initiatives to modernize healthcare infrastructure and expand access to advanced diagnostic services across tier-2 and tier-3 cities. The Healthy China 2030 initiative has allocated substantial funding for medical equipment procurement and clinical training programs, directly supporting the adoption of enhanced ultrasound technology in public hospitals and private imaging centers.
China’s aging population and rising prevalence of chronic conditions, including cardiovascular disease and liver disorders, are creating unprecedented demand for diagnostic imaging services that can be delivered efficiently and cost-effectively. The National Medical Products Administration has implemented regulatory reforms that accelerate approval processes for new contrast agents and imaging devices, enabling faster market entry for both international manufacturers and domestic innovators.
Chinese medical device companies such as Shenzhen Mindray Bio-Medical Electronics are developing sophisticated ultrasound systems with integrated contrast-enhanced imaging capabilities at price points significantly lower than Western competitors, thereby democratizing access to advanced diagnostic technologies. Major hospitals in Beijing, Shanghai, and Guangzhou serve as early adopters and clinical validation centers where new applications for therapeutic applications are being explored through collaborative research programs.
The Chinese government’s emphasis on reducing healthcare costs while improving diagnostic accuracy aligns perfectly with the value proposition of contrast ultrasound, which delivers high-quality imaging without the infrastructure requirements or operational expenses associated with CT and MRI systems. Furthermore, expanding health insurance coverage through programs like Urban Employee Basic Medical Insurance is reducing out-of-pocket costs for patients, making contrast ultrasound procedures more accessible to middle-income populations.
Training initiatives organized by provincial health authorities and professional medical societies are addressing the traditional shortage of skilled sonographers proficient in contrast-enhanced techniques. As a result, this plays a significant role in improving service quality and expanding clinical adoption across diverse healthcare settings.
Japan maintains a mature and technically sophisticated contrast ultrasound market characterized by early clinical adoption, comprehensive reimbursement coverage, and strong domestic manufacturing capabilities. The country’s universal healthcare system, administered through statutory health insurance programs, provides generous reimbursement for contrast ultrasound procedures across multiple clinical indications, including cardiac imaging, liver lesion characterization, and vascular assessments.
Japanese physicians have been early adopters of contrast enhanced ultrasound technology, with clinical practice patterns established over decades of experience using microbubble-based contrast agents for diagnostic applications. Leading medical device companies headquartered in Japan, including Canon Medical Systems and Fujifilm Holdings Corporation, maintain extensive research and development programs focused on integrating artificial intelligence and advanced imaging software into ultrasound platforms designed specifically for Asian patient populations.
Academic medical centers such as the University of Tokyo Hospital and Osaka University Hospital conduct cutting-edge research on novel applications of contrast ultrasound in oncology, including real-time monitoring of tumor response to chemotherapy and assessment of treatment efficacy following interventional radiology procedures. Japan’s aging demographic profile, with approximately 29% of the population aged 65 or older, creates sustained demand for cardiovascular imaging services where contrast ultrasound enables accurate diagnosis of heart failure, valvular disease, and myocardial perfusion abnormalities.
The country’s emphasis on preventive medicine and early disease detection supports the routine use of enhanced ultrasound in screening programs for hepatocellular carcinoma among patients with chronic hepatitis B and C infections. Moreover, Japan’s regulatory environment through the Pharmaceuticals and Medical Devices Agency maintains rigorous safety standards while supporting innovation, ensuring that new contrast agents and imaging technologies undergo thorough evaluation before clinical deployment.
The Asia-Pacific contrast ultrasound market is segmented into product, type, application, and end use. The end use segment is further categorized into hospitals, clinics, and ambulatory diagnostic centers.
The hospitals segment represents the dominant end use category within the Asia-Pacific contrast ultrasound market, accounting for the majority of procedures performed across the region. This segment encompasses tertiary care hospitals, specialty hospitals, and general hospitals that maintain dedicated diagnostic imaging departments equipped with advanced ultrasound systems and trained personnel capable of performing contrast-enhanced studies.
Hospitals serve as the primary setting for complex diagnostic workups requiring contrast ultrasound, particularly for patients with suspected malignancies, cardiovascular abnormalities, or liver diseases that necessitate detailed perfusion assessment and tissue characterization. Large public hospitals in major metropolitan areas across China, Japan, and India have made substantial capital investments in state-of-the-art ultrasound equipment featuring integrated artificial intelligence, quantitative perfusion analysis software, and multi-frequency transducers that optimize image quality for contrast-enhanced applications.
The hospitals segment benefits from centralized procurement systems that enable bulk purchasing of contrast agents at favorable pricing, making advanced diagnostic services more economically viable even in resource-constrained settings. Moreover, teaching hospitals and academic medical centers within this segment play a critical role in clinical education, training the next generation of physicians and sonographers in optimal contrast-enhanced imaging techniques while conducting research studies that expand the evidence base for new clinical indications.
The growing prevalence of oncology programs within Asian hospitals is driving demand for diagnostic applications of contrast ultrasound to characterize liver lesions, assess tumor vascularity, and monitor treatment response in patients undergoing chemotherapy or radiation therapy. Hospitals also serve as referral centers for complex cases requiring multidisciplinary evaluation, where real-time contrast ultrasound findings inform treatment planning discussions among oncologists, surgeons, and interventional radiologists.
Furthermore, the hospitals segment is witnessing increased adoption of portable ultrasound devices with contrast-enhanced capabilities in emergency departments and intensive care units. In this regard, bedside imaging enables rapid diagnosis of life-threatening conditions such as pulmonary embolism, myocardial infarction, and abdominal trauma.
Some of the top players operating in the Asia-Pacific contrast ultrasound market include Shenzhen Mindray Bio-Medical Electronics Co Ltd, GE Healthcare, Siemens Healthineers AG, and Canon Medical Systems Corporation, among others.
Shenzhen Mindray Bio-Medical Electronics Co Ltd, headquartered in Shenzhen, China, is a leading domestic medical device manufacturer with a strong regional presence across the Asia-Pacific markets. The company specializes in developing and manufacturing diagnostic imaging equipment, patient monitoring systems, and in-vitro diagnostic products tailored to the clinical and economic needs of emerging markets. Mindray’s ultrasound portfolio includes advanced systems with contrast-enhanced imaging capabilities designed specifically for hospitals, clinics, and ambulatory diagnostic centers seeking cost-effective alternatives to premium Western brands.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Product, Type, Application, End Use |
| Countries Analyzed | China, India, Japan, Australia & New Zealand, South Korea, Thailand, Indonesia, Vietnam, and Rest of Asia-Pacific |
| Companies Analyzed | GE HealthCare, Bracco Imaging SpA, Lantheus Holdings Inc, Siemens Healthineers AG, Koninklijke Philips NV, Bayer AG, Guerbet, Canon Medical Systems Corporation, Shenzhen Mindray Bio-Medical Electronics Co Ltd, Esaote SpA, FUJIFILM Holdings Corporation, Samsung Healthcare, Daiichi Sankyo Company Limited, Trivitron Healthcare Pvt Ltd, SuperSonic Imagine SA |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- THE CONTRAST ULTRASOUND MARKET IS EXPANDING STEADILY DUE TO RISING ADOPTION OF MICROBUBBLE-BASED IMAGING AGENTS IN CARDIOLOGY AND ONCOLOGY DIAGNOSTICS
- HOSPITALS REPRESENT THE LARGEST END-USER SEGMENT AS CONTRAST-ENHANCED ULTRASOUND IS INCREASINGLY USED FOR REAL-TIME PERFUSION ASSESSMENT
- ASIA-PACIFIC IS EMERGING AS A HIGH-GROWTH REGION DRIVEN BY EXPANDING DIAGNOSTIC INFRASTRUCTURE AND RISING AWARENESS OF NON-IONIZING IMAGING MODALITIES
MARKET DYNAMICS
- KEY DRIVERS
- RISING PREVALENCE OF CARDIOVASCULAR DISEASES AND LIVER DISORDERS IS INCREASING DEMAND FOR ENHANCED DIAGNOSTIC ACCURACY
- GROWING PREFERENCE FOR MINIMALLY INVASIVE AND RADIATION-FREE IMAGING TECHNIQUES IS BOOSTING CONTRAST ULTRASOUND UTILIZATION
- TECHNOLOGICAL ADVANCEMENTS IN ULTRASOUND SYSTEMS ARE IMPROVING IMAGE RESOLUTION AND CLINICAL CONFIDENCE
- EXPANDING CLINICAL APPLICATIONS IN PEDIATRICS AND INTERVENTIONAL RADIOLOGY ARE BROADENING MARKET OPPORTUNITIES
- KEY RESTRAINTS
- LIMITED REIMBURSEMENT COVERAGE IN SEVERAL DEVELOPING MARKETS IS CONSTRAINING ADOPTION RATES
- REGULATORY COMPLEXITIES RELATED TO APPROVAL OF CONTRAST AGENTS CAN DELAY PRODUCT LAUNCHES
- LACK OF AWARENESS AND TRAINING AMONG SONOGRAPHERS MAY LIMIT OPTIMAL UTILIZATION
- COMPETITION FROM ALTERNATIVE IMAGING MODALITIES SUCH AS MRI AND CT SCANS MAY RESTRICT MARKET PENETRATION
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- INCREASING RESEARCH ON TARGETED MICROBUBBLE CONTRAST AGENTS IS DRIVING INNOVATION IN MOLECULAR IMAGING
- GROWING INTEGRATION OF ARTIFICIAL INTELLIGENCE IN ULTRASOUND WORKFLOWS IS ENHANCING DIAGNOSTIC PRECISION
- SHIFT TOWARD POINT-OF-CARE ULTRASOUND DEVICES IS EXPANDING ACCESS TO CONTRAST-ENHANCED STUDIES
- STRATEGIC COLLABORATIONS BETWEEN PHARMACEUTICAL AND MEDICAL DEVICE COMPANIES ARE ACCELERATING PRODUCT DEVELOPMENT
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR ASIA-PACIFIC
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SUPPLIERS
- CONTRAST AGENT MANUFACTURERS
- ULTRASOUND OEMS
- DISTRIBUTION PARTNERS
- HOSPITAL PROCUREMENT
- END-USER FACILITIES
- KEY BUYING CRITERIA
- IMAGE CLARITY
- SAFETY PROFILE
- REGULATORY APPROVAL
- COST EFFECTIVENESS
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
CONTRAST ULTRASOUND MARKET BY PRODUCT
- EQUIPMENT
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- CONTRAST AGENTS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- EQUIPMENT
CONTRAST ULTRASOUND MARKET BY TYPE
- NON-TARGETED
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- TARGETED
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- NON-TARGETED
CONTRAST ULTRASOUND MARKET BY APPLICATION
- DIAGNOSTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- THERAPEUTIC APPLICATIONS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- DIAGNOSTIC APPLICATIONS
CONTRAST ULTRASOUND MARKET BY END USE
- HOSPITALS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- CLINICS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- AMBULATORY DIAGNOSTIC CENTERS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- HOSPITALS
GEOGRAPHICAL ANALYSIS
- ASIA-PACIFIC
- MARKET SIZE & ESTIMATES
- ASIA-PACIFIC MARKET DRIVERS
- ASIA-PACIFIC MARKET CHALLENGES
- KEY PLAYERS IN ASIA-PACIFIC CONTRAST ULTRASOUND MARKET
- COUNTRY ANALYSIS
- CHINA
- CHINA MARKET SIZE & OPPORTUNITIES
- INDIA
- INDIA MARKET SIZE & OPPORTUNITIES
- JAPAN
- JAPAN MARKET SIZE & OPPORTUNITIES
- AUSTRALIA & NEW ZEALAND
- AUSTRALIA & NEW ZEALAND MARKET SIZE & OPPORTUNITIES
- SOUTH KOREA
- SOUTH KOREA MARKET SIZE & OPPORTUNITIES
- THAILAND
- THAILAND MARKET SIZE & OPPORTUNITIES
- INDONESIA
- INDONESIA MARKET SIZE & OPPORTUNITIES
- VIETNAM
- VIETNAM MARKET SIZE & OPPORTUNITIES
- REST OF ASIA-PACIFIC
- REST OF ASIA-PACIFIC MARKET SIZE & OPPORTUNITIES
- CHINA
- ASIA-PACIFIC
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- GE HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- BRACCO IMAGING SPA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- LANTHEUS HOLDINGS INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SIEMENS HEALTHINEERS AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- KONINKLIJKE PHILIPS NV
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- BAYER AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GUERBET
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- CANON MEDICAL SYSTEMS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ESAOTE SPA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- FUJIFILM HOLDINGS CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SAMSUNG HEALTHCARE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- DAIICHI SANKYO COMPANY LIMITED
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- TRIVITRON HEALTHCARE PVT LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SUPERSONIC IMAGINE SA
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GE HEALTHCARE
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – CONTRAST ULTRASOUND
TABLE 2: CONTRAST ULTRASOUND MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY PRODUCT, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY PRODUCT, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: MARKET BY TYPE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: MARKET BY TYPE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: MARKET BY APPLICATION, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: MARKET BY APPLICATION, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: MARKET BY END USE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: MARKET BY END USE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: EUROPE MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 12: EUROPE MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 13: KEY PLAYERS OPERATING IN THE EUROPEAN MARKET
TABLE 14: LIST OF MERGERS & ACQUISITIONS
TABLE 15: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 16: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 17: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR EUROPE
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY PRODUCT, IN 2025
FIGURE 11: EQUIPMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: CONTRAST AGENTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY TYPE, IN 2025
FIGURE 14: NON-TARGETED MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: TARGETED MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: SEGMENT GROWTH POTENTIAL, BY APPLICATION, IN 2025
FIGURE 17: DIAGNOSTIC APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: THERAPEUTIC APPLICATIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: SEGMENT GROWTH POTENTIAL, BY END USE, IN 2025
FIGURE 20: HOSPITALS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: CLINICS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: AMBULATORY DIAGNOSTIC CENTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: EUROPE CONTRAST ULTRASOUND MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 24: GERMANY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: UNITED KINGDOM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: FRANCE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: ITALY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: SPAIN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 29: BELGIUM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: POLAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: REST OF EUROPE MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-
EUROPE SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
NORTH AMERICA SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
SPAIN ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
MEXICO ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
ITALY ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
AUSTRALIA ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034
-
BRAZIL ADVANCED DELIVERY NUTRACEUTICALS MARKET FORECAST 2026-2034