The United Kingdom Acute Care at Home Market by Service Type (Physician Care Services, Skilled Nursing Services, Diagnostic & Monitoring Services, Therapy Services, Medication Administration Services, Other Acute Care Services) Market by Component (Remote Patient Monitoring Devices, Telehealth & Virtual Care Platforms, Clinical Command Center Software, Therapeutic Equipment, Other Components) Market by Disease Indication (Respiratory Diseases, Cardiovascular Diseases, Infectious Diseases, Renal Disorders, Post-Surgical Care, Other Acute Conditions), by Geography
UNITED KINGDOM ACUTE CARE AT HOME MARKET OVERVIEW
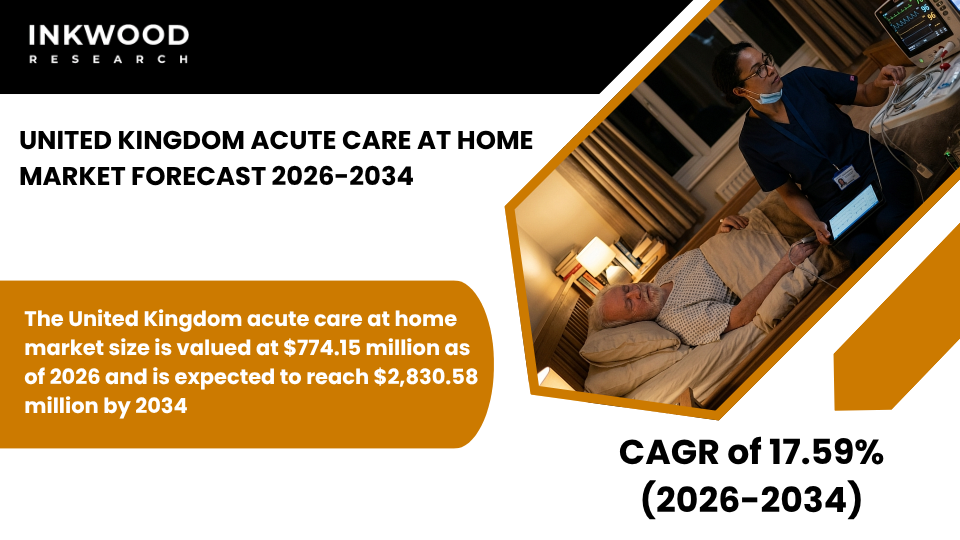
The United Kingdom acute care at home market size is valued at $774.15 million as of 2026 and is expected to reach $2,830.58 million by 2034, progressing with a CAGR of 17.59% during the forecast years, 2026–2034.
MARKET INSIGHTS
The United Kingdom represents one of the most institutionally driven markets for acute home healthcare globally, with the National Health Service (NHS) playing a central and defining role in shaping demand. The NHS virtual ward model, which delivers hospital-level acute care to patients in their own homes through remote monitoring and coordinated clinical teams, has become a cornerstone of the UK’s strategy to ease hospital capacity pressures.
According to NHS England, virtual wards are now available across every Integrated Care System (ICS) in England. The previous government set and met a target of 10,000 virtual ward beds by September 2023, and the number continued to grow, reaching 12,497 virtual beds by September 2024, an increase of 19.9% year-on-year.
Furthermore, in May 2024, NHS England committed £150 million in additional funding to enhance virtual ward capacity, with an explicit target of maintaining occupancy levels above 80%. These policy commitments provide a strong structural foundation for the United Kingdom’s acute care at home market during the forecast period.
Real-world program outcomes are reinforcing the clinical and economic case for continued investment in home-based acute care across the UK. According to an NHS England evaluation of the South East region, virtual wards generated savings exceeding £10 million by reducing hospital admissions and bed usage.
Additionally, Medway NHS Foundation Trust reported that the same level of care delivered in a hospital costs approximately £657 per day, compared to just £187 per day on a virtual ward, representing a cost saving of over £100,000 in just six months. Moreover, a virtual ward partnership involving South West London NHS Trusts demonstrated reductions in hospital length of stay by two to three days per patient.
These outcomes are compelling for NHS commissioners and Integrated Care Boards (ICBs) alike. For investors and vendors operating in the UK hospital at home market, they underscore a clear commercial opportunity in expanding remote monitoring infrastructure, telehealth platforms, and clinical software tools that support scalable, cost-efficient acute care delivery outside hospital walls.
Despite this momentum, the UK acute care at home services market faces tangible constraints that vendors and policymakers must navigate. The ending of ring-fenced virtual ward funding in March 2024 caused a notable slowdown in program expansion, with growth in occupied virtual beds slowing between January and May 2024, compared to the preceding five months, per the NHS Support Federation.
Workforce shortages, particularly in skilled nursing and allied health professions, also remain a persistent operational barrier. Additionally, data interoperability challenges across NHS Trusts and ICBs continue to hinder seamless care coordination. Nevertheless, the NHS’s 2025/26 Priorities and Operational Planning Guidance continues to mandate that ICSs embed and standardise virtual ward capacity in line with local demand.
Meanwhile, in Scotland, the government committed to expanding its Hospital at Home initiative to at least 2,000 beds by the end of 2026, according to Digital Health. Together, these factors are set to sustain and accelerate the acute care at home market growth in the United Kingdom during the forecast period.
To Know More About This Report, Request a Free Sample Copy
SEGMENTATION ANALYSIS
The United Kingdom acute care at home market is segmented by service type, component, and disease indication. The service type segment is further categorized into physician care services, skilled nursing services, diagnostic and monitoring services, therapy services (physical, occupational, and respiratory), medication administration services, and other acute care services.
Diagnostic and monitoring services represent one of the fastest-growing and most strategically important sub-segments in the United Kingdom acute care at home market. This sub-segment encompasses the deployment of clinical-grade remote monitoring devices, point-of-care testing tools, and wearable sensors that enable continuous or periodic assessment of patient vitals, oxygen saturation, heart rate, and other key indicators from within the home setting.
In the UK context, this sub-segment sits at the operational heart of the NHS virtual ward model, as real-time patient data feeds directly into clinical command centers where multidisciplinary teams make treatment decisions remotely. The NHS England operational framework explicitly identifies remote monitoring as a core component of all virtual ward pathways, covering conditions including acute respiratory infections, heart failure, and frailty.
Furthermore, with NHS Trusts increasingly adopting structured monitoring platforms, demand for integrated diagnostics solutions that connect seamlessly with existing electronic patient record (EPR) systems is growing rapidly. For technology vendors, this sub-segment represents a high-priority growth opportunity within the UK home-based acute care market, particularly as NHS ICBs seek to standardize and scale their monitoring capabilities across diverse patient populations.
COMPETITIVE INSIGHTS
Some of the top players operating in the United Kingdom acute care at home market include Philips Healthcare, HomeLink Healthcare, HFH Healthcare, and Acacium Group, among others.
Philips Healthcare is a global medical technology company headquartered in Amsterdam, Netherlands, with a well-established commercial presence across NHS England and affiliated UK health systems. In the context of the UK acute home healthcare market, Philips delivers a portfolio of remote patient monitoring devices, telehealth platforms, and connected care solutions designed to support hospital-at-home and virtual ward programs.
The company’s offerings include clinical decision support software, wearable biosensors, and enterprise-grade monitoring systems that integrate with NHS digital infrastructure. Philips’ established relationships with NHS Trusts, combined with its broad product range spanning diagnostics, patient monitoring, and care coordination technology, position it as a key enabler of scalable acute care home services within the UK market.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Service Type, Component, Disease Indication |
| Country Analyzed | The United Kingdom |
| Companies Analyzed | HomeLink Healthcare, The Home Hospital, Bridgewater Home Care, Helping Hands, Right at Home, The Good Care Group, Sova Healthcare, Medelit, HFH Healthcare, Acacium Group, Philips Healthcare |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE, SHARE & ESTIMATES
- MARKET OVERVIEW
- SCOPE OF STUDY
- MAJOR MARKET FINDINGS
- THE UNITED KINGDOM ACUTE CARE AT HOME MARKET IS GROWING STEADILY UNDER NHS INITIATIVES PROMOTING COMMUNITY-BASED CARE
- VIRTUAL WARDS AND REMOTE MONITORING PROGRAMS ARE BECOMING CENTRAL TO HOME-BASED ACUTE CARE DELIVERY
- INTEGRATED CARE SYSTEMS ARE PLAYING A KEY ROLE IN COORDINATING MULTIDISCIPLINARY HOME CARE SERVICES
- PUBLIC HEALTH FUNDING AND DIGITAL HEALTH ADOPTION ARE SUPPORTING MARKET DEVELOPMENT
MARKET DYNAMICS
- KEY DRIVERS
- NHS POLICIES FAVORING OUT-OF-HOSPITAL CARE ARE DRIVING ACUTE CARE AT HOME ADOPTION
- INCREASING PRESSURE ON HOSPITAL CAPACITY IS ENCOURAGING USE OF VIRTUAL WARDS
- AGING POPULATION AND RISING PREVALENCE OF CHRONIC CONDITIONS ARE FUELING DEMAND
- DIGITAL HEALTH INFRASTRUCTURE INVESTMENTS ARE ENABLING SCALABLE HOME CARE SOLUTIONS
- KEY RESTRAINTS
- LIMITED HEALTHCARE WORKFORCE AVAILABILITY CONSTRAINS SERVICE DELIVERY CAPACITY
- BUDGET CONSTRAINTS WITHIN THE NHS LIMIT LARGE-SCALE PROGRAM EXPANSION
- DATA INTEGRATION AND INTEROPERABILITY CHALLENGES HINDER SEAMLESS CARE DELIVERY
- VARIABILITY IN REGIONAL IMPLEMENTATION OF VIRTUAL WARDS AFFECTS MARKET UNIFORMITY
- KEY DRIVERS
STRATEGIC MARKET ANALYTICS
- GROWTH METRICS
- TAM, SAM & SOM OPPORTUNITY ANALYSIS
- EMERGING MARKET TRENDS & PARADIGM SHIFTS
- EXPANSION OF VIRTUAL WARD PROGRAMS IS TRANSFORMING ACUTE CARE DELIVERY IN THE UK
- INCREASED USE OF REMOTE MONITORING DEVICES IS IMPROVING PATIENT MANAGEMENT AT HOME
- COLLABORATION BETWEEN NHS TRUSTS AND DIGITAL HEALTH PROVIDERS IS RISING
- FOCUS ON REDUCING HOSPITAL STAYS IS DRIVING POLICY SUPPORT FOR HOME-BASED CARE
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- PESTLE ANALYSIS
- POLITICAL
- ECONOMIC
- SOCIAL LANDSCAPE
- TECHNOLOGY
- LEGAL
- ENVIRONMENTAL
- GROWTH OPPORTUNITY MAPPING & HEATMAP
- GROWTH PROSPECT MAPPING FOR THE UNITED KINGDOM
- MARKET MATURITY & LIFECYCLE ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- GROWTH METRICS
ACUTE CARE AT HOME VALUE CHAIN & DECISION FRAMEWORK
- VALUE CHAIN ANALYSIS
- MEDICAL DEVICE SUPPLIERS
- TECHNOLOGY PROVIDERS
- HEALTHCARE PROVIDERS
- HOME CARE SERVICES
- PAYERS INSURERS
- PATIENT MONITORING
- KEY BUYING CRITERIA
- CLINICAL EFFECTIVENESS
- COST EFFICIENCY
- TECHNOLOGY INTEGRATION
- PATIENT SAFETY
- PRICING MODELS, REIMBURSEMENT STRUCTURES & CARE DELIVERY OPTIMIZATION STRATEGIES
- REGULATORY & POLICY LANDSCAPE ANALYSIS
- VALUE CHAIN ANALYSIS
ACUTE CARE AT HOME MARKET BY SERVICE TYPE
- PHYSICIAN CARE SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SKILLED NURSING SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- DIAGNOSTIC & MONITORING SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- THERAPY SERVICES (PHYSICAL / OCCUPATIONAL / RESPIRATORY)
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- MEDICATION ADMINISTRATION SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER ACUTE CARE SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PHYSICIAN CARE SERVICES
ACUTE CARE AT HOME MARKET BY COMPONENT
- REMOTE PATIENT MONITORING DEVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- TELEHEALTH & VIRTUAL CARE PLATFORMS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- CLINICAL COMMAND CENTER SOFTWARE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- THERAPEUTIC EQUIPMENT
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER COMPONENTS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- REMOTE PATIENT MONITORING DEVICES
ACUTE CARE AT HOME MARKET BY DISEASE INDICATION
- RESPIRATORY DISEASES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- CARDIOVASCULAR DISEASES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- INFECTIOUS DISEASES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- RENAL DISORDERS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- POST-SURGICAL CARE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER ACUTE CONDITIONS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- RESPIRATORY DISEASES
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPETITOR POSITIONING & DIFFERENTIATION MAP
- COMPANY PROFILES
- HOMELINK HEALTHCARE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- THE HOME HOSPITAL
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- BRIDGEWATER HOME CARE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- HELPING HANDS
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- RIGHT AT HOME
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- THE GOOD CARE GROUP
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- SOVA HEALTHCARE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- MEDELIT
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- HFH HEALTHCARE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- ACACIUM GROUP
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- PHILIPS HEALTHCARE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- HOMELINK HEALTHCARE
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – ACUTE CARE AT HOME MARKET
TABLE 2: PRICING MODELS, REIMBURSEMENT STRUCTURES & CARE DELIVERY OPTIMIZATION STRATEGIES
TABLE 3: REGULATORY & POLICY LANDSCAPE ANALYSIS
TABLE 4: MARKET BY SERVICE TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 5: MARKET BY SERVICE TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 6: MARKET BY COMPONENT, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 7: MARKET BY COMPONENT, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 8: MARKET BY DISEASE INDICATION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 9: MARKET BY DISEASE INDICATION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 10: KEY PLAYERS OPERATING IN THE UNITED KINGDOM MARKET
TABLE 11: LIST OF MERGERS & ACQUISITIONS
TABLE 12: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 13: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 14: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR THE UNITED KINGDOM
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY SERVICE TYPE, IN 2025
FIGURE 11: PHYSICIAN CARE SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: SKILLED NURSING SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: DIAGNOSTIC & MONITORING SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 14: THERAPY SERVICES (PHYSICAL / OCCUPATIONAL / RESPIRATORY) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: MEDICATION ADMINISTRATION SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: OTHER ACUTE CARE SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: SEGMENT GROWTH POTENTIAL, BY COMPONENT, IN 2025
FIGURE 18: REMOTE PATIENT MONITORING DEVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: TELEHEALTH & VIRTUAL CARE PLATFORMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: CLINICAL COMMAND CENTER SOFTWARE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: THERAPEUTIC EQUIPMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: OTHER COMPONENTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: SEGMENT GROWTH POTENTIAL, BY DISEASE INDICATION, IN 2025
FIGURE 24: RESPIRATORY DISEASES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: CARDIOVASCULAR DISEASES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: INFECTIOUS DISEASES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: RENAL DISORDERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: POST-SURGICAL CARE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 29: OTHER ACUTE CONDITIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
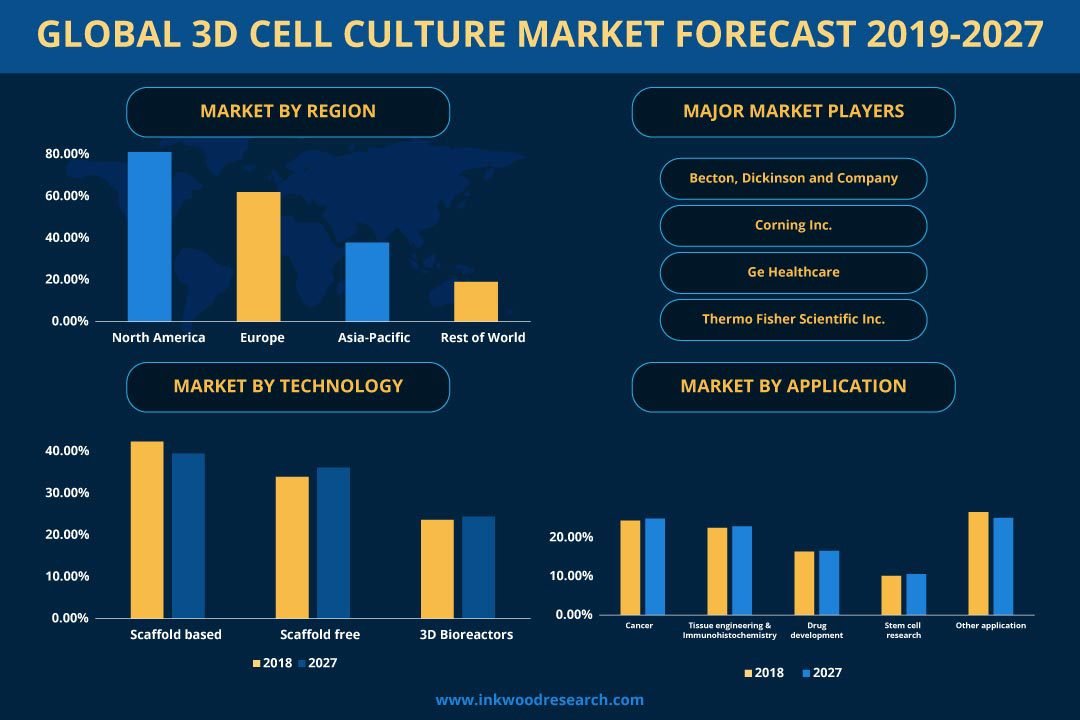
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
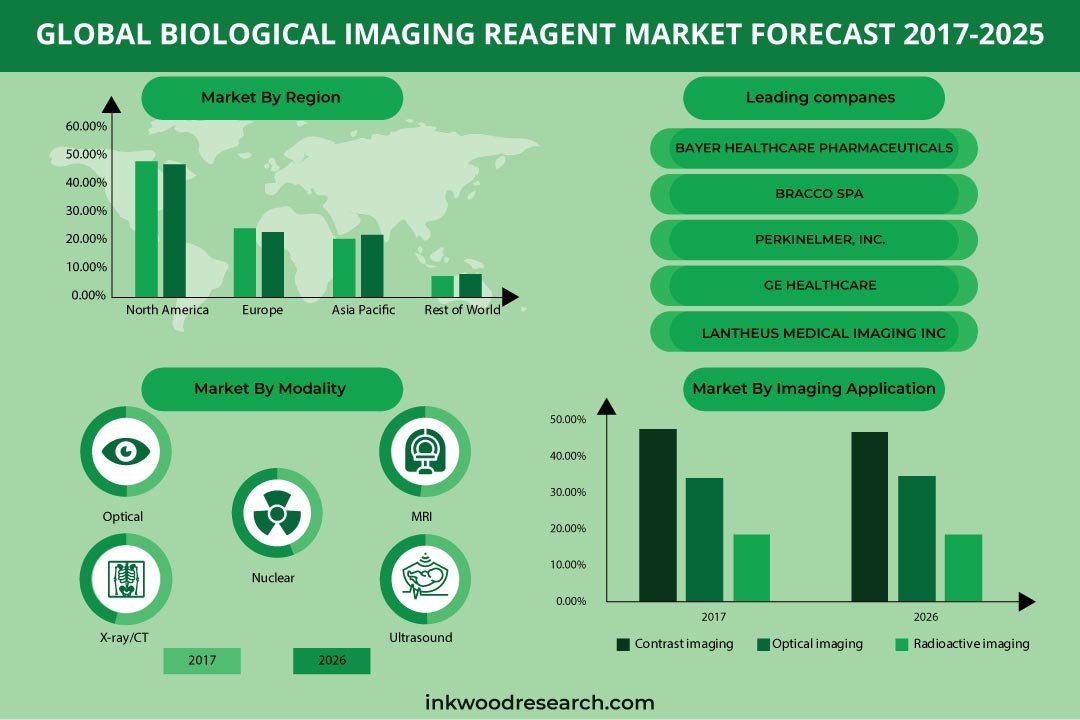
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034