
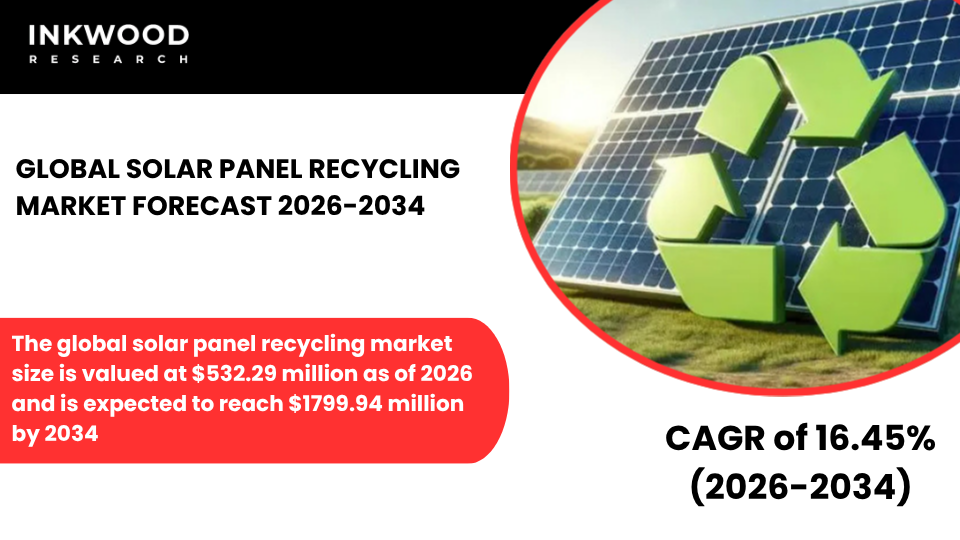
GLOBAL SOLAR PANEL RECYCLING MARKET FORECAST 2026-2034
SCOPE OF THE REPORT
Global Solar Panel Recycling Market by Process (Thermal, Mechanical, Chemical, Laser) Market by Type (Silicon-Based C-Si, Thin-Film, Other Types) Market by Shelf Life (Early Loss, Normal Loss) Market by Material/Recoverable Components (Glass, Aluminum, Copper, Plastic, Silver, PV Silicon, Other Materials/Recoverable Components), by Geography
GLOBAL SOLAR PANEL RECYCLING MARKET OVERVIEW
The global solar panel recycling market size is valued at $532.29 million as of 2026 and is expected to reach $1799.94 million by 2034, growing at a CAGR of 16.45% during the forecast period 2026-2034. The base year considered for the study is 2025, and the forecast period is between 2026 and 2034. The market study has also analyzed the crisis impact on the solar panel recycling market qualitatively as well as quantitatively.
Solar panel recycling represents the systematic process of recovering valuable materials from decommissioned photovoltaic PV panels at the end of their operational shelf life. This specialized waste management sector employs various recycling processes, including thermal, mechanical, chemical, and laser-based techniques to extract silicon, silver, aluminum, glass, and copper.
As solar energy capacity expands globally, panel recycling has emerged as an essential component of sustainable energy infrastructure. The industry addresses both early loss panels damaged during manufacturing or installation and normal loss panels reaching their 25-30 year operational lifespan. According to the International Renewable Energy Agency, solar panel waste could reach substantial volumes by 2050, making efficient material recovery systems increasingly vital for resource conservation and environmental protection.
The market’s rapid expansion stems from escalating solar installations worldwide and aging first-generation panels now reaching retirement. Furthermore, stringent environmental regulations across developed economies mandate proper disposal rather than landfilling. Additionally, technological breakthroughs in recycling techniques have significantly improved material recovery rates while reducing processing costs.
Government incentives and subsidies across Europe, Asia-Pacific, and North America are encouraging private sector investments in recycling infrastructure. Moreover, growing awareness about circular economy principles among solar manufacturers has catalyzed partnerships with specialized recycling companies. The demand for efficient recycling methods continues to rise as the solar industry matures and sustainability becomes a competitive differentiator.
To Know More About This Report, Request a Free Sample Copy
GROWTH ENABLERS
Key enablers of the global solar panel recycling market growth:
- Rising global solar capacity and retirement of old panels increase recycling demand
- Stringent environmental regulations promote sustainable disposal of solar waste
- Improvements in recycling technologies reduce cost and increase material recovery
- Government incentives and subsidies encourage investments in solar panel recycling infrastructure
- Government incentives and subsidies are fundamentally reshaping the solar panel recycling landscape by reducing financial barriers for facility establishment. Tax credits, grants, and low-interest loans enable companies to invest in advanced recycling equipment and automated systems. Consequently, businesses can achieve faster return on investment despite high initial capital requirements.
- European Union directives, particularly the Waste Electrical and Electronic Equipment (WEEE) Directive, mandate producer responsibility for panel end-of-life management. Similarly, several Asian nations have introduced subsidy programs specifically targeting photovoltaic recycling infrastructure development. These policy frameworks create predictable revenue streams for recycling companies, thereby attracting both domestic and international investors into the sector.
Key growth restraining factors of the global solar panel recycling market:
- High capital costs for installing recycling facilities limit market expansion
- Lack of standardization in panel design makes recycling processes complex
- Insufficient awareness about solar panel end-of-life management reduces collection rates
- Transportation and logistics challenges increase overall recycling costs
- Transportation and logistics challenges significantly elevate overall solar panel recycling costs, particularly affecting profitability in geographically dispersed markets. Panels are bulky, fragile, and require specialized handling during collection and transport to prevent breakage.
- Additionally, many solar installations are located in remote areas, increasing fuel costs and transit times. The weight and volume of decommissioned panels necessitate dedicated logistics infrastructure, which smaller recyclers struggle to maintain.
- Moreover, regulatory requirements for hazardous material transport add compliance costs and operational complexity. These combined factors create substantial cost barriers, especially for emerging markets where recycling infrastructure remains underdeveloped, thereby slowing market penetration and limiting accessibility for smaller solar farm operators.
KEY MARKET TRENDS
Global Solar Panel Recycling Industry | Top Trends
- Automation technologies are revolutionizing solar panel recycling operations by enhancing processing speed and material recovery precision. Robotic systems equipped with advanced sensors can identify and separate different panel components more efficiently than manual methods. Consequently, operational costs decline while throughput increases substantially. Companies deploying automated mechanical thermal laser techniques report significantly higher recovery rates for valuable materials like silicon and silver. Furthermore, these systems minimize worker exposure to potentially hazardous materials, improving workplace safety standards. The integration of artificial intelligence enables predictive maintenance and process optimization, making large-scale recycling operations economically viable.
- Strategic alliances between photovoltaic manufacturers and specialized recycling companies are becoming increasingly common across the solar energy sector. These collaborations create closed-loop systems where manufacturers design panels with end-of-life recyclability in mind. Meanwhile, recyclers gain access to predictable material streams and technical specifications that streamline processing. For instance, First Solar has established comprehensive take-back programs ensuring its panels return to dedicated facilities. Such partnerships reduce waste management costs for solar farm operators while guaranteeing secondary material supply for new panel manufacturing. Additionally, these arrangements strengthen brand reputation among environmentally conscious customers and investors.
- The circular economy principle is gaining substantial traction as manufacturers increasingly incorporate recycled materials into new photovoltaic panel production. Recovered silicon, aluminum, and glass meet quality standards for manufacturing applications when properly processed through advanced purification techniques. This trend reduces reliance on virgin material extraction, lowering both environmental impact and production costs. Moreover, supply chain disruptions have highlighted the strategic importance of secondary material sources for manufacturing resilience. According to industry reports, using recycled materials can reduce panel production costs while maintaining performance specifications. Companies embracing this approach simultaneously address sustainability goals and enhance profit margins through reduced raw material expenses.
- Environmental concerns are driving innovation toward chemical-free recycling techniques that minimize the ecological footprint during material recovery operations. Traditional chemical recycling methods often generate hazardous waste streams requiring additional treatment and disposal. Therefore, thermal and mechanical processes are gaining preference for their reduced environmental impact. Laser-based technologies represent the cutting edge, enabling precise material separation without chemical solvents. Furthermore, these cleaner methods align with increasingly stringent environmental regulations and corporate sustainability commitments. Companies adopting eco-friendly recycling processes enhance their competitive positioning while meeting stakeholder expectations for responsible waste management practices across the solar energy value chain.
MARKET SEGMENTATION
Market Segmentation – Process, Type, Shelf Life, and Material/Recoverable Components –
Market by Process:
- Thermal
- Thermal recycling employs high-temperature processes to separate and recover materials from photovoltaic PV panels through controlled heating methods. This technique effectively removes polymer-based encapsulants and backsheets, allowing subsequent recovery of glass, metals, and silicon wafers. The process operates at temperatures typically ranging between 400-600°C in specialized furnaces designed for solar panel processing.
- Thermal methods excel at processing large volumes quickly, making them economically attractive for high-capacity facilities. Additionally, this approach generates minimal chemical waste compared to solvent-based alternatives, aligning with environmental compliance requirements.
- Demand for thermal recycling continues to grow as operators seek cost-effective solutions for processing diverse panel types simultaneously. Recent technological improvements have enhanced energy efficiency and reduced processing times significantly. Moreover, thermal techniques can handle panels with various construction designs without extensive pre-sorting requirements.
- Regulatory pressures favoring clean recycling methods further accelerate adoption across Europe and Asia-Pacific markets. This sub-segment supports overall market growth by providing scalable, environmentally responsible material recovery that meets stringent environmental regulations while delivering acceptable recovery rates for valuable materials like silicon, silver, and aluminum.
- Mechanical
- Chemical
- Laser
Market by Type:
- Silicon-Based (C-Si)
- Thin-Film
- Other Types
Market by Shelf Life:
- Early Loss
- Normal Loss
Market by Material/Recoverable Components:
- Glass
- Aluminum
- Copper
- Plastic
- Silver
- PV Silicon
- Other Materials/Recoverable Components
Geographical Study based on Four Major Regions:
- North America: The United States and Canada
- Europe: The United Kingdom, Germany, France, Italy, Spain, Poland, Belgium, and Rest of Europe
- Asia-Pacific: China, India, Japan, Australia & New Zealand, South Korea, Thailand, Indonesia, Vietnam, and Rest of Asia-Pacific
- China’s solar panel recycling market is experiencing rapid development driven by massive photovoltaic installations and proactive government policies addressing renewable energy waste management. As the world’s largest solar panel manufacturer and consumer, China faces mounting volumes of decommissioned panels requiring proper disposal.
- Government initiatives under the 14th Five-Year Plan emphasize circular economy development, specifically targeting solar waste reduction. Consequently, domestic recycling companies are investing heavily in advanced mechanical thermal laser technologies to maximize material recovery efficiency.
- However, challenges persist regarding collection infrastructure in rural areas where many installations exist. Nevertheless, partnerships between manufacturers like JA Solar and specialized recyclers are establishing comprehensive take-back systems.
- Furthermore, China’s dominance in polycrystalline and monocrystalline solar panel production creates substantial opportunities for recovering high-purity silicon for remanufacturing applications, positioning the nation as a global leader in photovoltaic recycling innovation.
- Rest of World: Latin America, the Middle East & Africa
Our market research reports offer an in-depth analysis of individual country-level market size and growth statistics. We cover the segmentation analysis, key growth factors, and macro-economic trends within the solar panel recycling market, providing detailed insights into:
MAJOR PLAYERS
The major players in the global solar panel recycling market are:
- Aurubis AG
- Canadian Solar Inc
- ECS Refining
- Envela Corporation
- First Solar Inc
Key strategies adopted by some of these companies:
- First Solar expanded its global recycling network through partnerships with European waste management specialists, enabling comprehensive panel collection across multiple countries. This collaboration strengthens the company’s closed-loop manufacturing system while reducing logistics costs. The initiative demonstrates how vertical integration in solar panel recycling creates competitive advantages through guaranteed secondary material access.
- Canadian Solar commissioned a state-of-the-art recycling facility in Asia, incorporating automated sorting and mechanical thermal processing capabilities. This investment addresses growing panel retirement volumes while recovering valuable silicon and aluminum for reuse. The facility’s advanced technology achieves recovery rates exceeding industry standards, establishing new benchmarks for resource efficiency in photovoltaic recycling.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Process, Type, Shelf Life, and Material / Recoverable Components |
| Geographies Analyzed | North America, Europe, Asia-Pacific, Rest of World |
| Companies Analyzed | Aurubis AG, Canadian Solar Inc, ECS Refining, Envela Corporation, First Solar Inc, Hanwha Group, JA Solar Co Ltd, Reiling Group, Rinovasol Group, Sharp Corporation, SiC Processing GmbH, Silcontel Ltd, Silrec Corporation, Trina Solar, Yingli Energy Co |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY & KEY INSIGHTS
- MARKET SIZE, SHARE & ESTIMATES
- MARKET OVERVIEW
- SCOPE OF STUDY
- MAJOR MARKET FINDINGS
- THE MARKET IS EXPERIENCING RAPID GROWTH DUE TO INCREASING SOLAR PANEL INSTALLATIONS WORLDWIDE
- EUROPE AND ASIA-PACIFIC ARE LEADING REGIONS DRIVING SOLAR PANEL RECYCLING INITIATIVES
- TECHNOLOGICAL ADVANCEMENTS IN RECYCLING PROCESSES ARE IMPROVING MATERIAL RECOVERY EFFICIENCY
- GOVERNMENT POLICIES AND REGULATIONS ARE MANDATING PROPER DISPOSAL AND RECYCLING OF SOLAR PANELS
MARKET DYNAMICS
- KEY DRIVERS
- RISING GLOBAL SOLAR CAPACITY AND RETIREMENT OF OLD PANELS INCREASE RECYCLING DEMAND
- STRINGENT ENVIRONMENTAL REGULATIONS PROMOTE SUSTAINABLE DISPOSAL OF SOLAR WASTE
- IMPROVEMENTS IN RECYCLING TECHNOLOGIES REDUCE COST AND INCREASE MATERIAL RECOVERY
- GOVERNMENT INCENTIVES AND SUBSIDIES ENCOURAGE INVESTMENTS IN SOLAR PANEL RECYCLING INFRASTRUCTURE
- KEY RESTRAINTS
- HIGH CAPITAL COSTS FOR INSTALLING RECYCLING FACILITIES LIMIT MARKET EXPANSION
- LACK OF STANDARDIZATION IN PANEL DESIGN MAKES RECYCLING PROCESSES COMPLEX
- INSUFFICIENT AWARENESS ABOUT SOLAR PANEL END-OF-LIFE MANAGEMENT REDUCES COLLECTION RATES
- TRANSPORTATION AND LOGISTICS CHALLENGES INCREASE OVERALL RECYCLING COSTS
- KEY DRIVERS
STRATEGIC MARKET ANALYTICS
- KEY MARKET TRENDS
- EMERGENCE OF AUTOMATED AND ROBOTIC RECYCLING SYSTEMS INCREASES OPERATIONAL EFFICIENCY
- PARTNERSHIPS BETWEEN SOLAR MANUFACTURERS AND RECYCLERS ARE BECOMING COMMON
- INCREASING USE OF SECONDARY MATERIALS IN NEW PANEL MANUFACTURING DRIVES CIRCULAR ECONOMY
- FOCUS ON ECO-FRIENDLY AND CHEMICAL-FREE RECYCLING PROCESSES IS GAINING TRACTION
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR NORTH AMERICA
- GROWTH PROSPECT MAPPING FOR EUROPE
- GROWTH PROSPECT MAPPING FOR ASIA-PACIFIC
- GROWTH PROSPECT MAPPING FOR REST OF WORLD
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SUPPLY
- COLLECTION AND LOGISTICS
- DISMANTLING AND SHREDDING
- MATERIAL SORTING
- CHEMICAL PROCESSING
- RECOVERED MATERIAL SUPPLY
- KEY BUYING CRITERIA
- RECYCLING EFFICIENCY
- COST COMPETITIVENESS
- ENVIRONMENTAL COMPLIANCE
- TECHNOLOGICAL ADVANCEMENT
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
SOLAR PANEL RECYCLING MARKET BY PROCESS
- THERMAL
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- MECHANICAL
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- CHEMICAL
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- LASER
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- THERMAL
SOLAR PANEL RECYCLING MARKET BY TYPE
- SILICON-BASED (C-SI)
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- THIN-FILM
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- OTHER TYPES
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- SILICON-BASED (C-SI)
SOLAR PANEL RECYCLING MARKET BY SHELF LIFE
- EARLY LOSS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- NORMAL LOSS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- EARLY LOSS
SOLAR PANEL RECYCLING MARKET BY MATERIAL / RECOVERABLE COMPONENTS
- GLASS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- ALUMINUM
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- COPPER
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- PLASTIC
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- SILVER
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- PV SILICON
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- OTHER MATERIALS / RECOVERABLE COMPONENTS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- GLASS
GEOGRAPHICAL ANALYSIS
- NORTH AMERICA
- MARKET SIZE & ESTIMATES
- NORTH AMERICA MARKET DRIVERS
- NORTH AMERICA MARKET CHALLENGES
- KEY PLAYERS IN NORTH AMERICA SOLAR PANEL RECYCLING MARKET
- COUNTRY ANALYSIS
- UNITED STATES
- UNITED STATES MARKET SIZE & OPPORTUNITIES
- CANADA
- CANADA MARKET SIZE & OPPORTUNITIES
- UNITED STATES
- EUROPE
- MARKET SIZE & ESTIMATES
- EUROPE MARKET DRIVERS
- EUROPE MARKET CHALLENGES
- KEY PLAYERS IN EUROPE SOLAR PANEL RECYCLING MARKET
- COUNTRY ANALYSIS
- GERMANY
- GERMANY MARKET SIZE & OPPORTUNITIES
- UNITED KINGDOM
- UNITED KINGDOM MARKET SIZE & OPPORTUNITIES
- FRANCE
- FRANCE MARKET SIZE & OPPORTUNITIES
- ITALY
- ITALY MARKET SIZE & OPPORTUNITIES
- SPAIN
- SPAIN MARKET SIZE & OPPORTUNITIES
- BELGIUM
- BELGIUM MARKET SIZE & OPPORTUNITIES
- POLAND
- POLAND MARKET SIZE & OPPORTUNITIES
- REST OF EUROPE
- REST OF EUROPE MARKET SIZE & OPPORTUNITIES
- GERMANY
- ASIA-PACIFIC
- MARKET SIZE & ESTIMATES
- ASIA-PACIFIC MARKET DRIVERS
- ASIA-PACIFIC MARKET CHALLENGES
- KEY PLAYERS IN ASIA-PACIFIC SOLAR PANEL RECYCLING MARKET
- COUNTRY ANALYSIS
- CHINA
- CHINA MARKET SIZE & OPPORTUNITIES
- INDIA
- INDIA MARKET SIZE & OPPORTUNITIES
- JAPAN
- JAPAN MARKET SIZE & OPPORTUNITIES
- AUSTRALIA & NEW ZEALAND
- AUSTRALIA & NEW ZEALAND MARKET SIZE & OPPORTUNITIES
- SOUTH KOREA
- SOUTH KOREA MARKET SIZE & OPPORTUNITIES
- THAILAND
- THAILAND MARKET SIZE & OPPORTUNITIES
- INDONESIA
- INDONESIA MARKET SIZE & OPPORTUNITIES
- VIETNAM
- VIETNAM MARKET SIZE & OPPORTUNITIES
- REST OF ASIA-PACIFIC
- REST OF ASIA-PACIFIC MARKET SIZE & OPPORTUNITIES
- CHINA
- REST OF WORLD
- MARKET SIZE & ESTIMATES
- REST OF WORLD MARKET DRIVERS
- REST OF WORLD MARKET CHALLENGES
- KEY PLAYERS IN REST OF WORLD SOLAR PANEL RECYCLING MARKET
- REGIONAL ANALYSIS
- LATIN AMERICA
- LATIN AMERICA MARKET SIZE & OPPORTUNITIES
- MIDDLE EAST & AFRICA
- MIDDLE EAST & AFRICA MARKET SIZE & OPPORTUNITIES
- LATIN AMERICA
- NORTH AMERICA
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPETITOR POSITIONING & DIFFERENTIATION MAP
- COMPANY PROFILES
- AURUBIS AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- CANADIAN SOLAR INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ECS REFINING
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ENVELA CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- FIRST SOLAR INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- HANWHA GROUP
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- JA SOLAR CO LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- REILING GROUP
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- RINOVASOL GROUP
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SHARP CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SIC PROCESSING GMBH
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SILCONTEL LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SILREC CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- TRINA SOLAR
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- YINGLI ENERGY CO
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- AURUBIS AG
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – SOLAR PANEL RECYCLING
TABLE 2: SOLAR PANEL RECYCLING MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY PROCESS, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY PROCESS, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: THERMAL MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: THERMAL MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: MECHANICAL MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: MECHANICAL MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: CHEMICAL MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: CHEMICAL MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: LASER MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 12: LASER MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 13: MARKET BY TYPE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 14: MARKET BY TYPE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 15: SILICON-BASED (C-SI) MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 16: SILICON-BASED (C-SI) MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 17: THIN-FILM MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 18: THIN-FILM MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 19: OTHER TYPES MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 20: OTHER TYPES MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 21: MARKET BY SHELF LIFE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 22: MARKET BY SHELF LIFE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 23: EARLY LOSS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 24: EARLY LOSS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 25: NORMAL LOSS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 26: NORMAL LOSS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 27: MARKET BY MATERIAL / RECOVERABLE COMPONENTS, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 28: MARKET BY MATERIAL / RECOVERABLE COMPONENTS, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 29: GLASS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 30: GLASS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 31: ALUMINUM MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 32: ALUMINUM MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 33: COPPER MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 34: COPPER MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 35: PLASTIC MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 36: PLASTIC MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 37: SILVER MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 38: SILVER MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 39: PV SILICON MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 40: PV SILICON MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 41: OTHER MATERIALS / RECOVERABLE COMPONENTS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 42: OTHER MATERIALS / RECOVERABLE COMPONENTS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 43: MARKET BY GEOGRAPHICAL ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 44: MARKET BY GEOGRAPHICAL ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 45: NORTH AMERICA MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 46: NORTH AMERICA MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 47: KEY PLAYERS OPERATING IN THE NORTH AMERICAN MARKET
TABLE 48: EUROPE MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 49: EUROPE MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 50: KEY PLAYERS OPERATING IN THE EUROPEAN MARKET
TABLE 51: ASIA-PACIFIC MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 52: ASIA-PACIFIC MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 53: KEY PLAYERS OPERATING IN THE ASIA-PACIFIC MARKET
TABLE 54: REST OF WORLD MARKET, REGIONAL ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 55: REST OF WORLD MARKET, REGIONAL ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 56: KEY PLAYERS OPERATING IN THE REST OF WORLD MARKET
TABLE 57: LIST OF MERGERS & ACQUISITIONS
TABLE 58: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 59: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 60: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: KEY MARKET TRENDS
FIGURE 2: PORTER’S FIVE FORCES ANALYSIS
FIGURE 3: GROWTH PROSPECT MAPPING FOR NORTH AMERICA
FIGURE 4: GROWTH PROSPECT MAPPING FOR EUROPE
FIGURE 5: GROWTH PROSPECT MAPPING FOR ASIA-PACIFIC
FIGURE 6: GROWTH PROSPECT MAPPING FOR REST OF WORLD
FIGURE 7: MARKET MATURITY ANALYSIS
FIGURE 8: MARKET CONCENTRATION ANALYSIS
FIGURE 9: VALUE CHAIN ANALYSIS
FIGURE 10: KEY BUYING CRITERIA
FIGURE 11: SEGMENT GROWTH POTENTIAL, BY PROCESS, IN 2025
FIGURE 12: THERMAL MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: MECHANICAL MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 14: CHEMICAL MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: LASER MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: SEGMENT GROWTH POTENTIAL, BY TYPE, IN 2025
FIGURE 17: SILICON-BASED (C-SI) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: THIN-FILM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: OTHER TYPES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: SEGMENT GROWTH POTENTIAL, BY SHELF LIFE, IN 2025
FIGURE 21: EARLY LOSS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: NORMAL LOSS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: SEGMENT GROWTH POTENTIAL, BY MATERIAL / RECOVERABLE COMPONENTS, IN 2025
FIGURE 24: GLASS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: ALUMINUM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: COPPER MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: PLASTIC MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: SILVER MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 29: PV SILICON MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: OTHER MATERIALS / RECOVERABLE COMPONENTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: NORTH AMERICA SOLAR PANEL RECYCLING MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 32: UNITED STATES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 33: CANADA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 34: EUROPE SOLAR PANEL RECYCLING MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 35: GERMANY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 36: UNITED KINGDOM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 37: FRANCE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 38: ITALY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 39: SPAIN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 40: BELGIUM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 41: POLAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 42: REST OF EUROPE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 43: ASIA-PACIFIC SOLAR PANEL RECYCLING MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 44: CHINA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 45: INDIA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 46: JAPAN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 47: AUSTRALIA & NEW ZEALAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 48: SOUTH KOREA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 49: THAILAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 50: INDONESIA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 51: VIETNAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 52: REST OF ASIA-PACIFIC MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 53: REST OF WORLD SOLAR PANEL RECYCLING MARKET, REGIONAL OUTLOOK, 2025 & 2034 (IN %)
FIGURE 54: LATIN AMERICA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 55: MIDDLE EAST & AFRICA MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
FAQs
Silicon, silver, and aluminum represent the highest-value materials extracted through solar panel recycling processes. Silver commands premium prices due to its use in photovoltaic cell conductors, while high-purity silicon is essential for manufacturing new panels. Additionally, aluminum frames and copper wiring provide significant revenue streams for recycling operations.
Photovoltaic panels typically operate for 25-30 years before reaching the end of their productive shelf life. However, early loss panels may require recycling sooner due to manufacturing defects, installation damage, or extreme weather events. Normal loss panels gradually degrade in efficiency until recycling becomes economically preferable to continued operation.
Chemical and laser-based recycling processes generally achieve the highest material recovery rates, often exceeding 95% for valuable components like silicon and precious metals. However, mechanical thermal techniques remain popular due to lower operational costs and simpler infrastructure requirements. The optimal process depends on panel type, facility capacity, and local environmental regulations governing waste management practices.
RELATED REPORTS
-
TURKEY SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
UNITED STATES SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
JAPAN SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
ASIA-PACIFIC SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
EUROPE SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
NORTH AMERICA SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
GLOBAL SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
UNITED STATES WIND ENERGY MARKET FORECAST 2026-2034
-
CANADA WIND ENERGY MARKET FORECAST 2026-2034
-
GERMANY WIND ENERGY MARKET FORECAST 2026-2034