Global Solar Microinverter Market by Product Type (Single-Phase Microinverters, Three-Phase Microinverters, Standalone Microinverters, Hybrid/Microinverter-Battery Integrated Units, IQ-Series), Market by Connection/System Type (Grid-Tied Microinverters, Off-Grid Microinverters, Hybrid Microinverters Grid-Interactive + Storage Compatible), Market by Power Rating (Below 250 W, 250–400 W, 400–700 W, Above 700 W), Market by Application (Residential Rooftop Solar, Utility-Scale Distributed PV, Off-Grid Systems/Remote Power Supply, Agricultural Solar, Commercial Solar), Market by Distribution Channel (Direct Sales Manufacturers to EPCs or Installers, Online Retail/E-Commerce, Distributors & Wholesalers, OEM Agreements), by Geography
GLOBAL SOLAR MICROINVERTER MARKET OVERVIEW
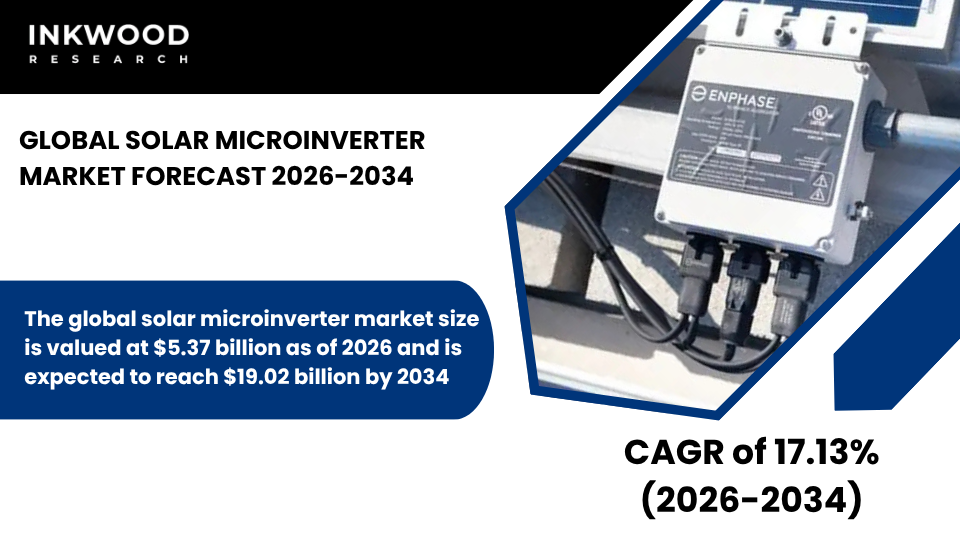
The global solar microinverter market size is valued at $5.37 billion as of 2026 and is expected to reach $19.02 billion by 2034, growing at a CAGR of 17.13% during the forecast period 2026-2034. The base year considered for the study is 2025, and the forecast period is between 2026 and 2034. The market study has also analyzed the crisis impact on the solar microinverter market qualitatively as well as quantitatively.
A solar microinverter is a compact power electronics device that converts direct current from individual photovoltaic panels into alternating current at the module level. Unlike traditional string inverters that connect multiple panels in series, each solar microinverter operates independently on a single panel or a small group of panels.
This architecture provides superior module-level optimization, enabling each panel to perform at its maximum potential regardless of shading, orientation, or degradation affecting neighboring units. The technology has revolutionized residential and commercial solar photovoltaic systems by offering enhanced safety through rapid shutdown capabilities, simplified system design, and real-time monitoring of individual panel performance.
Solar microinverters eliminate single points of failure and support flexible installation configurations, making them particularly valuable in complex rooftop environments. As clean energy adoption accelerates globally, power electronics innovations continue to improve conversion efficiency while reducing costs, positioning solar microinverters as a critical component in distributed solar energy infrastructure.
The solar microinverter market is experiencing robust growth driven by increasing residential solar adoption and evolving safety regulations worldwide. Declining solar module costs have improved the overall economics of microinverter-based systems, making them more competitive with traditional string inverter configurations.
Additionally, growing consumer awareness of energy yield optimization benefits is accelerating the transition from centralized inverter architectures to module-level power electronics solutions. Government incentives supporting clean energy deployment, combined with technological advancements in battery energy storage integration, are creating favorable conditions for market expansion across both developed and emerging solar markets.
To Know More About This Report, Request a Free Sample Copy
GROWTH ENABLERS
Key enablers of the global solar microinverter market growth:
- Rising residential solar adoption is accelerating demand for easy-to-install and scalable inverter solutions
- Increasing focus on system safety and rapid shutdown compliance is favoring microinverter deployment
- Declining module costs are improving the overall economics of microinverter-based systems
- Growing consumer awareness of energy yield optimization is driving upgrade demand from string inverters
- The growing consumer awareness of energy yield optimization represents a fundamental shift in how installers and end-users evaluate solar photovoltaic systems. According to the S. Department of Energy solar research initiatives, module-level power electronics can extract up to 35% more energy compared to string configurations in partially shaded conditions.
- Homeowners increasingly understand that maximizing energy harvest translates directly into faster payback periods and improved lifetime returns on investment. This knowledge is particularly influential in residential markets where roof geometries, nearby trees, or architectural features create shading challenges.
- Furthermore, real-time monitoring capabilities enable users to identify underperforming panels immediately, reducing maintenance costs and downtime. As solar technology education improves through installer training programs and digital marketing, more consumers specifically request solar microinverter solutions during project planning. This demand pull is strengthening market penetration rates across the United States, Europe, and Asia-Pacific regions.
Key growth restraining factors of the global solar panel recycling market:
- Higher upfront system costs continue to limit microinverter penetration in price-sensitive markets
- Complexity in after-sales service can increase maintenance costs for large-scale installations
- Dependence on imported electronic components exposes supply chains to price and availability risks
- Limited suitability for utility-scale projects constrains the addressable market size
- Limited suitability for utility-scale projects represents a structural constraint on total addressable market expansion. While solar microinverters excel in residential rooftop and small commercial applications, utility-scale solar farms spanning hundreds of megawatts typically favor central or string inverters due to installation complexity and cost considerations.
- Large ground-mounted arrays benefit from economies of scale that make per-watt costs significantly lower with centralized power electronics architecture. Additionally, the sheer volume of devices required for gigawatt-scale projects creates logistical challenges in deployment, commissioning, and long-term maintenance management.
- Although some distributed utility projects are beginning to explore microinverter applications for specific use cases, the bulk of utility-scale capacity additions will continue relying on traditional inverter technologies. This limitation channels solar microinverter growth primarily into distributed generation segments, which represent a smaller portion of total global solar capacity additions compared to large-scale solar farms.
KEY MARKET TRENDS
Global Solar Microinverter Industry | Top Trends
- The solar industry is witnessing a rapid increase in panel wattage ratings, with mainstream modules now exceeding 400-500W output compared to 250-300W just a few years ago. In response, leading power electronics companies are developing solar microinverters capable of handling 480W to over 700W AC output to match these high-efficiency panels. Enphase Energy launched its IQ8 series microinverters in 2024, featuring models rated up to 384W peak AC output designed specifically for 500W+ DC solar modules. These advancements ensure that solar microinverter technology remains compatible with evolving photovoltaic systems while maintaining conversion efficiency above 96%. The trend toward higher power ratings also improves system economics by reducing the number of devices needed per installation, lowering both hardware and labor costs.
- Modern solar microinverter systems now include sophisticated cloud-based monitoring platforms that provide granular, panel-level performance data accessible through mobile applications and web portals. These software solutions enable remote diagnostics, automated alerts for underperformance or failures, and detailed energy production analytics. Real-time visibility into individual panel performance helps installers identify issues quickly, reduces truck rolls for service calls, and provides end-users with transparency into their renewable energy production. Furthermore, advanced analytics leverage machine learning algorithms to predict maintenance needs and optimize energy storage dispatch in solar-plus-battery configurations, adding substantial value beyond simple power conversion.
- Equipment manufacturers are increasingly forming exclusive or preferred partnerships with solar installation companies to secure distribution channels and drive product adoption. In November 2025, Enphase Energy announced a partnership with Green Mountain Power in Vermont to deploy IQ Battery systems through a utility-backed home battery lease program. Similarly, in February 2024, Sparq Systems signed a manufacturing and supply agreement with Jio Things Limited to develop and distribute microinverters across India and global markets. These collaborations provide manufacturers with reliable demand pipelines while offering installers preferential pricing, technical support, and co-marketing opportunities. Such partnerships are particularly valuable in residential solar markets where installer recommendations heavily influence customer equipment choices, creating brand loyalty and market share advantages.
- AC module technology, which integrates solar microinverters directly into photovoltaic panel frames during manufacturing, is gaining traction as a plug-and-play solar solution. This factory integration simplifies field installation by eliminating separate microinverter mounting and wiring steps, reducing labor costs and installation time. AC modules also streamline permitting and inspection processes since they arrive as pre-certified, code-compliant units. Several panel manufacturers are partnering with power electronics companies to offer these integrated products, particularly targeting the residential market, where ease of installation drives adoption. The U.S. National Electrical Code’s rapid shutdown requirements have further accelerated AC module interest, as the integrated design inherently meets safety standards without additional equipment.
MARKET SEGMENTATION
Market Segmentation – Product Type, Connection/System Type, Power Rating, Application, and Distribution Channel –
Market by Product Type:
- Single-Phase Microinverters
- Single-phase microinverters represent the most established segment within the solar microinverter market, designed specifically for residential and small commercial applications using standard 120V or 240V electrical service. These devices convert DC power from individual solar panels into single-phase alternating current that integrates seamlessly with typical household electrical systems.
- Key features include compact form factors, weather-resistant enclosures rated to IP67 standards, and integrated wireless communication for monitoring. Single-phase designs appeal to customers through their simplified installation process, lower upfront costs compared to three-phase alternatives, and proven reliability in millions of deployed systems worldwide.
- The segment benefits from continuous design improvements that have pushed peak efficiency ratings above 97% while reducing component counts and manufacturing costs. Growing demand stems primarily from new residential construction codes requiring solar-ready infrastructure, existing homeowner retrofits seeking energy independence, and government incentive programs like the U.S. Investment Tax Credit that make distributed solar financially attractive.
- Three-Phase Microinverters
- Standalone Microinverters
- Hybrid/Microinverter-Battery Integrated Units
- IQ-Series
Market by Connection/System Type:
- Grid-Tied Microinverters
- Off-Grid Microinverters
- Hybrid Microinverters (Grid-Interactive + Storage Compatible)
Market by Power Rating:
- Below 250 W
- 250–400 W
- 400–700 W
- Above 700 W
Market by Application:
- Residential Rooftop Solar
- Utility-Scale Distributed PV
- Off-Grid Systems/Remote Power Supply
- Agricultural Solar
- Commercial Solar
Market by Distribution Channel:
- Direct Sales (Manufacturers to EPCs or Installers)
- Online Retail/E-Commerce
- Distributors & Wholesalers
- OEM Agreements
Geographical Study based on Three Major Regions:
- Europe: The United Kingdom, Germany, France, Italy, Spain, Poland, Belgium, and Rest of Europe
- Asia-Pacific: China, India, Japan, Australia & New Zealand, South Korea, Thailand, Indonesia, Vietnam, and Rest of Asia-Pacific
- The solar microinverter market in China is experiencing substantial growth supported by the government’s strong commitment to renewable energy and significant investments in solar infrastructure. The country’s 14th Five-Year Plan emphasizes distributed photovoltaic systems, creating favorable policy conditions for solar microinverter adoption in residential, commercial, and industrial applications.
- As the world’s leading solar panel manufacturer, China benefits from vertically integrated supply chains that reduce power electronics costs while maintaining quality standards. Companies like Hoymiles and APsystems (Altenergy Power System) have emerged as major global competitors, leveraging domestic manufacturing advantages to offer competitively priced products.
- Additionally, China’s focus on smart grid integration and energy storage systems is driving demand for advanced microinverter solutions with bidirectional power flow capabilities. However, the market faces challenges from grid curtailment in certain provinces and intense price competition among domestic manufacturers.
- Looking forward, urbanization trends, rising electricity consumption, and government subsidies for building-integrated photovoltaics position China as a critical growth market through 2034, particularly as low-carbon-intensive technologies gain priority in national development strategies.
- Rest of World: Latin America, the Middle East & Africa
Our market research reports offer an in-depth analysis of individual country-level market size and growth statistics. We cover the segmentation analysis, key growth factors, and macro-economic trends within the solar microinverter market, providing detailed insights into –
MAJOR PLAYERS
The major players in the global solar microinverter market are:
- Enphase Energy Inc
- Hoymiles Power Electronics Inc
- APsystems (Altenergy Power System Inc)
- SMA Solar Technology AG
- Sungrow Power Supply Co Ltd
Key strategies adopted by some of these companies:
- Enphase Energy launched the fourth-generation IQ Battery 10C with domestic U.S. manufacturing in August 2025. The company introduced its next-generation battery energy storage system featuring 10 kWh usable capacity and 7.08 kW continuous power output, manufactured in U.S. facilities to qualify for domestic content bonus credits. This strategic move addresses growing demand for solar-plus-storage solutions while reducing dependence on imported components and meeting Buy America requirements for utility and commercial projects.
- Enphase Energy formed a partnership with Green Mountain Power for a battery lease program in November 2025. The collaboration enables Vermont residents to access IQ Battery systems through a 10-year lease at $55 monthly or a $5,500 upfront payment, supporting GMP’s 75 MW virtual power plant initiative. This partnership strategy demonstrates how manufacturers are working directly with utilities to create new customer acquisition channels while advancing grid modernization and clean energy goals.
- Hoymiles officially entered the Indian market with a comprehensive product portfolio launch in September 2025. The company hosted an exclusive product launch ceremony in New Delhi, unveiling battery energy storage systems, microinverters, string inverters, and hybrid solutions targeting India’s rapidly expanding solar ecosystem. This market expansion strategy positions Hoymiles to capitalize on India’s government initiatives, including PM Surya Ghar and PM-KUSUM programs that are driving residential and agricultural solar adoption.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Product Type, Connection / System Type, Power Rating, Application, Distribution Channel |
| Geographies Analyzed | Europe, Asia-Pacific, Rest of World |
| Companies Analyzed | Enphase Energy Inc, SolarEdge Technologies Inc, Hoymiles Power Electronics Inc, SMA Solar Technology AG, APsystems (Altenergy Power System Inc), Darfon Electronics Corp, Sungrow Power Supply Co Ltd, Chilicon Power LLC, Sparq Systems Inc, Leading Edge Power, ReneSola Ltd, ABB Ltd, Delta Electronics Inc, GoodWe, Fronius International GmbH |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY & KEY INSIGHTS
- MARKET SIZE, SHARE & ESTIMATES
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- MICROINVERTERS ARE GAINING SHARE OVER STRING INVERTERS DUE TO SUPERIOR MODULE LEVEL OPTIMIZATION AND SAFETY PERFORMANCE
- RESIDENTIAL ROOFTOP INSTALLATIONS ACCOUNT FOR THE LARGEST DEMAND SHARE, DRIVEN BY DESIGN FLEXIBILITY AND SHADE TOLERANCE
- TECHNOLOGICAL DIFFERENTIATION IS CENTERED AROUND HIGHER POWER RATINGS AND INTEGRATED MONITORING CAPABILITIES
MARKET DYNAMICS
- KEY DRIVERS
- RISING RESIDENTIAL SOLAR ADOPTION IS ACCELERATING DEMAND FOR EASY TO INSTALL AND SCALABLE INVERTER SOLUTIONS
- INCREASING FOCUS ON SYSTEM SAFETY AND RAPID SHUTDOWN COMPLIANCE IS FAVORING MICROINVERTER DEPLOYMENT
- DECLINING MODULE COSTS ARE IMPROVING THE OVERALL ECONOMICS OF MICROINVERTER-BASED SYSTEMS
- GROWING CONSUMER AWARENESS OF ENERGY YIELD OPTIMIZATION IS DRIVING UPGRADE DEMAND FROM STRING INVERTERS
- KEY RESTRAINTS
- HIGHER UPFRONT SYSTEM COSTS CONTINUE TO LIMIT MICROINVERTER PENETRATION IN PRICE-SENSITIVE MARKETS
- COMPLEXITY IN AFTER-SALES SERVICE CAN INCREASE MAINTENANCE COSTS FOR LARGE-SCALE INSTALLATIONS
- DEPENDENCE ON IMPORTED ELECTRONIC COMPONENTS EXPOSES SUPPLY CHAINS TO PRICE AND AVAILABILITY RISKS
- LIMITED SUITABILITY FOR UTILITY SCALE PROJECTS CONSTRAINS THE ADDRESSABLE MARKET SIZE
- KEY DRIVERS
STRATEGIC MARKET ANALYTICS
- KEY MARKET TRENDS
- MANUFACTURERS ARE INTRODUCING HIGH-POWER MICROINVERTERS TO SUPPORT NEXT GENERATION SOLAR MODULES
- INTEGRATION OF ADVANCED MONITORING SOFTWARE IS BECOMING A STANDARD PRODUCT FEATURE
- STRATEGIC PARTNERSHIPS WITH INSTALLERS ARE EMERGING AS A KEY GO-TO MARKET STRATEGY
- INCREASING ADOPTION OF AC MODULES IS STRENGTHENING THE MICROINVERTER ECOSYSTEM
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR EUROPE
- GROWTH PROSPECT MAPPING FOR ASIA-PACIFIC
- GROWTH PROSPECT MAPPING FOR REST OF WORLD
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SOURCING
- POWER ELECTRONICS DESIGN
- COMPONENT MANUFACTURING
- INVERTER ASSEMBLY
- QUALITY TESTING
- DISTRIBUTION CHANNELS
- INSTALLATION SERVICES
- AFTER SALES SUPPORT
- KEY BUYING CRITERIA
- CONVERSION EFFICIENCY
- SYSTEM RELIABILITY
- WARRANTY COVERAGE
- MONITORING FEATURES
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
SOLAR MICROINVERTER MARKET BY PRODUCT TYPE
- SINGLE-PHASE MICROINVERTERS
- THREE-PHASE MICROINVERTERS
- STANDALONE MICROINVERTERS
- HYBRID / MICROINVERTER-BATTERY INTEGRATED UNITS
- IQ-SERIES
SOLAR MICROINVERTER MARKET BY CONNECTION / SYSTEM TYPE
- GRID-TIED MICROINVERTERS
- OFF-GRID MICROINVERTERS
- HYBRID MICROINVERTERS (GRID-INTERACTIVE + STORAGE COMPATIBLE)
SOLAR MICROINVERTER MARKET BY POWER RATING
- BELOW 250 W
- 250–400 W
- 400–700 W
- ABOVE 700 W
SOLAR MICROINVERTER MARKET BY APPLICATION
- RESIDENTIAL ROOFTOP SOLAR
- UTILITY-SCALE DISTRIBUTED PV
- OFF-GRID SYSTEMS / REMOTE POWER SUPPLY
- AGRICULTURAL SOLAR
- COMMERCIAL SOLAR
- SMALL-SIZE
- MID-SIZE
SOLAR MICROINVERTER MARKET BY DISTRIBUTION CHANNEL
- DIRECT SALES (MANUFACTURERS TO EPCS OR INSTALLERS)
- ONLINE RETAIL / E-COMMERCE
- DISTRIBUTORS & WHOLESALERS
- OEM AGREEMENTS
GEOGRAPHICAL ANALYSIS
- EUROPE
- MARKET SIZE & ESTIMATES
- EUROPE MARKET DRIVERS
- EUROPE MARKET CHALLENGES
- KEY PLAYERS IN EUROPE SOLAR MICROINVERTER MARKET
- COUNTRY ANALYSIS
- GERMANY
- GERMANY MARKET SIZE & OPPORTUNITIES
- UNITED KINGDOM
- UNITED KINGDOM MARKET SIZE & OPPORTUNITIES
- FRANCE
- FRANCE MARKET SIZE & OPPORTUNITIES
- ITALY
- ITALY MARKET SIZE & OPPORTUNITIES
- SPAIN
- SPAIN MARKET SIZE & OPPORTUNITIES
- BELGIUM
- BELGIUM MARKET SIZE & OPPORTUNITIES
- POLAND
- POLAND MARKET SIZE & OPPORTUNITIES
- REST OF EUROPE
- REST OF EUROPE MARKET SIZE & OPPORTUNITIES
- GERMANY
- ASIA-PACIFIC
- MARKET SIZE & ESTIMATES
- ASIA-PACIFIC MARKET DRIVERS
- ASIA-PACIFIC MARKET CHALLENGES
- KEY PLAYERS IN ASIA-PACIFIC SOLAR MICROINVERTER MARKET
- COUNTRY ANALYSIS
- CHINA
- CHINA MARKET SIZE & OPPORTUNITIES
- INDIA
- INDIA MARKET SIZE & OPPORTUNITIES
- JAPAN
- JAPAN MARKET SIZE & OPPORTUNITIES
- AUSTRALIA & NEW ZEALAND
- AUSTRALIA & NEW ZEALAND MARKET SIZE & OPPORTUNITIES
- SOUTH KOREA
- SOUTH KOREA MARKET SIZE & OPPORTUNITIES
- THAILAND
- THAILAND MARKET SIZE & OPPORTUNITIES
- INDONESIA
- INDONESIA MARKET SIZE & OPPORTUNITIES
- VIETNAM
- VIETNAM MARKET SIZE & OPPORTUNITIES
- REST OF ASIA-PACIFIC
- REST OF ASIA-PACIFIC MARKET SIZE & OPPORTUNITIES
- CHINA
- REST OF WORLD
- MARKET SIZE & ESTIMATES
- REST OF WORLD MARKET DRIVERS
- REST OF WORLD MARKET CHALLENGES
- KEY PLAYERS IN REST OF WORLD SOLAR MICROINVERTER MARKET
- REGIONAL ANALYSIS
- LATIN AMERICA
- LATIN AMERICA MARKET SIZE & OPPORTUNITIES
- MIDDLE EAST & AFRICA
- MIDDLE EAST & AFRICA MARKET SIZE & OPPORTUNITIES
- LATIN AMERICA
- EUROPE
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPETITOR POSITIONING & DIFFERENTIATION MAP
- COMPANY PROFILES
- ENPHASE ENERGY INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SOLAREDGE TECHNOLOGIES INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- HOYMILES POWER ELECTRONICS INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SMA SOLAR TECHNOLOGY AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- APSISTEMS (ALTENERGY POWER SYSTEM INC)
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- DARFON ELECTRONICS CORP
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SUNGROW POWER SUPPLY CO LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- CHILICON POWER LLC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SPARQ SYSTEMS INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- LEADING EDGE POWER
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- RENESOLA LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ABB LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- DELTA ELECTRONICS INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GOODWE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- FRONIUS INTERNATIONAL GMBH
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ENPHASE ENERGY INC
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – SOLAR MICROINVERTER
TABLE 2: SOLAR MICROINVERTER MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY PRODUCT TYPE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY PRODUCT TYPE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: SINGLE-PHASE MICROINVERTERS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: SINGLE-PHASE MICROINVERTERS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: THREE-PHASE MICROINVERTERS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: THREE-PHASE MICROINVERTERS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: STANDALONE MICROINVERTERS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: STANDALONE MICROINVERTERS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: HYBRID / MICROINVERTER-BATTERY INTEGRATED UNITS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 12: HYBRID / MICROINVERTER-BATTERY INTEGRATED UNITS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 13: IQ-SERIES MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 14: IQ-SERIES MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 15: MARKET BY CONNECTION / SYSTEM TYPE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 16: MARKET BY CONNECTION / SYSTEM TYPE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 17: GRID-TIED MICROINVERTERS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 18: GRID-TIED MICROINVERTERS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 19: OFF-GRID MICROINVERTERS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 20: OFF-GRID MICROINVERTERS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 21: HYBRID MICROINVERTERS (GRID-INTERACTIVE + STORAGE COMPATIBLE) MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 22: HYBRID MICROINVERTERS (GRID-INTERACTIVE + STORAGE COMPATIBLE) MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 23: MARKET BY POWER RATING, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 24: MARKET BY POWER RATING, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 25: BELOW 250 W MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 26: BELOW 250 W MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 27: 250–400 W MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 28: 250–400 W MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 29: 400–700 W MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 30: 400–700 W MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 31: ABOVE 700 W MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 32: ABOVE 700 W MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 33: MARKET BY APPLICATION, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 34: MARKET BY APPLICATION, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 35: RESIDENTIAL ROOFTOP SOLAR MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 36: RESIDENTIAL ROOFTOP SOLAR MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 37: UTILITY-SCALE DISTRIBUTED PV MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 38: UTILITY-SCALE DISTRIBUTED PV MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 39: OFF-GRID SYSTEMS / REMOTE POWER SUPPLY MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 40: OFF-GRID SYSTEMS / REMOTE POWER SUPPLY MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 41: AGRICULTURAL SOLAR MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 42: AGRICULTURAL SOLAR MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 43: COMMERCIAL SOLAR MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 44: COMMERCIAL SOLAR MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 45: MARKET BY COMMERCIAL SOLAR, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 46: MARKET BY COMMERCIAL SOLAR, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 47: SMALL-SIZE COMMERCIAL SOLAR MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 48: SMALL-SIZE COMMERCIAL SOLAR MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 49: MID-SIZE COMMERCIAL SOLAR MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 50: MID-SIZE COMMERCIAL SOLAR MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 51: MARKET BY DISTRIBUTION CHANNEL, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 52: MARKET BY DISTRIBUTION CHANNEL, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 53: DIRECT SALES MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 54: DIRECT SALES MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 55: ONLINE RETAIL / E-COMMERCE MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 56: ONLINE RETAIL / E-COMMERCE MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 57: DISTRIBUTORS & WHOLESALERS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 58: DISTRIBUTORS & WHOLESALERS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 59: OEM AGREEMENTS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 60: OEM AGREEMENTS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 61: MARKET BY GEOGRAPHICAL ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 62: MARKET BY GEOGRAPHICAL ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 63: EUROPE MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 64: EUROPE MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 65: KEY PLAYERS OPERATING IN THE EUROPEAN MARKET
TABLE 66: ASIA-PACIFIC MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 67: ASIA-PACIFIC MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 68: KEY PLAYERS OPERATING IN THE ASIA-PACIFIC MARKET
TABLE 69: REST OF WORLD MARKET, REGIONAL ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 70: REST OF WORLD MARKET, REGIONAL ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 71: KEY PLAYERS OPERATING IN THE REST OF WORLD MARKET
TABLE 72: LIST OF MERGERS & ACQUISITIONS
TABLE 73: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 74: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 75: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR EUROPE
FIGURE 6: GROWTH PROSPECT MAPPING FOR ASIA-PACIFIC
FIGURE 7: GROWTH PROSPECT MAPPING FOR REST OF WORLD
FIGURE 8: MARKET MATURITY ANALYSIS
FIGURE 9: MARKET CONCENTRATION ANALYSIS
FIGURE 10: VALUE CHAIN ANALYSIS
FIGURE 11: KEY BUYING CRITERIA
FIGURE 12: SEGMENT GROWTH POTENTIAL, BY PRODUCT TYPE, IN 2025
FIGURE 13: SINGLE-PHASE MICROINVERTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 14: THREE-PHASE MICROINVERTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: STANDALONE MICROINVERTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: HYBRID / MICROINVERTER-BATTERY INTEGRATED UNITS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: IQ-SERIES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: SEGMENT GROWTH POTENTIAL, BY CONNECTION / SYSTEM TYPE, IN 2025
FIGURE 19: GRID-TIED MICROINVERTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: OFF-GRID MICROINVERTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: HYBRID MICROINVERTERS (GRID-INTERACTIVE + STORAGE COMPATIBLE) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: SEGMENT GROWTH POTENTIAL, BY POWER RATING, IN 2025
FIGURE 23: BELOW 250 W MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: 250–400 W MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: 400–700 W MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: ABOVE 700 W MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: SEGMENT GROWTH POTENTIAL, BY APPLICATION, IN 2025
FIGURE 28: RESIDENTIAL ROOFTOP SOLAR MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 29: UTILITY-SCALE DISTRIBUTED PV MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: OFF-GRID SYSTEMS / REMOTE POWER SUPPLY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: AGRICULTURAL SOLAR MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 32: COMMERCIAL SOLAR MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 33: SEGMENT GROWTH POTENTIAL, BY COMMERCIAL SOLAR, IN 2025
FIGURE 34: SMALL-SIZE COMMERCIAL SOLAR MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 35: MID-SIZE COMMERCIAL SOLAR MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 36: SEGMENT GROWTH POTENTIAL, BY DISTRIBUTION CHANNEL, IN 2025
FIGURE 37: DIRECT SALES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 38: ONLINE RETAIL / E-COMMERCE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 39: DISTRIBUTORS & WHOLESALERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 40: OEM AGREEMENTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 41: EUROPE SOLAR MICROINVERTER MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 42: GERMANY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 43: UNITED KINGDOM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 44: FRANCE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 45: ITALY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 46: SPAIN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 47: BELGIUM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 48: POLAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 49: REST OF EUROPE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 50: ASIA-PACIFIC SOLAR MICROINVERTER MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 51: CHINA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 52: INDIA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 53: JAPAN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 54: AUSTRALIA & NEW ZEALAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 55: SOUTH KOREA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 56: THAILAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 57: INDONESIA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 58: VIETNAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 59: REST OF ASIA-PACIFIC MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 60: REST OF WORLD SOLAR MICROINVERTER MARKET, REGIONAL OUTLOOK, 2025 & 2034 (IN %)
FIGURE 61: LATIN AMERICA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 62: MIDDLE EAST & AFRICA MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
FAQs
A solar microinverter is a compact power electronics device that converts DC electricity to AC at the individual panel level, whereas string inverters connect multiple panels in series. Solar microinverters offer superior performance in shaded conditions, enhanced safety through module-level shutdown, and simplified system expansion, making them ideal for residential rooftop solar installations.
The global solar microinverter market is driven by increasing residential solar adoption, declining module costs, improving system economics, and growing demand for energy yield optimization. Additionally, safety regulations requiring rapid shutdown compliance and advances in battery energy storage integration are accelerating microinverter deployment across renewable energy projects worldwide.
North America leads in solar microinverter penetration due to strong installer networks and safety code requirements, while Asia-Pacific, particularly China and India, is experiencing the fastest growth driven by government renewable energy mandates. Europe maintains steady adoption through feed-in tariffs and energy independence initiatives, making these three regions critical markets for power electronics manufacturers through 2034.
RELATED REPORTS
-
TURKEY SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
UNITED STATES SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
JAPAN SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
ASIA-PACIFIC SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
EUROPE SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
NORTH AMERICA SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
GLOBAL SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
UNITED STATES WIND ENERGY MARKET FORECAST 2026-2034
-
CANADA WIND ENERGY MARKET FORECAST 2026-2034
-
GERMANY WIND ENERGY MARKET FORECAST 2026-2034