
EUROPE UAV BATTERY MARKET FORECAST 2025-2032
SCOPE OF THE REPORT
Europe UAV Battery Market by Technology (Lithium-Based, Nickel-Based, Fuel Cell, Sodium-Ion) Market by Component (Cells, Enclosures, Connectors) Market by Point of Sale (OEM, Aftermarket) Market by Platform (Consumer, Commercial, Government & Law Enforcement, Military)
REPORTS » ENERGY, POWER & UTILITIES » ENERGY STORAGE » EUROPE UAV BATTERY MARKET FORECAST 2025-2032
EUROPE UAV BATTERY MARKET OVERVIEW
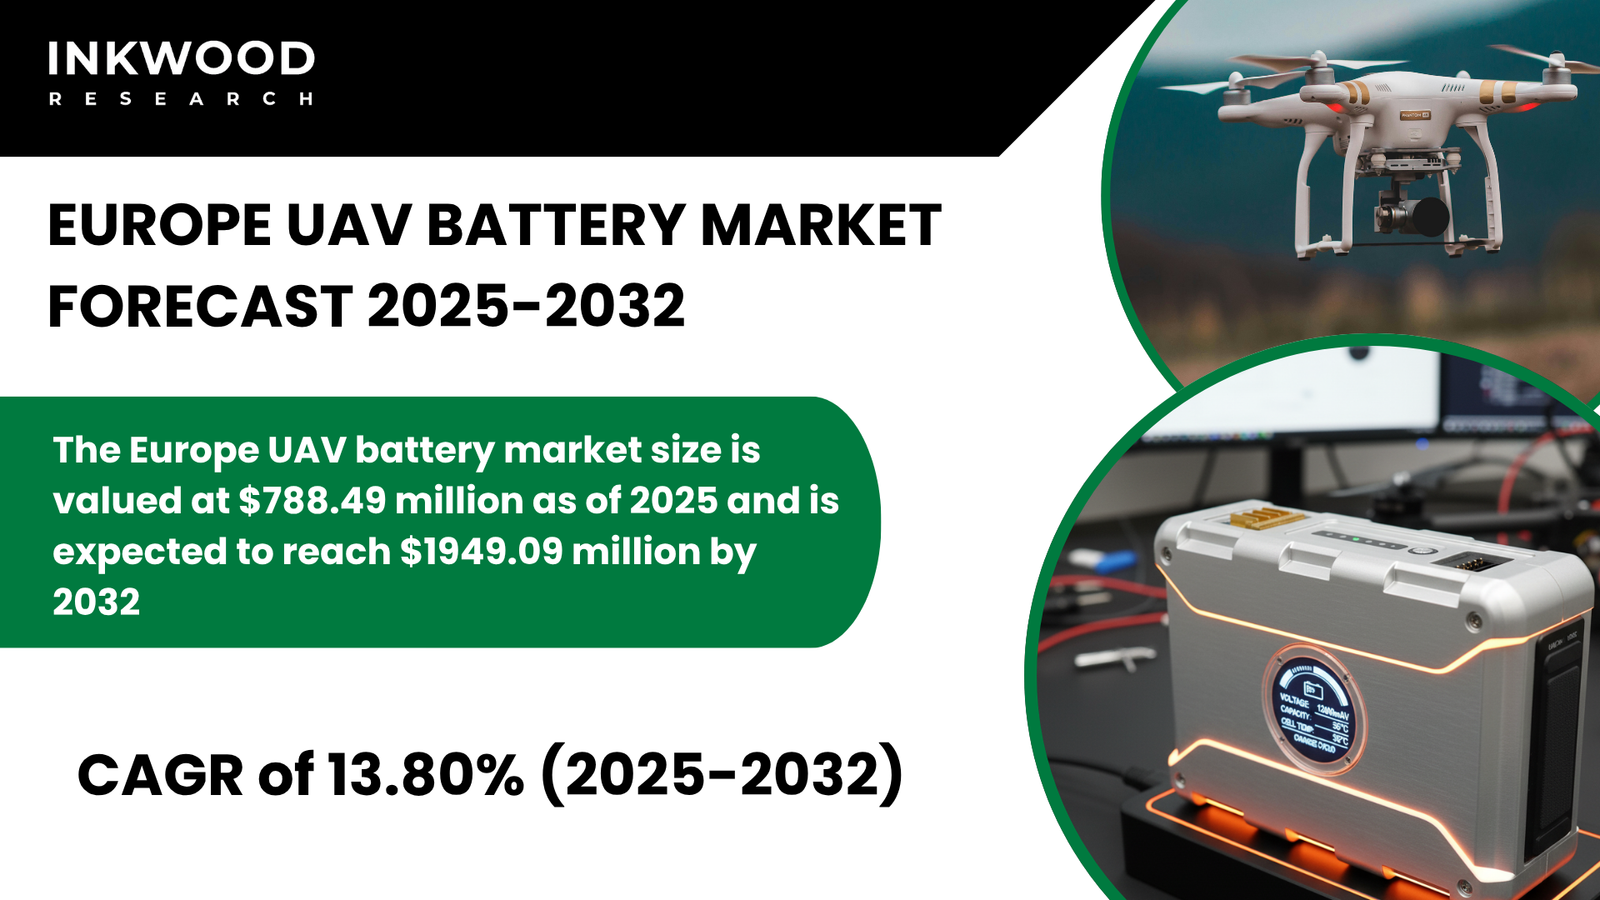
The Europe UAV battery market size is valued at $788.49 million as of 2025 and is expected to reach $1949.09 million by 2032, progressing with a CAGR of 13.80% during the forecast years, 2025-2032.
The Europe UAV battery market demonstrates strong growth momentum fueled by coordinated defense initiatives across member states and expanding commercial drone applications throughout the region’s diverse industries. European Union policies promoting autonomous aerial mobility and smart city infrastructure accelerate the adoption of battery-powered drones for urban logistics and public services. Meanwhile, defense collaborations among NATO allies drive joint procurement programs for unmanned surveillance systems requiring standardized power solutions.
Regulatory harmonization efforts by the European Union Aviation Safety Agency (EASA) establish consistent operational frameworks enabling cross-border drone operations, thereby expanding market opportunities for battery manufacturers. Additionally, Europe’s commitment to sustainable transportation and renewable energy creates favorable conditions for developing eco-friendly battery technologies aligned with environmental objectives. The region’s robust aerospace manufacturing ecosystem supports innovation through research partnerships connecting universities, battery developers, and UAV producers.
Furthermore, government funding initiatives targeting advanced materials research accelerate the development of next-generation battery chemistries promising higher energy density and improved safety characteristics. Commercial sectors, including agriculture, energy infrastructure, and logistics, increasingly integrate drone technology into operational workflows, generating sustained demand for reliable power systems.
To Know More About This Report, Request a Free Sample Copy
The Europe UAV battery market growth assessment includes the analysis of the United Kingdom, Germany, France, Italy, Spain, Belgium, Poland, and Rest of Europe.
The United Kingdom emerges as a significant market for UAV battery systems, driven by defense modernization programs and pioneering commercial drone applications across various sectors. According to the UK Ministry of Defence, military investments prioritize unmanned intelligence, surveillance, and reconnaissance capabilities for both domestic security and international operations. Defense contractors based in the UK develop advanced battery solutions specifically engineered for long-endurance maritime patrol drones monitoring coastal waters and offshore installations.
Meanwhile, commercial operators leverage favorable regulations established by the UK Civil Aviation Authority to deploy drones for infrastructure inspection, emergency response, and delivery services. Energy companies utilize battery-powered UAVs for offshore wind farm inspections and oil platform surveys, requiring power systems capable of withstanding harsh marine environments. Agricultural enterprises across rural regions adopt precision farming techniques enabled by drones monitoring livestock and crop conditions.
Additionally, the UK’s pharmaceutical and healthcare sectors pioneer medical drone delivery programs connecting urban hospitals with rural clinics, demanding rapid-charging batteries supporting time-sensitive missions. Technology hubs in London and Cambridge foster innovation through collaborative research initiatives exploring solid-state batteries and hybrid power systems. The country’s established aerospace supply chains facilitate domestic production while maintaining quality standards required for both military and commercial aviation applications.
Germany commands substantial influence within Europe’s UAV battery market through its manufacturing prowess and technological leadership in battery chemistry research. The German Federal Ministry of Defence allocates significant resources toward unmanned systems for reconnaissance and tactical support operations, creating robust demand for high-performance power solutions. German automotive manufacturers leveraging battery expertise from electric vehicle programs increasingly diversify into UAV power systems, applying advanced thermal management technologies to aerial applications.
Industrial sectors throughout Germany’s manufacturing heartland deploy inspection drones for quality control, warehouse management, and supply chain optimization, requiring reliable batteries supporting multiple daily operational cycles. According to reports, the country’s commitment to Industry 4.0 initiatives accelerates the integration of autonomous systems into manufacturing environments. Agricultural cooperatives in Bavaria and other rural regions utilize precision farming drones for crop health monitoring and targeted pesticide application.
Furthermore, Germany’s renewable energy sector employs UAVs for wind turbine inspections and solar farm maintenance across expansive installations. Research institutions collaborate with battery manufacturers to develop next-generation chemistries, including lithium-sulfur and solid-state architectures, promising superior performance characteristics. Vendors targeting the German market should emphasize manufacturing quality, technical certifications, and alignment with environmental sustainability standards valued by enterprises and government agencies throughout the country.
The Europe UAV battery market is segmented into technology, component, point of sale, and platform. The technology segment is further categorized into lithium-based, nickel-based, fuel cell, and sodium-ion.
The lithium-based technology segment maintains dominance across Europe’s UAV battery market due to proven reliability and mature manufacturing infrastructure supporting diverse applications. Lithium-ion and lithium-polymer chemistries provide optimal energy density for commercial drones operating in delivery services, agricultural monitoring, and infrastructure inspection throughout European nations. These battery technologies deliver consistent performance across the region’s varied climatic conditions, from Mediterranean warmth to Nordic cold.
European manufacturers prioritize lithium-based systems meeting stringent safety regulations established by aviation authorities while satisfying environmental standards governing battery production and disposal. Additionally, declining production costs through manufacturing scale economies make lithium batteries economically viable for price-sensitive commercial applications. Defense procurement programs across Europe favor lithium-based power systems for tactical UAVs requiring lightweight configurations without compromising mission duration.
Moreover, Europe’s established supply chains for lithium battery components enable rapid scaling of production capacity, responding to growing demand across military and commercial segments. Investment opportunities emerge for vendors offering customized lithium battery solutions optimized for specific European applications such as cold-weather operations in Scandinavia or extended-endurance missions supporting border security initiatives.
Some of the top players operating in the Europe UAV battery market include Intelligent Energy, HES Energy Systems, Epsilor, Tadiran Batteries, etc.
Intelligent Energy holds a strategic position in the Europe UAV battery market through its pioneering fuel cell technology offering extended flight endurance for commercial and defense applications. The UK-based company specializes in hydrogen fuel cell systems that dramatically increase UAV operational duration compared to conventional battery-only configurations. Intelligent Energy’s modular fuel cell designs integrate seamlessly with lithium batteries, creating hybrid power architectures optimized for long-range surveillance and delivery missions.
Their engineering expertise enables customization of power modules matching specific voltage and current requirements of diverse UAV platforms. Furthermore, the company maintains strong partnerships with European defense contractors supplying fuel cell solutions for next-generation reconnaissance programs requiring multi-hour loiter capabilities. Intelligent Energy’s manufacturing facilities adhere to aerospace quality standards, ensuring product reliability demanded by military specifications.
Additionally, their technical support services assist commercial operators in transitioning from battery-only systems to hybrid configurations, providing training on hydrogen handling and fuel cell maintenance. The company’s strategic focus on sustainable aviation aligns with Europe’s environmental objectives, positioning their technology as a preferred solution for operators prioritizing reduced carbon emissions alongside enhanced operational performance.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2025-2032 |
| Base Year | 2024 |
| Market Historical Years | 2018-2023 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Technology, Component, Point of Sale, and Platform |
| Countries Analyzed | The United Kingdom, Germany, France, Italy, Spain, Belgium, Poland, and Rest of Europe. |
| Companies Analyzed | Tadiran Batteries, Eagle-Picher Technologies, Epsilor, HES Energy Systems, Intelligent Energy, Inventus Power, Plug Power, RRC Power Solutions, Shenzhen Grepow Battery, Sion Power |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- THE UAV BATTERY MARKET IS EXPERIENCING SIGNIFICANT GROWTH DUE TO RISING DEMAND FOR LONG-ENDURANCE DRONES ACROSS COMMERCIAL AND DEFENSE APPLICATIONS
- LITHIUM-POLYMER AND LITHIUM-ION BATTERIES DOMINATE THE MARKET OWING TO THEIR HIGH ENERGY DENSITY AND LIGHTWEIGHT CHARACTERISTICS
- INCREASING INVESTMENTS IN UAV TECHNOLOGY BY DEFENSE AGENCIES ARE DRIVING THE DEMAND FOR HIGH-PERFORMANCE AND FAST-CHARGING BATTERIES
MARKET DYNAMICS
- KEY DRIVERS
- INCREASING COMMERCIAL APPLICATIONS, SUCH AS DELIVERY SERVICES, AGRICULTURE, AND SURVEILLANCE, ARE BOOSTING UAV BATTERY DEMAND
- TECHNOLOGICAL ADVANCEMENTS IN BATTERY CHEMISTRY ARE IMPROVING ENERGY DENSITY AND CYCLE LIFE OF UAV BATTERIES
- GOVERNMENT SUPPORT AND REGULATORY APPROVALS FOR UAV OPERATIONS IN CIVIL AIRSPACE ARE EXPANDING MARKET OPPORTUNITIES
- RISING DEFENSE EXPENDITURES AND DEMAND FOR UNMANNED SYSTEMS FOR BORDER SECURITY AND RECONNAISSANCE ARE FUELING MARKET GROWTH
- KEY RESTRAINTS
- LIMITED FLIGHT TIME AND ENERGY STORAGE CAPACITY OF CURRENT BATTERY TECHNOLOGIES CONSTRAIN LONG-ENDURANCE UAV OPERATIONS
- HIGH COST OF ADVANCED BATTERY MATERIALS AND PRODUCTION LIMITS MASS ADOPTION IN COST-SENSITIVE APPLICATIONS
- THERMAL MANAGEMENT AND SAFETY ISSUES ASSOCIATED WITH HIGH-ENERGY BATTERIES POSE CHALLENGES FOR MANUFACTURERS
- SLOW DEVELOPMENT OF BATTERY RECYCLING INFRASTRUCTURE INCREASES ENVIRONMENTAL AND SUPPLY CHAIN RISKS
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- INCREASING ADOPTION OF SOLID-STATE BATTERIES IS EXPECTED TO ENHANCE SAFETY AND ENERGY EFFICIENCY OF UAVS
- RAPID R&D FOCUS ON HYBRID ENERGY SYSTEMS COMBINING FUEL CELLS AND BATTERIES TO EXTEND UAV FLIGHT TIME
- GROWING PARTNERSHIPS BETWEEN UAV MANUFACTURERS AND BATTERY SUPPLIERS TO DEVELOP CUSTOMIZED POWER SOLUTIONS
- SHIFT TOWARD LIGHTWEIGHT AND HIGH-PERFORMANCE MATERIALS LIKE GRAPHENE AND LITHIUM-SULFUR FOR NEXT-GENERATION UAV BATTERIES
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR EUROPE
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SUPPLIERS
- BATTERY CELL MANUFACTURERS
- MODULE ASSEMBLERS
- UAV OEMS
- SYSTEM INTEGRATORS
- DISTRIBUTORS
- END USERS
- KEY BUYING CRITERIA
- ENERGY DENSITY
- WEIGHT EFFICIENCY
- CYCLE LIFE
- CHARGING SPEED
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
UAV BATTERY MARKET BY TECHNOLOGY
- LITHIUM-BASED
- LITHIUM-ION
- LITHIUM-POLYMER
- LITHIUM-METAL
- LITHIUM-SULFUR
- NICKEL-BASED
- FUEL CELL
- LITHIUM-BASED
UAV BATTERY MARKET BY COMPONENT
- CELLS
- ENCLOSURES
- CONNECTORS
UAV BATTERY MARKET BY POINT OF SALE
- OEM
- AFTERMARKET
UAV BATTERY MARKET BY PLATFORM
- CONSUMER
- COMMERCIAL
- SMALL
- MEDIUM
- LARGE
- GOVERNMENT & LAW ENFORCEMENT
- MILITARY
- SMALL
- NANO
- MICRO
- MINI
- TACTICAL
- CLOSE RANGE
- SHORT RANGE
- MEDIUM RANGE MEDIUM ENDURANCE
- LOW ALTITUDE LONG ENDURANCE
- STRATEGIC
- MALE (MEDIUM-ALTITUDE LONG ENDURANCE)
- HALE (HIGH-ALTITUDE LONG ENDURANCE)
- SMALL
GEOGRAPHICAL ANALYSIS
- EUROPE
- MARKET SIZE & ESTIMATES
- EUROPE MARKET DRIVERS
- EUROPE UAV BATTERY MARKET CHALLENGES
- KEY PLAYERS IN EUROPE UAV BATTERY MARKET
- COUNTRY ANALYSIS
- GERMANY
- GERMANY MARKET SIZE & OPPORTUNITIES
- UNITED KINGDOM
- UNITED KINGDOM MARKET SIZE & OPPORTUNITIES
- FRANCE
- FRANCE MARKET SIZE & OPPORTUNITIES
- ITALY
- ITALY MARKET SIZE & OPPORTUNITIES
- SPAIN
- SPAIN MARKET SIZE & OPPORTUNITIES
- BELGIUM
- BELGIUM MARKET SIZE & OPPORTUNITIES
- POLAND
- POLAND MARKET SIZE & OPPORTUNITIES
- REST OF EUROPE
- REST OF EUROPE MARKET SIZE & OPPORTUNITIES
- GERMANY
- EUROPE
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- TADIRAN BATTERIES
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- EAGLE-PICHER TECHNOLOGIES
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- EPSILOR
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- HES ENERGY SYSTEMS
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- INTELLIGENT ENERGY
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- INVENTUS POWER
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- PLUG POWER
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- RRC POWER SOLUTIONS
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- SHENZHEN GREPOW BATTERY
- COMPANY OVERVIEW
- PRODUCTS
- STRENGTHS & CHALLENGES
- SION POWER
- COMPANY OVERVIEW
- PRODUCTS
- TADIRAN BATTERIES
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – UAV BATTERY
TABLE 2: MARKET BY TECHNOLOGY, HISTORICAL YEARS, 2018-2023 (IN $ MILLION)
TABLE 3: MARKET BY TECHNOLOGY, FORECAST YEARS, 2025-2032 (IN $ MILLION)
TABLE 4: MARKET BY LITHIUM-BASED, HISTORICAL YEARS, 2018-2023 (IN $ MILLION)
TABLE 5: MARKET BY LITHIUM-BASED, FORECAST YEARS, 2025-2032 (IN $ MILLION)
TABLE 6: MARKET BY COMPONENT, HISTORICAL YEARS, 2018-2023 (IN $ MILLION)
TABLE 7: MARKET BY COMPONENT, FORECAST YEARS, 2025-2032 (IN $ MILLION)
TABLE 8: MARKET BY POINT OF SALE, HISTORICAL YEARS, 2018-2023 (IN $ MILLION)
TABLE 9: MARKET BY POINT OF SALE, FORECAST YEARS, 2025-2032 (IN $ MILLION)
TABLE 10: MARKET BY PLATFORM, HISTORICAL YEARS, 2018-2023 (IN $ MILLION)
TABLE 11: MARKET BY PLATFORM, FORECAST YEARS, 2025-2032 (IN $ MILLION)
TABLE 12: MARKET BY COMMERCIAL, HISTORICAL YEARS, 2018-2023 (IN $ MILLION)
TABLE 13: MARKET BY COMMERCIAL, FORECAST YEARS, 2025-2032 (IN $ MILLION)
TABLE 14: MARKET BY MILITARY, HISTORICAL YEARS, 2018-2023 (IN $ MILLION)
TABLE 15: MARKET BY MILITARY, FORECAST YEARS, 2025-2032 (IN $ MILLION)
TABLE 16: MARKET BY SMALL, HISTORICAL YEARS, 2018-2023 (IN $ MILLION)
TABLE 17: MARKET BY SMALL, FORECAST YEARS, 2025-2032 (IN $ MILLION)
TABLE 18: MARKET BY TACTICAL, HISTORICAL YEARS, 2018-2023 (IN $ MILLION)
TABLE 19: MARKET BY TACTICAL, FORECAST YEARS, 2025-2032 (IN $ MILLION)
TABLE 20: MARKET BY STRATEGIC, HISTORICAL YEARS, 2018-2023 (IN $ MILLION)
TABLE 21: MARKET BY STRATEGIC, FORECAST YEARS, 2025-2032 (IN $ MILLION)
TABLE 22: EUROPE MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2018-2023 (IN $ MILLION)
TABLE 23: EUROPE MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2025-2032 (IN $ MILLION)
TABLE 24: KEY PLAYERS OPERATING IN THE EUROPEAN MARKET
TABLE 25: LIST OF MERGERS & ACQUISITIONS
TABLE 26: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 27: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 28: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: KEY MARKET TRENDS
FIGURE 2: PORTER’S FIVE FORCES ANALYSIS
FIGURE 3: GROWTH PROSPECT MAPPING FOR EUROPE
FIGURE 4: MARKET MATURITY ANALYSIS
FIGURE 5: MARKET CONCENTRATION ANALYSIS
FIGURE 6: VALUE CHAIN ANALYSIS
FIGURE 7: KEY BUYING CRITERIA
FIGURE 8: SEGMENT GROWTH POTENTIAL, BY TECHNOLOGY, IN 2024
FIGURE 9: LITHIUM-BASED MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY LITHIUM-BASED, IN 2024
FIGURE 11: LITHIUM-ION MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 12: LITHIUM-POLYMER MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 13: LITHIUM-METAL MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 14: LITHIUM-SULFUR MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 15: NICKEL-BASED MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 16: FUEL CELL MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 17: SODIUM-ION MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 18: SEGMENT GROWTH POTENTIAL, BY COMPONENT, IN 2024
FIGURE 19: CELLS MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 20: ENCLOSURES MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 21: CONNECTORS MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 22: SEGMENT GROWTH POTENTIAL, BY POINT OF SALE, IN 2024
FIGURE 23: OEM MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 24: AFTERMARKET MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 25: SEGMENT GROWTH POTENTIAL, BY PLATFORM, IN 2024
FIGURE 26: CONSUMER MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 27: COMMERCIAL MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 28: SEGMENT GROWTH POTENTIAL, BY COMMERCIAL, IN 2024
FIGURE 29: SMALL MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 30: MEDIUM MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 31: LARGE MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 32: GOVERNMENT & LAW ENFORCEMENT MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 33: MILITARY MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 34: SEGMENT GROWTH POTENTIAL, BY MILITARY, IN 2024
FIGURE 35: SMALL MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 36: SEGMENT GROWTH POTENTIAL, BY SMALL, IN 2024
FIGURE 37: NANO MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 38: MICRO MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 39: MINI MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 40: SEGMENT GROWTH POTENTIAL, BY TACTICAL, IN 2024
FIGURE 41: CLOSE RANGE MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 42: SHORT RANGE MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 43: MEDIUM RANGE MEDIUM ENDURANCE MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 44: LOW ALTITUDE LONG ENDURANCE MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 45: STRATEGIC MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 46: SEGMENT GROWTH POTENTIAL, BY STRATEGIC, IN 2024
FIGURE 47: MALE (MEDIUM-ALTITUDE LONG ENDURANCE) MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 48: HALE (HIGH-ALTITUDE LONG ENDURANCE) MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 49: EUROPE UAV BATTERY MARKET, COUNTRY OUTLOOK, 2024 & 2032 (IN %)
FIGURE 50: GERMANY MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 51: UNITED KINGDOM MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 52: FRANCE MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 53: ITALY MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 54: SPAIN MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 55: BELGIUM MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 56: POLAND MARKET SIZE, 2025-2032 (IN $ MILLION)
FIGURE 57: REST OF EUROPE MARKET SIZE, 2025-2032 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
TURKEY SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
UNITED STATES SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
JAPAN SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
ASIA-PACIFIC SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
EUROPE SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
NORTH AMERICA SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
GLOBAL SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
UNITED STATES WIND ENERGY MARKET FORECAST 2026-2034
-
CANADA WIND ENERGY MARKET FORECAST 2026-2034
-
GERMANY WIND ENERGY MARKET FORECAST 2026-2034