Europe Solar Panel Recycling Market by Process (Thermal, Mechanical, Chemical, Laser) Market by Type (Silicon-Based C-Si, Thin-Film, Other Types) Market by Shelf Life (Early Loss, Normal Loss) Market by Material/Recoverable Components (Glass, Aluminum, Copper, Plastic, Silver, PV Silicon, Other Materials/Recoverable Components), by Geography
EUROPE SOLAR PANEL RECYCLING MARKET OVERVIEW
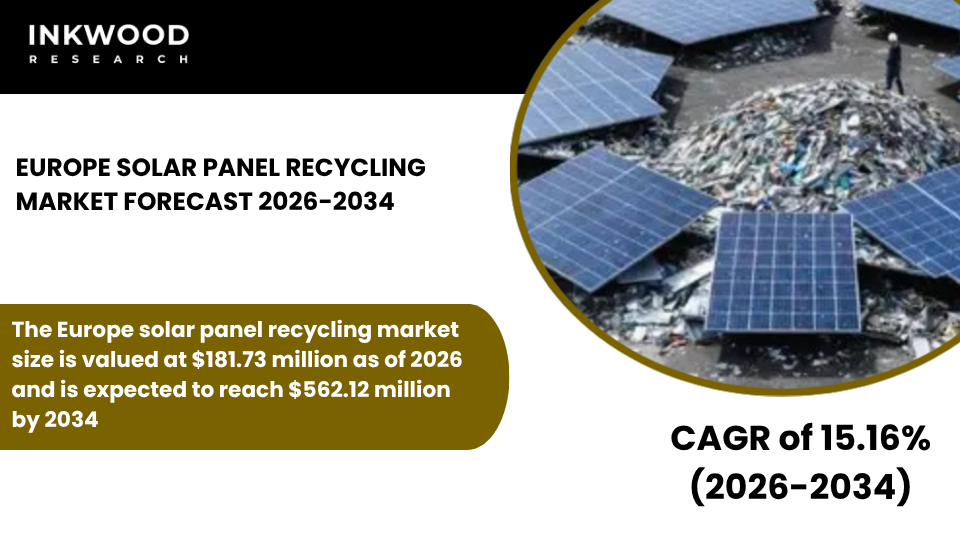
The Europe solar panel recycling market size is valued at $181.73 million as of 2026 and is expected to reach $562.12 million by 2034, progressing with a CAGR of 15.16% during the forecast years, 2026-2034.
Europe’s solar panel recycling market is advancing rapidly, propelled by the region’s pioneering environmental regulations and comprehensive waste management frameworks that prioritize circular economy principles across all industrial sectors. The European Union’s stringent environmental regulations, particularly the Waste Electrical and Electronic Equipment (WEEE) Directive, mandate producer responsibility for photovoltaic panel end-of-life management, creating robust compliance drivers for recycling infrastructure development.
Furthermore, Europe’s mature solar energy market means substantial volumes of first-generation panels are approaching their operational shelf life, generating immediate demand for efficient recycling methods and material recovery capabilities. Technological innovations in mechanical thermal laser processes have enhanced recovery rates for valuable materials like silicon, silver, and aluminum, making recycling operations increasingly profitable and environmentally sustainable.
Additionally, government incentives across multiple member states are supporting capital investments in advanced recycling facilities, while carbon reduction targets incentivize material reuse over virgin resource extraction. The demand for efficient recycling continues to intensify as manufacturers, installers, and utilities seek compliant solutions that align with sustainability commitments and regulatory obligations.
To Know More About This Report, Request a Free Sample Copy
The Europe solar panel recycling market growth assessment includes the analysis of the United Kingdom, Germany, France, Italy, Spain, Belgium, Poland, and Rest of Europe.
The United Kingdom’s solar panel recycling market is experiencing steady development, driven by ambitious net-zero commitments and comprehensive environmental legislation that extends producer responsibility throughout product lifecycles. Following Brexit, the UK maintained alignment with European waste management standards while introducing domestic regulations specifically addressing photovoltaic waste streams.
The country’s substantial residential solar installations from the 2010s feed-in tariff era are now approaching their mid-life service intervals, creating growing volumes of early loss panels requiring proper disposal and material recovery. Moreover, UK environmental agencies have established clear guidelines for solar panel classification, collection, and processing, ensuring consistent regulatory frameworks across England, Scotland, Wales, and Northern Ireland.
Furthermore, investment in recycling infrastructure remains concentrated around major industrial centers, where economies of scale enable cost-effective processing of diverse panel types, including monocrystalline solar panels, polycrystalline solar panels, and thin-film technologies.
Private sector engagement in solar panel recycling continues to expand, with specialized waste management companies establishing dedicated facilities equipped with advanced sorting and separation technologies. These operations focus on maximizing recovery rates for high-value materials while maintaining strict environmental compliance throughout processing stages.
However, collection logistics present ongoing challenges, particularly for residential installations where panel retrieval costs can exceed recovered material values. Despite these obstacles, partnerships between solar installers and recyclers are creating streamlined take-back systems that improve collection efficiency and reduce overall recycling costs for homeowners and businesses.
Conversely, Germany leads Europe’s solar panel recycling sector, supported by decades of environmental policy leadership and the world’s most comprehensive renewable energy infrastructure development programs. The country’s extensive photovoltaic installations, accumulated through aggressive solar subsidies since the early 2000s, are generating substantial recycling volumes as panels reach their planned operational shelf life.
German regulations mandate rigorous waste sorting and material recovery standards, requiring recyclers to achieve minimum recovery thresholds for glass, metals, and semiconductor materials extracted from decommissioned panels. Consequently, German facilities employ cutting-edge mechanical and chemical recycling processes that consistently exceed EU-mandated recovery targets while minimizing environmental impact throughout operations.
According to Germany’s Federal Environment Agency, the country processes significant volumes of photovoltaic waste annually, positioning it as Europe’s largest market for solar panel recycling services. Furthermore, Germany’s robust manufacturing sector creates strong domestic demand for secondary materials, particularly high-purity silicon and precious metals recovered through advanced purification techniques.
Research institutions collaborate closely with industrial recyclers to develop innovative processing methods that enhance material quality and expand applications for recycled components in new panel manufacturing, thereby strengthening circular economy integration across the solar energy value chain. As a result, these factors are set to play a vital role in boosting the solar panel recycling market growth in Europe during the forecasted period.
SEGMENTATION ANALYSIS
The Europe solar panel recycling market is segmented into process, type, shelf life, and material/recoverable components. The type segment is further categorized into silicon-based (c-si), thin-film, and other types.
Silicon-based c-si panels dominate the European market, representing the overwhelming majority of installed photovoltaic capacity across residential, commercial, and utility-scale applications throughout the region. These panels utilize crystalline silicon technology, available in both monocrystalline and polycrystalline configurations, which account for approximately 90% of global solar installations due to superior efficiency ratings and proven long-term performance reliability.
Consequently, recycling infrastructure specifically designed for silicon-based panels has developed extensively across Europe, employing specialized techniques to recover high-purity silicon suitable for remanufacturing applications. The recycling process typically involves thermal treatment to remove polymer encapsulants, followed by mechanical separation of glass, aluminum frames, and silicon wafers using precision crushing and sorting equipment.
Furthermore, chemical etching processes can refine recovered silicon to semiconductor-grade purity, creating valuable secondary materials that reduce manufacturing costs for new panel production while decreasing reliance on energy-intensive virgin silicon extraction. Environmental benefits include substantial carbon footprint reduction compared to primary silicon production, aligning perfectly with European sustainability goals and corporate responsibility commitments across the solar industry.
Market demand for silicon-based panel recycling continues growing as large utility installations from the 2010s approach decommissioning timelines, creating predictable material streams for specialized recyclers. This segment supports overall market expansion by addressing the largest volume category within photovoltaic waste management, providing scalable solutions that meet stringent environmental regulations while delivering economic value through recovered material sales and processing service fees.
COMPETITIVE INSIGHTS
Some of the top players operating in the Europe solar panel recycling market include Aurubis AG, Rinovasol Group, SIC Processing GmbH, Silcontel Ltd, etc.
Aurubis AG operates as Europe’s leading integrated metals producer and recycler, headquartered in Hamburg, Germany, specializing in complex recycling solutions for electronic waste, including photovoltaic panels and semiconductor materials. The company leverages its extensive metallurgical expertise to extract valuable metals from solar panels, including copper, silver, and precious metals embedded within photovoltaic cells and electrical components.
Aurubis employs advanced pyrometallurgical and hydrometallurgical processes that achieve exceptional recovery rates for high-value materials while meeting strict European environmental standards throughout operations. The company’s multi-metal recovery capabilities enable simultaneous processing of diverse waste streams, creating operational efficiencies that enhance profitability and environmental performance across recycling operations.
Additionally, Aurubis maintains an extensive logistics network across Europe, facilitating efficient collection and transportation of decommissioned panels from solar farms, commercial installations, and residential projects throughout major markets. This comprehensive infrastructure positions the company as a strategic partner for solar manufacturers and utilities seeking compliant, economically viable end-of-life panel management solutions across the European market.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Process, Type, Shelf Life, and Material / Recoverable Components |
| Countries Analyzed | The United Kingdom, Germany, France, Italy, Spain, Poland, Belgium, and Rest of Europe |
| Companies Analyzed | Aurubis AG, Canadian Solar Inc, ECS Refining, Envela Corporation, First Solar Inc, Hanwha Group, JA Solar Co Ltd, Reiling Group, Rinovasol Group, Sharp Corporation, SiC Processing GmbH, Silcontel Ltd, Silrec Corporation, Trina Solar, Yingli Energy Co |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- THE MARKET IS EXPERIENCING RAPID GROWTH DUE TO INCREASING SOLAR PANEL INSTALLATIONS WORLDWIDE
- TECHNOLOGICAL ADVANCEMENTS IN RECYCLING PROCESSES ARE IMPROVING MATERIAL RECOVERY EFFICIENCY
- GOVERNMENT POLICIES AND REGULATIONS ARE MANDATING PROPER DISPOSAL AND RECYCLING OF SOLAR PANELS
MARKET DYNAMICS
- KEY DRIVERS
- RISING GLOBAL SOLAR CAPACITY AND RETIREMENT OF OLD PANELS INCREASE RECYCLING DEMAND
- STRINGENT ENVIRONMENTAL REGULATIONS PROMOTE SUSTAINABLE DISPOSAL OF SOLAR WASTE
- IMPROVEMENTS IN RECYCLING TECHNOLOGIES REDUCE COST AND INCREASE MATERIAL RECOVERY
- GOVERNMENT INCENTIVES AND SUBSIDIES ENCOURAGE INVESTMENTS IN SOLAR PANEL RECYCLING INFRASTRUCTURE
- KEY RESTRAINTS
- HIGH CAPITAL COSTS FOR INSTALLING RECYCLING FACILITIES LIMIT MARKET EXPANSION
- LACK OF STANDARDIZATION IN PANEL DESIGN MAKES RECYCLING PROCESSES COMPLEX
- INSUFFICIENT AWARENESS ABOUT SOLAR PANEL END-OF-LIFE MANAGEMENT REDUCES COLLECTION RATES
- TRANSPORTATION AND LOGISTICS CHALLENGES INCREASE OVERALL RECYCLING COSTS
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- EMERGENCE OF AUTOMATED AND ROBOTIC RECYCLING SYSTEMS INCREASES OPERATIONAL EFFICIENCY
- PARTNERSHIPS BETWEEN SOLAR MANUFACTURERS AND RECYCLERS ARE BECOMING COMMON
- INCREASING USE OF SECONDARY MATERIALS IN NEW PANEL MANUFACTURING DRIVES CIRCULAR ECONOMY
- FOCUS ON ECO-FRIENDLY AND CHEMICAL-FREE RECYCLING PROCESSES IS GAINING TRACTION
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR EUROPE
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SUPPLY
- COLLECTION AND LOGISTICS
- DISMANTLING AND SHREDDING
- MATERIAL SORTING
- CHEMICAL PROCESSING
- RECOVERED MATERIAL SUPPLY
- KEY BUYING CRITERIA
- RECYCLING EFFICIENCY
- COST COMPETITIVENESS
- ENVIRONMENTAL COMPLIANCE
- TECHNOLOGICAL ADVANCEMENT
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
SOLAR PANEL RECYCLING MARKET BY PROCESS
- THERMAL
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- MECHANICAL
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- CHEMICAL
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- LASER
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- THERMAL
SOLAR PANEL RECYCLING MARKET BY TYPE
- SILICON-BASED (C-SI)
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- THIN-FILM
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- OTHER TYPES
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- SILICON-BASED (C-SI)
SOLAR PANEL RECYCLING MARKET BY SHELF LIFE
- EARLY LOSS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- NORMAL LOSS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- EARLY LOSS
SOLAR PANEL RECYCLING MARKET BY MATERIAL / RECOVERABLE COMPONENTS
- GLASS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- ALUMINUM
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- COPPER
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- PLASTIC
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- SILVER
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- PV SILICON
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- OTHER MATERIALS / RECOVERABLE COMPONENTS
- MARKET FORECAST FIGURE
- SEGMENT ANALYSIS
- GLASS
GEOGRAPHICAL ANALYSIS
- EUROPE
- MARKET SIZE & ESTIMATES
- EUROPE MARKET DRIVERS
- EUROPE MARKET CHALLENGES
- KEY PLAYERS IN EUROPE SOLAR PANEL RECYCLING MARKET
- COUNTRY ANALYSIS
- GERMANY
- GERMANY MARKET SIZE & OPPORTUNITIES
- UNITED KINGDOM
- UNITED KINGDOM MARKET SIZE & OPPORTUNITIES
- FRANCE
- FRANCE MARKET SIZE & OPPORTUNITIES
- ITALY
- ITALY MARKET SIZE & OPPORTUNITIES
- SPAIN
- SPAIN MARKET SIZE & OPPORTUNITIES
- BELGIUM
- BELGIUM MARKET SIZE & OPPORTUNITIES
- POLAND
- POLAND MARKET SIZE & OPPORTUNITIES
- REST OF EUROPE
- REST OF EUROPE MARKET SIZE & OPPORTUNITIES
- GERMANY
- EUROPE
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- AURUBIS AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- CANADIAN SOLAR INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ECS REFINING
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ENVELA CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- FIRST SOLAR INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- HANWHA GROUP
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- JA SOLAR CO LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- REILING GROUP
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- RINOVASOL GROUP
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SHARP CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SIC PROCESSING GMBH
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SILCONTEL LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SILREC CORPORATION
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- TRINA SOLAR
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- YINGLI ENERGY CO
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- AURUBIS AG
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – SOLAR PANEL RECYCLING
TABLE 2: SOLAR PANEL RECYCLING MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY PROCESS, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY PROCESS, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: MARKET BY TYPE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: MARKET BY TYPE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: MARKET BY SHELF LIFE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: MARKET BY SHELF LIFE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: MARKET BY MATERIAL / RECOVERABLE COMPONENTS, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: MARKET BY MATERIAL / RECOVERABLE COMPONENTS, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: EUROPE MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 12: EUROPE MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 13: KEY PLAYERS OPERATING IN THE EUROPEAN MARKET
TABLE 14: LIST OF MERGERS & ACQUISITIONS
TABLE 15: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 16: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 17: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: KEY MARKET TRENDS
FIGURE 2: PORTER’S FIVE FORCES ANALYSIS
FIGURE 3: GROWTH PROSPECT MAPPING FOR EUROPE
FIGURE 4: MARKET MATURITY ANALYSIS
FIGURE 5: MARKET CONCENTRATION ANALYSIS
FIGURE 6: VALUE CHAIN ANALYSIS
FIGURE 7: KEY BUYING CRITERIA
FIGURE 8: SEGMENT GROWTH POTENTIAL, BY PROCESS, IN 2025
FIGURE 9: THERMAL MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 10: MECHANICAL MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 11: CHEMICAL MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: LASER MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY TYPE, IN 2025
FIGURE 14: SILICON-BASED (C-SI) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: THIN-FILM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: OTHER TYPES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: SEGMENT GROWTH POTENTIAL, BY SHELF LIFE, IN 2025
FIGURE 18: EARLY LOSS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: NORMAL LOSS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: SEGMENT GROWTH POTENTIAL, BY MATERIAL / RECOVERABLE COMPONENTS, IN 2025
FIGURE 21: GLASS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: ALUMINUM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: COPPER MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: PLASTIC MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: SILVER MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: PV SILICON MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: OTHER MATERIALS / RECOVERABLE COMPONENTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: EUROPE SOLAR PANEL RECYCLING MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 29: GERMANY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: UNITED KINGDOM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: FRANCE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 32: ITALY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 33: SPAIN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 34: BELGIUM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 35: POLAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 36: REST OF EUROPE MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
ASIA PACIFIC PRECISION FARMING MARKET FORECAST 2026
-
TURKEY SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
UNITED STATES SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
JAPAN SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
ASIA-PACIFIC SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
EUROPE SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
NORTH AMERICA SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
GLOBAL SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
UNITED STATES WIND ENERGY MARKET FORECAST 2026-2034
-
CANADA WIND ENERGY MARKET FORECAST 2026-2034