
EUROPE SOLAR MICROINVERTER MARKET FORECAST 2026-2034
SCOPE OF THE REPORT
Europe Solar Microinverter Market by Product Type (Single-Phase Microinverters, Three-Phase Microinverters, Standalone Microinverters, Hybrid/Microinverter-Battery Integrated Units, IQ-Series), Market by Connection/System Type (Grid-Tied Microinverters, Off-Grid Microinverters, Hybrid Microinverters Grid-Interactive + Storage Compatible), Market by Power Rating (Below 250 W, 250–400 W, 400–700 W, Above 700 W), Market by Application (Residential Rooftop Solar, Utility-Scale Distributed PV, Off-Grid Systems/Remote Power Supply, Agricultural Solar, Commercial Solar), Market by Distribution Channel (Direct Sales Manufacturers to EPCs or Installers, Online Retail/E-Commerce, Distributors & Wholesalers, OEM Agreements), by Geography
EUROPE SOLAR MICROINVERTER MARKET OVERVIEW
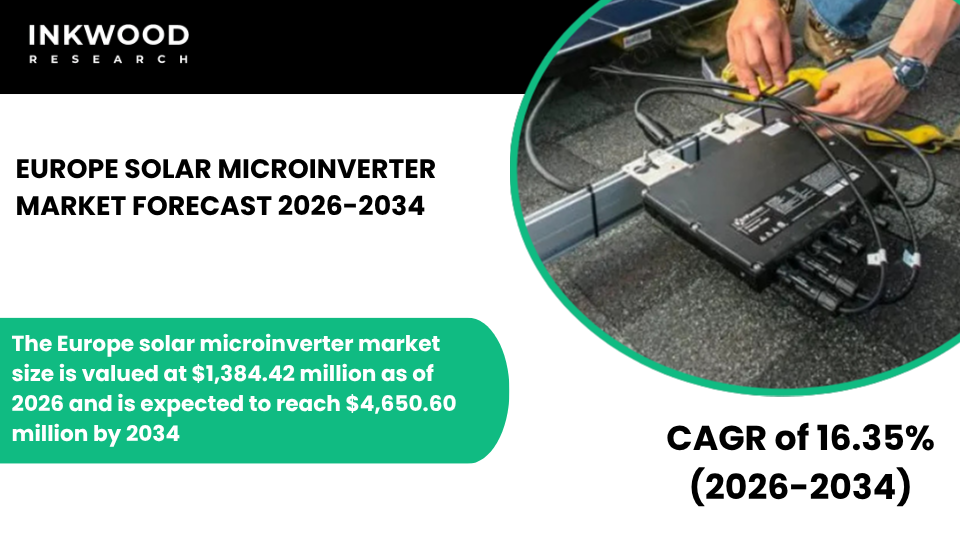
The Europe solar microinverter market size is valued at $1,384.42 million as of 2026 and is expected to reach $4,650.60 million by 2034, progressing with a CAGR of 16.35% during the forecast years, 2026-2034.
The Europe solar microinverter market is experiencing substantial growth, driven by aggressive renewable energy targets and comprehensive policy frameworks across member states. Germany’s Energiewende program, combined with the UK’s Clean Power 2030 Action Plan, is accelerating residential rooftop solar adoption, which directly benefits module-level power electronics deployment.
According to Germany’s Federal Network Agency, the country added over 16.1 GW of new solar capacity in 2024, with two-thirds concentrated in rooftop and building installations. Meanwhile, the UK government’s Solar Roadmap 2025 targets 45-47 GW of solar capacity by 2030, up from 18.1 GW in early 2025, emphasizing rooftop deployment as a cornerstone strategy.
Furthermore, declining solar module costs and improving conversion efficiencies are making solar microinverter systems more economically competitive with traditional string configurations. The integration of advanced monitoring software and battery energy storage capabilities is enhancing system value propositions, particularly for residential and commercial applications.
Government mandates for rapid shutdown compliance, combined with feed-in tariffs and net metering programs, continue to create favorable market conditions. Additionally, the rise of balcony solar systems and plug-in modules across European markets is expanding the addressable customer base beyond traditional homeowners, enabling apartment dwellers to participate in distributed solar energy generation.
The Europe solar microinverter market growth assessment includes the analysis of the United Kingdom, Germany, France, Italy, Spain, Belgium, Poland, and Rest of Europe.
Germany commands a significant share of the European solar microinverter market, supported by decades of renewable energy policy innovation and substantial installed capacity. The country’s commitment to achieving 80% renewable electricity by 2030, as outlined by the German Federal Ministry for Economic Affairs and Climate Action, positions solar photovoltaic systems as critical infrastructure components.
To Know More About This Report, Request a Free Sample Copy
In 2024, renewable energy sources, particularly wind and solar, accounted for approximately 59% of Germany’s electricity generation, demonstrating the nation’s leadership in the clean energy transition. The German market benefits from the Renewable Energy Sources Act (EEG), which provides predictable financial frameworks for solar investments, though recent reforms have shifted toward auction-based mechanisms for larger installations.
Residential rooftop applications dominate solar microinverter demand, driven by the proliferation of balcony solar systems that allow apartment residents to generate clean energy without complex permitting requirements. According to government data, 435,000 new balcony systems were installed in 2024 alone, reflecting strong consumer interest in accessible solar technology.
However, challenges persist in the form of grid connection delays for larger distributed projects and evolving regulations around energy storage integration. The market also faces increasing price competition from Asian manufacturers, though established European brands maintain advantages in service quality, warranty support, and local technical expertise.
Looking forward, Germany’s planned grid modernization investments will address bottlenecks that currently constrain distributed solar deployment, creating additional opportunities for solar microinverter adoption across residential, commercial, and agricultural segments.
The United Kingdom represents a rapidly expanding market for solar microinverters, propelled by ambitious government policies and increasing cost competitiveness of distributed solar systems. The UK’s Clean Power 2030 Action Plan, published by the Department for Energy Security and Net Zero, establishes a clear pathway for solar energy to provide clean electricity at scale while reducing consumer energy bills.
The government’s Future Homes Standard, scheduled for implementation in 2027, will mandate solar photovoltaic panels on most new residential construction, covering at least 40% of a building’s floor area where feasible. This regulatory requirement is projected to save homeowners approximately £530 annually on energy costs while significantly reducing carbon emissions from day one of occupancy.
Furthermore, the UK’s £13.2 billion Warm Homes Plan includes provisions for solar microinverter installations on existing homes, particularly within social housing portfolios, coupled with heat pumps, battery energy storage, and insulation upgrades. Commercial sector opportunities are equally substantial, with the forthcoming Future Buildings Standard expected to mandate rooftop solar on new retail, warehouse, and office developments.
The UK market benefits from streamlined grid connection processes for residential-scale systems, though larger rooftop installations still face administrative challenges. Great British Energy’s inaugural project, announced in March 2025, commits to installing solar panels on approximately 200 schools and 200 NHS facilities, demonstrating public sector leadership in renewable energy procurement.
According to UK government statistics, over 1.7 million solar installations with 18.1 GW cumulative capacity were operational by March 2025, with projections indicating potential for 54-57 GW by 2030 when rooftop deployment accelerates. The market also benefits from the Smart Export Guarantee, which provides compensation for surplus electricity exported to the grid, improving the economic case for residential solar investments.
Despite these favorable conditions, challenges include upfront system costs for existing homeowners, regional variations in grid capacity, and ongoing policy discussions around land use for ground-mounted installations. Collectively, these factors are expected to influence the solar microinverter market in Europe during the forecast period.
The Europe solar microinverter market is segmented into product type, connection/system type, power rating, application, and distribution channel. The product type segment is further categorized into single-phase microinverters, three-phase microinverters, standalone microinverters, hybrid/microinverter-battery integrated units, and IQ-series.
Single-phase microinverters play a pivotal role in the European market, driven primarily by their suitability for residential applications using standard 230V single-phase electrical service prevalent across European households. These devices excel in converting DC power from individual solar panels into alternating current that seamlessly integrates with typical home electrical systems, offering peak conversion efficiencies exceeding 97%.
The segment benefits from continuous technological refinements that have reduced component counts, improved thermal management, and enhanced wireless communication capabilities for remote monitoring. Growing demand stems from multiple factors, including government mandates for new home construction with integrated solar technology, existing homeowner retrofits seeking energy independence amid rising utility costs, and the proliferation of balcony solar systems in Germany and other markets that enable apartment dwellers to participate in distributed generation.
Furthermore, single-phase solar microinverters align perfectly with European safety regulations requiring rapid shutdown functionality, as module-level architecture inherently meets these requirements without additional equipment. The segment also benefits from installer familiarity and established supply chains, which reduce installation complexity and project risks.
As residential rooftop solar adoption accelerates across the UK, Germany, France, and other European markets, single-phase microinverters remain positioned as the foundational technology enabling the clean energy transition at the household level, supporting overall market growth through proven reliability, simplified installation procedures, and declining per-unit costs that improve system economics.
Some of the top players operating in the Europe solar microinverter market include Enphase Energy Inc, SMA Solar Technology AG, Hoymiles Power Electronics Inc, APsystems (Altenergy Power System Inc), etc.
Enphase Energy Inc is a global energy technology company, specializing in microinverter-based solar and battery energy storage systems. The company pioneered module-level power electronics and has established itself as the world’s leading supplier of solar microinverters, with approximately 84.8 million units shipped and more than 5.0 million systems deployed across over 160 countries.
Enphase’s product portfolio includes its flagship IQ Series microinverters, which feature advanced gallium nitride power electronics, integrated rapid shutdown capabilities, and seamless integration with the company’s battery energy storage offerings, such as the IQ Battery 10C. The company operates a comprehensive software platform called Enlighten, providing real-time monitoring, remote diagnostics, and performance analytics accessible through mobile and web applications.
Enphase distinguishes itself through extended warranty coverage, with its fourth-generation products backed by industry-leading 15-year warranties, comprehensive technical support infrastructure, and a focus on residential and commercial distributed generation markets. The company has expanded U.S. domestic manufacturing capacity to meet local content requirements while maintaining global supply chain capabilities, positioning itself to serve European markets through established distribution networks and installer partnerships across key countries, including Germany, the UK, France, and the Netherlands.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Product Type, Connection / System Type, Power Rating, Application, Distribution Channel |
| Countries Analyzed | The United Kingdom, Germany, France, Italy, Spain, Poland, Belgium, and Rest of Europe |
| Companies Analyzed | Enphase Energy Inc, SolarEdge Technologies Inc, Hoymiles Power Electronics Inc, SMA Solar Technology AG, APsystems (Altenergy Power System Inc), Darfon Electronics Corp, Sungrow Power Supply Co Ltd, Chilicon Power LLC, Sparq Systems Inc, Leading Edge Power, ReneSola Ltd, ABB Ltd, Delta Electronics Inc, GoodWe, Fronius International GmbH |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE & FORECAST
- MARKET OVERVIEW
- SCOPE OF STUDY
- CRISIS SCENARIO ANALYSIS
- MAJOR MARKET FINDINGS
- MICROINVERTERS ARE GAINING SHARE OVER STRING INVERTERS DUE TO SUPERIOR MODULE LEVEL OPTIMIZATION AND SAFETY PERFORMANCE
- RESIDENTIAL ROOFTOP INSTALLATIONS ACCOUNT FOR THE LARGEST DEMAND SHARE, DRIVEN BY DESIGN FLEXIBILITY AND SHADE TOLERANCE
- TECHNOLOGICAL DIFFERENTIATION IS CENTERED AROUND HIGHER POWER RATINGS AND INTEGRATED MONITORING CAPABILITIES
MARKET DYNAMICS
- KEY DRIVERS
- RISING RESIDENTIAL SOLAR ADOPTION IS ACCELERATING DEMAND FOR EASY TO INSTALL AND SCALABLE INVERTER SOLUTIONS
- INCREASING FOCUS ON SYSTEM SAFETY AND RAPID SHUTDOWN COMPLIANCE IS FAVORING MICROINVERTER DEPLOYMENT
- DECLINING MODULE COSTS ARE IMPROVING THE OVERALL ECONOMICS OF MICROINVERTER-BASED SYSTEMS
- GROWING CONSUMER AWARENESS OF ENERGY YIELD OPTIMIZATION IS DRIVING UPGRADE DEMAND FROM STRING INVERTERS
- KEY RESTRAINTS
- HIGHER UPFRONT SYSTEM COSTS CONTINUE TO LIMIT MICROINVERTER PENETRATION IN PRICE-SENSITIVE MARKETS
- COMPLEXITY IN AFTER-SALES SERVICE CAN INCREASE MAINTENANCE COSTS FOR LARGE-SCALE INSTALLATIONS
- DEPENDENCE ON IMPORTED ELECTRONIC COMPONENTS EXPOSES SUPPLY CHAINS TO PRICE AND AVAILABILITY RISKS
- LIMITED SUITABILITY FOR UTILITY SCALE PROJECTS CONSTRAINS THE ADDRESSABLE MARKET SIZE
- KEY DRIVERS
KEY ANALYTICS
- KEY MARKET TRENDS
- MANUFACTURERS ARE INTRODUCING HIGH-POWER MICROINVERTERS TO SUPPORT NEXT GENERATION SOLAR MODULES
- INTEGRATION OF ADVANCED MONITORING SOFTWARE IS BECOMING A STANDARD PRODUCT FEATURE
- STRATEGIC PARTNERSHIPS WITH INSTALLERS ARE EMERGING AS A KEY GO-TO MARKET STRATEGY
- INCREASING ADOPTION OF AC MODULES IS STRENGTHENING THE MICROINVERTER ECOSYSTEM
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- GROWTH PROSPECT MAPPING
- GROWTH PROSPECT MAPPING FOR EUROPE
- MARKET MATURITY ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SOURCING
- POWER ELECTRONICS DESIGN
- COMPONENT MANUFACTURING
- INVERTER ASSEMBLY
- QUALITY TESTING
- DISTRIBUTION CHANNELS
- INSTALLATION SERVICES
- KEY BUYING CRITERIA
- CONVERSION EFFICIENCY
- SYSTEM RELIABILITY
- WARRANTY COVERAGE
- MONITORING FEATURES
- REGULATORY FRAMEWORK
- KEY MARKET TRENDS
SOLAR MICROINVERTER MARKET BY PRODUCT TYPE
- SINGLE-PHASE MICROINVERTERS
- THREE-PHASE MICROINVERTERS
- STANDALONE MICROINVERTERS
- HYBRID / MICROINVERTER-BATTERY INTEGRATED UNITS
- IQ-SERIES
SOLAR MICROINVERTER MARKET BY CONNECTION / SYSTEM TYPE
- GRID-TIED MICROINVERTERS
- OFF-GRID MICROINVERTERS
- HYBRID MICROINVERTERS (GRID-INTERACTIVE + STORAGE COMPATIBLE)
SOLAR MICROINVERTER MARKET BY POWER RATING
- BELOW 250 W
- 250–400 W
- 400–700 W
- ABOVE 700 W
SOLAR MICROINVERTER MARKET BY APPLICATION
- RESIDENTIAL ROOFTOP SOLAR
- UTILITY-SCALE DISTRIBUTED PV
- OFF-GRID SYSTEMS / REMOTE POWER SUPPLY
- AGRICULTURAL SOLAR
- COMMERCIAL SOLAR
- SMALL-SIZE
- MID-SIZE
SOLAR MICROINVERTER MARKET BY DISTRIBUTION CHANNEL
- DIRECT SALES (MANUFACTURERS TO EPCS OR INSTALLERS)
- ONLINE RETAIL / E-COMMERCE
- DISTRIBUTORS & WHOLESALERS
- OEM AGREEMENTS
GEOGRAPHICAL ANALYSIS
- EUROPE
- MARKET SIZE & ESTIMATES
- EUROPE MARKET DRIVERS
- EUROPE MARKET CHALLENGES
- KEY PLAYERS IN EUROPE SOLAR MICROINVERTER MARKET
- COUNTRY ANALYSIS
- GERMANY
- GERMANY MARKET SIZE & OPPORTUNITIES
- UNITED KINGDOM
- UNITED KINGDOM MARKET SIZE & OPPORTUNITIES
- FRANCE
- FRANCE MARKET SIZE & OPPORTUNITIES
- ITALY
- ITALY MARKET SIZE & OPPORTUNITIES
- SPAIN
- SPAIN MARKET SIZE & OPPORTUNITIES
- BELGIUM
- BELGIUM MARKET SIZE & OPPORTUNITIES
- POLAND
- POLAND MARKET SIZE & OPPORTUNITIES
- REST OF EUROPE
- REST OF EUROPE MARKET SIZE & OPPORTUNITIES
- GERMANY
- EUROPE
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPANY PROFILES
- ENPHASE ENERGY INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SOLAREDGE TECHNOLOGIES INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- HOYMILES POWER ELECTRONICS INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SMA SOLAR TECHNOLOGY AG
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- APSISTEMS (ALTENERGY POWER SYSTEM INC)
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- DARFON ELECTRONICS CORP
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SUNGROW POWER SUPPLY CO LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- CHILICON POWER LLC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- SPARQ SYSTEMS INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- LEADING EDGE POWER
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- RENESOLA LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ABB LTD
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- DELTA ELECTRONICS INC
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- GOODWE
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- FRONIUS INTERNATIONAL GMBH
- COMPANY OVERVIEW
- PRODUCTS / SERVICES LIST
- STRENGTHS & CHALLENGES
- ENPHASE ENERGY INC
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – SOLAR MICROINVERTER
TABLE 2: SOLAR MICROINVERTER MARKET REGULATORY FRAMEWORK
TABLE 3: MARKET BY PRODUCT TYPE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 4: MARKET BY PRODUCT TYPE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 5: MARKET BY CONNECTION / SYSTEM TYPE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 6: MARKET BY CONNECTION / SYSTEM TYPE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 7: MARKET BY POWER RATING, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 8: MARKET BY POWER RATING, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 9: MARKET BY APPLICATION, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 10: MARKET BY APPLICATION, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 11: MARKET BY COMMERCIAL SOLAR, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 12: MARKET BY COMMERCIAL SOLAR, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 13: MARKET BY DISTRIBUTION CHANNEL, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 14: MARKET BY DISTRIBUTION CHANNEL, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 15: EUROPE MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 16: EUROPE MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 17: KEY PLAYERS OPERATING IN THE EUROPEAN MARKET
TABLE 18: LIST OF MERGERS & ACQUISITIONS
TABLE 19: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 20: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 21: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR EUROPE
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY PRODUCT TYPE, IN 2025
FIGURE 11: SINGLE-PHASE MICROINVERTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: THREE-PHASE MICROINVERTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: STANDALONE MICROINVERTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 14: HYBRID / MICROINVERTER-BATTERY INTEGRATED UNITS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: IQ-SERIES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: SEGMENT GROWTH POTENTIAL, BY CONNECTION / SYSTEM TYPE, IN 2025
FIGURE 17: GRID-TIED MICROINVERTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: OFF-GRID MICROINVERTERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: HYBRID MICROINVERTERS (GRID-INTERACTIVE + STORAGE COMPATIBLE) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: SEGMENT GROWTH POTENTIAL, BY POWER RATING, IN 2025
FIGURE 21: BELOW 250 W MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: 250–400 W MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: 400–700 W MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: ABOVE 700 W MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: SEGMENT GROWTH POTENTIAL, BY APPLICATION, IN 2025
FIGURE 26: RESIDENTIAL ROOFTOP SOLAR MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: UTILITY-SCALE DISTRIBUTED PV MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: OFF-GRID SYSTEMS / REMOTE POWER SUPPLY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 29: AGRICULTURAL SOLAR MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: COMMERCIAL SOLAR MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: SEGMENT GROWTH POTENTIAL, BY COMMERCIAL SOLAR, IN 2025
FIGURE 32: SMALL-SIZE COMMERCIAL SOLAR MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 33: MID-SIZE COMMERCIAL SOLAR MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 34: SEGMENT GROWTH POTENTIAL, BY DISTRIBUTION CHANNEL, IN 2025
FIGURE 35: DIRECT SALES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 36: ONLINE RETAIL / E-COMMERCE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 37: DISTRIBUTORS & WHOLESALERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 38: OEM AGREEMENTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 39: EUROPE SOLAR MICROINVERTER MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 40: GERMANY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 41: UNITED KINGDOM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 42: FRANCE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 43: ITALY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 44: SPAIN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 45: BELGIUM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 46: POLAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 47: REST OF EUROPE MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
TURKEY SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
UNITED STATES SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
JAPAN SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
ASIA-PACIFIC SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
EUROPE SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
NORTH AMERICA SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
GLOBAL SOLAR ENCAPSULATION MARKET FORECAST 2026-2034
-
UNITED STATES WIND ENERGY MARKET FORECAST 2026-2034
-
CANADA WIND ENERGY MARKET FORECAST 2026-2034
-
GERMANY WIND ENERGY MARKET FORECAST 2026-2034