Australia Acute Care at Home Market by Service Type (Physician Care Services, Skilled Nursing Services, Diagnostic & Monitoring Services, Therapy Services, Medication Administration Services, Other Acute Care Services) Market by Component (Remote Patient Monitoring Devices, Telehealth & Virtual Care Platforms, Clinical Command Center Software, Therapeutic Equipment, Other Components) Market by Disease Indication (Respiratory Diseases, Cardiovascular Diseases, Infectious Diseases, Renal Disorders, Post-Surgical Care, Other Acute Conditions), by Geography
AUSTRALIA ACUTE CARE AT HOME MARKET OVERVIEW
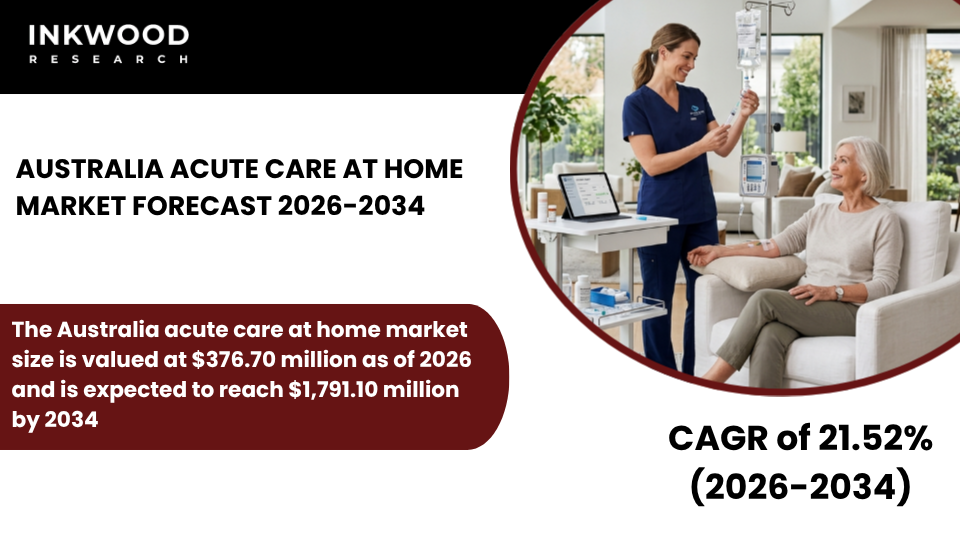
The Australia acute care at home market size is valued at $376.70 million as of 2026 and is expected to reach $1,791.10 million by 2034, progressing with a CAGR of 21.52% during the forecast years, 2026–2034.
MARKET INSIGHTS
Australia has one of the most well-established acute care at home frameworks globally, built on a long-standing model known as Hospital in the Home (HITH). HITH is formally defined as a 24-hour, 7-day-a-week service delivering acute inpatient-equivalent care through skilled clinical staff, hospital technologies, equipment, and medication, directly within a patient’s place of residence.
This model is well integrated into state and territory public hospital systems, with HITH programs now operating across New South Wales, Queensland, Victoria, and other jurisdictions. Reflecting the broader healthcare funding environment, the Australian Institute of Health and Welfare (AIHW) reported that total health spending in Australia reached $270.5 billion in 2023-24, equating to $10,037 per person and approximately 10.1% of national economic activity, with governments collectively funding approximately 69.6% of total health expenditure.
This substantial public funding base reinforces the structural capacity for continued investment in home-based acute care programs. Additionally, hospital spending reached $113.8 billion in 2023-24, a 1.2% increase from the prior year, with a 4.1% rise in the number of patient separations, further intensifying the case for diverting suitable patients to HITH and acute home care delivery models.
Telehealth integration is rapidly accelerating the clinical and commercial potential of the Australia acute care at home market. Telstra Health, one of the country’s leading digital health technology providers, has partnered with hospitals across Queensland and New South Wales to deploy its Virtual Health Platform within HITH programs. A study published in the Asia Pacific Journal of Health Management, based on Telstra Health’s program at Mackay Base Hospital (Queensland Health), demonstrated a significant reduction in hospital readmission risk, average length of stay, and risk of same-diagnosis readmission within 28 days.
These outcomes represent compelling clinical and economic evidence that virtual care-enabled HITH models can materially reduce inpatient demand and improve patient outcomes. Furthermore, in New South Wales, the state’s five-year Virtual Care Strategy has driven the scaling of HITH programs as an alternative care pathway to address emergency department overcrowding and ambulance ramping, with recent expansions including the Virtual Rural Generalist Service and continuous remote monitoring deployments supported by AI-powered wearable devices.
Australia’s unique geography makes home-based acute care particularly strategic, as vast rural and remote populations face systemic barriers to accessing hospital-based care. Programs like the Royal Flying Doctor Service’s virtual acute care initiatives and remote telehealth deployments highlight how the acute home healthcare model is being adapted to address Australia’s distinctive access challenges.
Nevertheless, the Australia acute care at home market also faces notable constraints. Workforce shortages, particularly in skilled nursing outside metropolitan centres, limit service capacity in regional and remote areas. Moreover, despite evidence supporting HITH as a safe and cost-effective care model, clinical uptake remains suboptimal in some jurisdictions, partly due to varying state-level regulatory standards and inconsistent funding frameworks across the public and private sectors.
The AIHW has also noted that respiratory conditions accounted for $5.8 billion in Australian health system expenditure in 2023-24, representing one of the most resource-intensive disease groups and a primary clinical target for future HITH program expansion. These factors, in turn, are set to influence the acute care at home market growth in Australia during the forecast period.
To Know More About This Report, Request a Free Sample Copy
SEGMENTATION ANALYSIS
The Australia acute care at home market is segmented by service type, component, and disease indication. The disease indication segment is further categorized into respiratory diseases, cardiovascular diseases, infectious diseases, renal disorders, post-surgical care, and other acute conditions.
Respiratory diseases represent one of the largest and most clinically established sub-segments driving demand within the Australia acute care at home market. This sub-segment encompasses home-based management of conditions, including chronic obstructive pulmonary disease (COPD), pneumonia, acute asthma exacerbations, and other acute respiratory infections, delivered through a combination of skilled nursing visits, remote patient monitoring devices, and virtual clinical oversight.
The scale of this disease burden in Australia is significant. According to the AIHW, in 2023-24, respiratory conditions accounted for 4.1% of all hospitalisations, representing 521,000 patient separations, while health system expenditure on respiratory diseases reached $5.8 billion in the same year. These figures make respiratory care one of the most compelling areas for HITH-based intervention, given the potential to divert clinically stable patients from inpatient beds to well-monitored home settings.
In New South Wales, acute respiratory infection pathways have been a priority deployment area for hospital virtual ward programs, with remote monitoring solutions tracking oxygen saturation, breathing rate, and heart rate continuously through wearable devices. Furthermore, COPD and heart failure are among the primary disease pathways targeted under existing HITH programs across Queensland and Victoria. For vendors and health systems alike, expanding respiratory-focused acute home care capacity represents both an immediate commercial priority and a clinically high-impact investment within the Australian market.
COMPETITIVE INSIGHTS
Some of the top players operating in the Australia acute care at home market include Telstra Health, Ramsay Home Health, Australian Unity, and CareMonitor, among others.
Telstra Health is an Australian digital health technology company and a subsidiary of Telstra Corporation, headquartered in Melbourne. It is one of the most widely deployed enablers of HITH and virtual care programs across the Australian acute home healthcare market. Its flagship Virtual Health Platform supports hospitals, aged care providers, allied health services, and community care organizations in delivering continuous remote monitoring, telehealth video consultations, and clinical observations management to patients in their homes.
Telstra Health’s platform has been adopted by public health services across Queensland, New South Wales, and other states, with documented outcomes including significant reductions in readmission rates and hospital length of stay. Its deep integration with existing hospital workflows and strong relationships with state health departments position it as a key infrastructure partner for health systems scaling their acute care at home service delivery.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Service Type, Component, Disease Indication |
| Country Analyzed | Australia |
| Companies Analyzed | Ramsay Home Health, Amplar Health, Allianz Care Australia, CareMonitor, Pop-Up Health, Telstra Health, Vitalis Health, Australian Unity, My Emergency Doctor, Philips Healthcare |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY
- MARKET SIZE, SHARE & ESTIMATES
- MARKET OVERVIEW
- SCOPE OF STUDY
- MAJOR MARKET FINDINGS
- AUSTRALIA’S ACUTE CARE AT HOME MARKET IS WELL-ESTABLISHED WITH HOSPITAL-IN-THE-HOME PROGRAMS WIDELY ADOPTED
- GOVERNMENT SUPPORT AND PUBLIC HEALTH INITIATIVES ARE DRIVING MARKET EXPANSION
- RURAL AND REMOTE HEALTHCARE DELIVERY IS BENEFITING FROM HOME-BASED CARE MODELS
- STRONG INTEGRATION OF COMMUNITY HEALTH SERVICES IS SUPPORTING CARE CONTINUITY
MARKET DYNAMICS
- KEY DRIVERS
- GOVERNMENT FUNDING AND POLICY SUPPORT FOR HOSPITAL-IN-THE-HOME PROGRAMS DRIVE ADOPTION
- GEOGRAPHICAL CHALLENGES AND REMOTE POPULATIONS INCREASE THE NEED FOR HOME-BASED CARE
- RISING HEALTHCARE COSTS ENCOURAGE SHIFT FROM HOSPITAL TO HOME SETTINGS
- ADVANCED TELEHEALTH INFRASTRUCTURE SUPPORTS SCALABLE CARE DELIVERY
- KEY RESTRAINTS
- LIMITED AVAILABILITY OF SKILLED HEALTHCARE PROFESSIONALS IN REMOTE AREAS RESTRICTS GROWTH
- HIGH COSTS OF IMPLEMENTING AND MAINTAINING HOME CARE INFRASTRUCTURE POSE CHALLENGES
- REGULATORY COMPLEXITIES ACROSS STATES IMPACT UNIFORM SERVICE DELIVERY
- PATIENT SAFETY CONCERNS IN COMPLEX CASES LIMIT FULL-SCALE ADOPTION
- KEY DRIVERS
STRATEGIC MARKET ANALYTICS
- GROWTH METRICS
- TAM, SAM & SOM OPPORTUNITY ANALYSIS
- EMERGING MARKET TRENDS & PARADIGM SHIFTS
- EXPANSION OF HOSPITAL-IN-THE-HOME PROGRAMS IS A KEY MARKET TREND
- INCREASED USE OF TELEHEALTH SERVICES IS ENHANCING ACCESS TO CARE
- FOCUS ON RURAL HEALTHCARE DELIVERY IS DRIVING INNOVATION IN HOME CARE MODELS
- COLLABORATION BETWEEN PUBLIC AND PRIVATE PROVIDERS IS STRENGTHENING SERVICE DELIVERY
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- PESTLE ANALYSIS
- POLITICAL
- ECONOMIC
- SOCIAL LANDSCAPE
- TECHNOLOGY
- LEGAL
- ENVIRONMENTAL
- GROWTH OPPORTUNITY MAPPING & HEATMAP
- GROWTH PROSPECT MAPPING FOR AUSTRALIA
- MARKET MATURITY & LIFECYCLE ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- GROWTH METRICS
ACUTE CARE AT HOME VALUE CHAIN & DECISION FRAMEWORK
- VALUE CHAIN ANALYSIS
- MEDICAL DEVICE SUPPLIERS
- TECHNOLOGY PROVIDERS
- HEALTHCARE PROVIDERS
- HOME CARE SERVICES
- PAYERS INSURERS
- PATIENT MONITORING
- KEY BUYING CRITERIA
- CLINICAL EFFECTIVENESS
- COST EFFICIENCY
- TECHNOLOGY INTEGRATION
- PATIENT SAFETY
- PRICING MODELS, REIMBURSEMENT STRUCTURES & CARE DELIVERY OPTIMIZATION STRATEGIES
- REGULATORY & POLICY LANDSCAPE ANALYSIS
- VALUE CHAIN ANALYSIS
ACUTE CARE AT HOME MARKET BY SERVICE TYPE
- PHYSICIAN CARE SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- SKILLED NURSING SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- DIAGNOSTIC & MONITORING SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- THERAPY SERVICES (PHYSICAL / OCCUPATIONAL / RESPIRATORY)
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- MEDICATION ADMINISTRATION SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER ACUTE CARE SERVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PHYSICIAN CARE SERVICES
ACUTE CARE AT HOME MARKET BY COMPONENT
- REMOTE PATIENT MONITORING DEVICES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- TELEHEALTH & VIRTUAL CARE PLATFORMS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- CLINICAL COMMAND CENTER SOFTWARE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- THERAPEUTIC EQUIPMENT
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER COMPONENTS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- REMOTE PATIENT MONITORING DEVICES
ACUTE CARE AT HOME MARKET BY DISEASE INDICATION
- RESPIRATORY DISEASES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- CARDIOVASCULAR DISEASES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- INFECTIOUS DISEASES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- RENAL DISORDERS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- POST-SURGICAL CARE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OTHER ACUTE CONDITIONS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- RESPIRATORY DISEASES
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPETITOR POSITIONING & DIFFERENTIATION MAP
- COMPANY PROFILES
- RAMSAY HOME HEALTH
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- AMPLAR HEALTH
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- ALLIANZ CARE AUSTRALIA
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- CAREMONITOR
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- POP-UP HEALTH
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- TELSTRA HEALTH
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- VITALIS HEALTH
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- AUSTRALIAN UNITY
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- MY EMERGENCY DOCTOR
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- PHILIPS HEALTHCARE
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- RAMSAY HOME HEALTH
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – ACUTE CARE AT HOME MARKET
TABLE 2: PRICING MODELS, REIMBURSEMENT STRUCTURES & CARE DELIVERY OPTIMIZATION STRATEGIES
TABLE 3: REGULATORY & POLICY LANDSCAPE ANALYSIS
TABLE 4: MARKET BY SERVICE TYPE, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 5: MARKET BY SERVICE TYPE, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 6: MARKET BY COMPONENT, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 7: MARKET BY COMPONENT, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 8: MARKET BY DISEASE INDICATION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 9: MARKET BY DISEASE INDICATION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 10: KEY PLAYERS OPERATING IN THE AUSTRALIAN MARKET
TABLE 11: LIST OF MERGERS & ACQUISITIONS
TABLE 12: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 13: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 14: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR AUSTRALIA
FIGURE 6: MARKET MATURITY ANALYSIS
FIGURE 7: MARKET CONCENTRATION ANALYSIS
FIGURE 8: VALUE CHAIN ANALYSIS
FIGURE 9: KEY BUYING CRITERIA
FIGURE 10: SEGMENT GROWTH POTENTIAL, BY SERVICE TYPE, IN 2025
FIGURE 11: PHYSICIAN CARE SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 12: SKILLED NURSING SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 13: DIAGNOSTIC & MONITORING SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 14: THERAPY SERVICES (PHYSICAL / OCCUPATIONAL / RESPIRATORY) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: MEDICATION ADMINISTRATION SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: OTHER ACUTE CARE SERVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: SEGMENT GROWTH POTENTIAL, BY COMPONENT, IN 2025
FIGURE 18: REMOTE PATIENT MONITORING DEVICES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: TELEHEALTH & VIRTUAL CARE PLATFORMS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 20: CLINICAL COMMAND CENTER SOFTWARE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: THERAPEUTIC EQUIPMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: OTHER COMPONENTS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: SEGMENT GROWTH POTENTIAL, BY DISEASE INDICATION, IN 2025
FIGURE 24: RESPIRATORY DISEASES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: CARDIOVASCULAR DISEASES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 26: INFECTIOUS DISEASES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: RENAL DISORDERS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: POST-SURGICAL CARE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 29: OTHER ACUTE CONDITIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
RELATED REPORTS
-
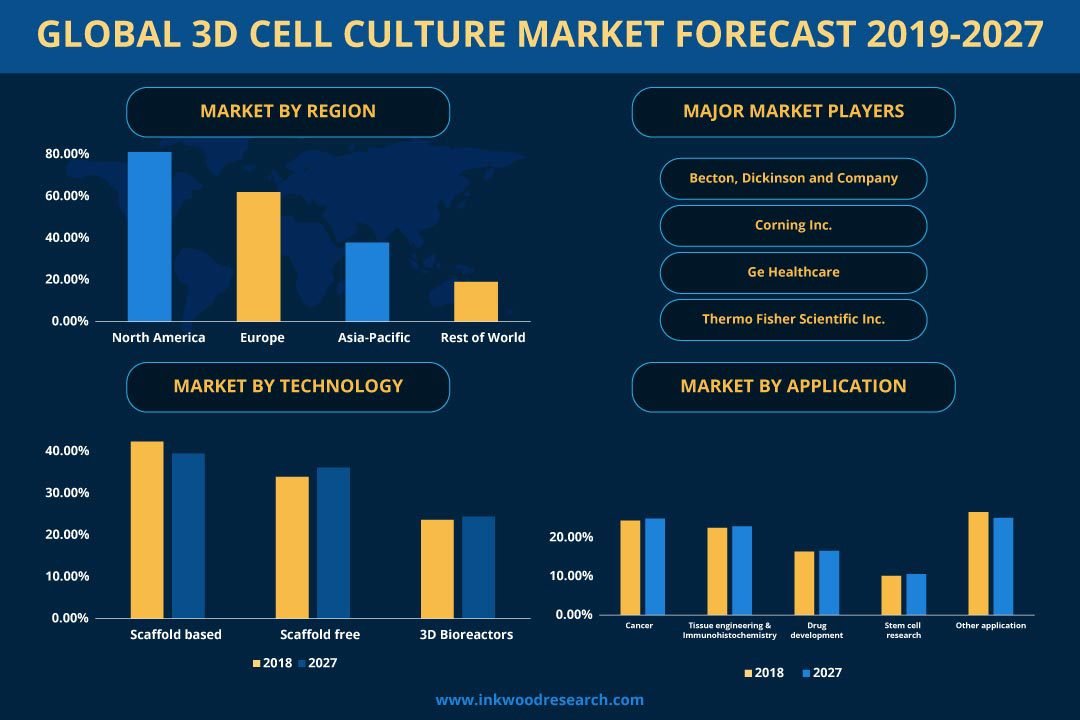
GLOBAL 3D CELL CULTURE MARKET FORECAST 2026
-
NORTH AMERICA 3D CELL CULTURE MARKET FORECAST 2026
-
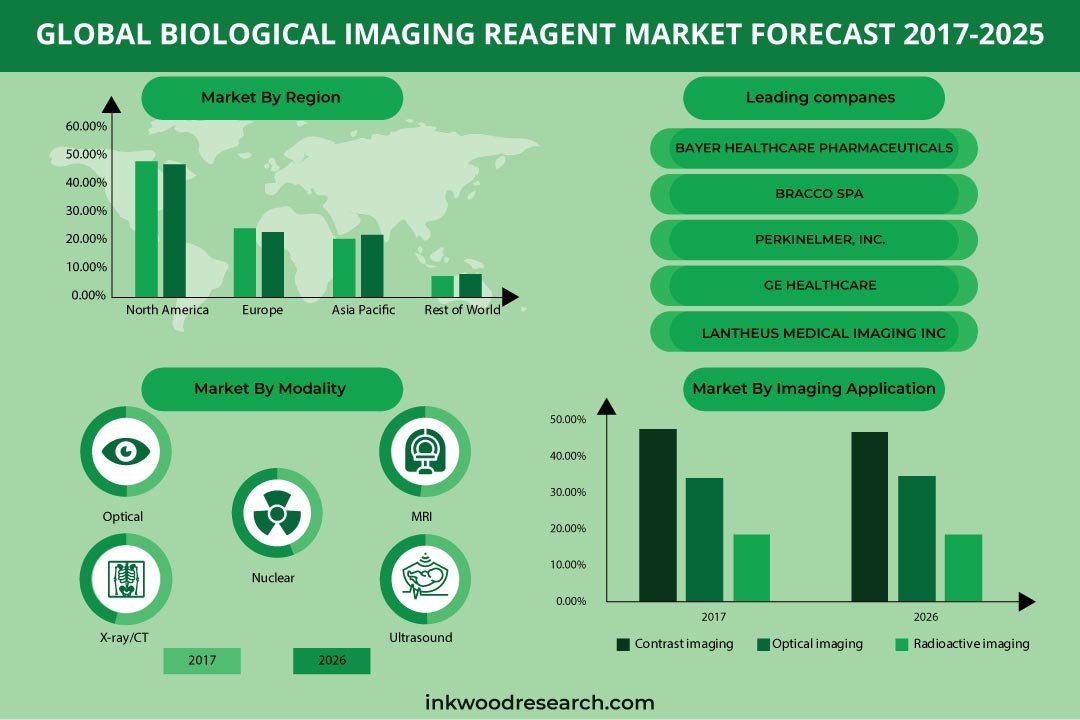
GLOBAL BIOLOGICAL IMAGING REAGENT MARKET FORECAST 2026
-

UNITED STATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED KINGDOM AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

UNITED ARAB EMIRATES AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SOUTH KOREA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SINGAPORE AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

SAUDI ARABIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034
-

AUSTRALIA AI-DRIVEN CLOUD MIGRATION SERVICES MARKET FORECAST 2026-2034