
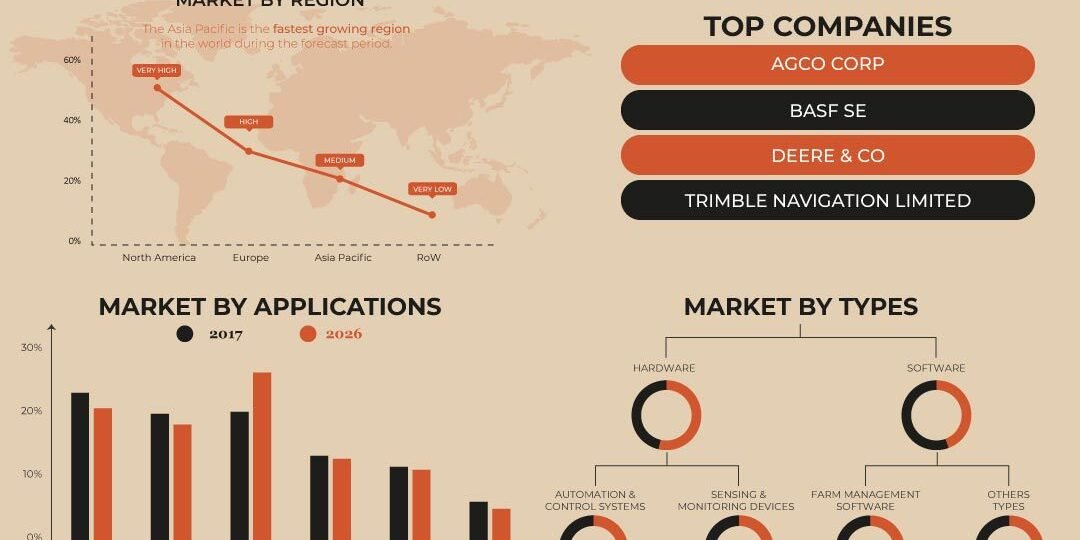
The global precision farming market is estimated to grow with approx. 7.9% CAGR during the year 2026–2032. The base year considered for the study is 2025 and the forecast period is 2026-2032. North America remains the largest regional market, accounting for roughly 36.6% of global revenue in 2025, while Asia Pacific is the fastest-growing region.
GLOBAL PRECISION FARMING MARKET FORECAST 2026
Global Precision Farming Market Is Segmented by Technology(Guidance System Technologies, Remote Sensing and Control Systems, Variable Rate Technology) by Type(Hardware, Software) by Applications(Soil Monitoring, Yield Monitoring, Software Applications, Variable Rate Applications, Field Mapping) & by Geography
A major driver in the global precision farming technologies market is the growing focus on sustainable agriculture and the need to develop crops that have stronger resistance to drought conditions and pests. One key aspect of precision farming involves understanding crop and soil patterns and deriving trends out of historical data. That analytical layer has matured considerably: cloud platforms now consolidate inputs from drones, in-field sensors, satellites, and weather stations into mobile dashboards, and AI models are increasingly used to convert multi-season historical yield and soil data into predictive prescriptions rather than retrospective reports.
Three further drivers define the current cycle. First, labour scarcity and wage inflation are pushing growers toward autonomy — GNSS auto-steering adoption has reached about 70% on farms over 1,000 hectares versus 52% on midsize holdings, and newer receivers such as John Deere’s StarFire 7000 lock onto more satellite bands for faster convergence. Second, input cost volatility, with recurring pressure on global fertiliser and fuel supply chains, is making variable-rate application a margin decision rather than an experimental one; documented efficiency gains of 15–30% on inputs underpin the business case. Third, sustainability and emissions reporting obligations are turning field-level data capture into a compliance requirement for growers supplying major food manufacturers, not merely an agronomic tool.

To learn more about this report, request a free sample copy
Consolidation has reshaped the supplier landscape materially since the previous edition. CNH Industrial absorbed Raven Industries in 2021, Kubota acquired AgJunction the same year, AGCO took an 85% stake in the PTx Trimble joint venture covering Trimble’s agriculture business in 2024, and Topcon was taken private in a KKR and JIC Capital management buyout completed in September 2025. Bayer, Corteva, and Nutrien now anchor the input-side digital platforms following the Monsanto, DowDuPont, and Agrium–PotashCorp transactions. In parallel, business models are shifting from capital purchase toward subscription — “Power as a Service” and “Data as a Service” arrangements let smaller operators pay only for the automation hours or analytics they use, lowering the entry threshold that has historically constrained adoption among smallholders.
The wide range of applications for guidance systems in precision agriculture is the main reason for its popularity. GNSS-based applications range from farm planning, field mapping, and soil sampling to tractor guidance and crop scouting. Guidance technologies, combined with other platforms, allow precise application of pesticides, herbicides, and fertilizers, reducing wastage while increasing efficiency. Adoption is now heavily skewed by farm size: auto-steering has reached roughly 70% penetration on holdings above 1,000 hectares versus 52% on midsize farms. Hardware continues to advance — John Deere’s StarFire 7000 receiver locks onto additional satellite bands for faster convergence, and the segment is moving beyond guidance toward full autonomy.
Guidance systems are among the oldest adopted precision farming technologies, which has made the segment a battleground for both incumbents and entrants, and it continues to see intense M&A. CNH Industrial completed its acquisition of Raven Industries in November 2021. Kubota acquired AgJunction in an all-cash deal valued at approximately CAD $91 million, closing the same year and folding its auto-steer and path-planning patents into Kubota’s autonomy roadmap. AGCO took an 85% stake in the PTx Trimble joint venture in April 2024, absorbing Trimble’s agriculture business. Topcon was taken private in September 2025 through a ¥348 billion management buyout backed by KKR and JIC Capital, freeing it to pursue longer-horizon positioning investments. On the venture side, Australia’s SwarmFarm Robotics closed a $30 million Series B for autonomous field robots.
High initial investment and implementation difficulty remain the principal restraints. GNSS-equipped machinery is costly, and returns concentrate on larger, fully integrated operations. Individual tools are cheaper, but stitching them into a cohesive management platform adds substantially to expense. Interpretation is equally challenging — every farm is unique, no universal prescription exists, and full implementation requires several seasons of accumulated data before it yields reliable prescriptions.
The Global Precision Farming Market segments include type, application, and technology.
Types are segmented into:
- Hardware
- Software
Applications are segmented into:
- Soil monitoring
- Yield monitoring
- Software applications
- Variable rate applications
- Field mapping
- Others
Technology is segmented into:
- Guidance systems
- Remote sensing and control systems
- Variable rate technology
Geographically, the Global Precision farming market has been segmented on the basis of four major regions, which include:
- Precision Farming North America Market– U.S., Canada, and Mexico
- Precision Farming Asia Pacific Market– China, India, Japan, Australia, New Zealand, RoAPAC
- Precision Farming Europe Market– UK, France, Germany, Italy, Spain, RoE
- Rest of World – Middle East and Africa
North America is anticipated to account for the largest market share during the forecast period. North America is one of the most advanced regions that has adopted farm mechanization and thus is the most attractive market for precision farming. Most of the farmers are wealthy, have large-sized farms, and use machine-intensive techniques for farming. They are highly professional and are willing to learn and adopt new farm technologies. Also, the high costs of labor relative to capital-intensive investment make labour-saving techniques particularly attractive. Many universities like the University Of Nebraska and the University of Minnesota offer courses for and are also involved in the research for precision farming. This is further expected to propel the market for precision agriculture. On the other hand, the Asia-Pacific is anticipated to be the fastest-growing region for the Global Precision farming market. Developing countries like India and China are the fastest growing precision farming markets in APAC. Many public and private partnership initiatives are working to strengthen the position of precision agriculture in India. Also, China has to adopt farm mechanization like precision farming to improve its productivity because of scarce agricultural sources, increasing pollution, and low utilizing efficiency. China has the advantage of an advanced IT infrastructure, and thus it will be easy for the country to adopt precision farming.
The Precision farming market is segmented on the basis of types which are sub-divided into hardware, software, and is also segmented on the basis of applications which are sub-divided into soil monitoring, yield monitoring, software applications, variable rate applications, field mapping and others. By technology, the precision farming market has been segmented into guidance systems, remote sensing and control systems, and variable rate technology.
The major market players in the Global Precision Farming Market are:
AGCO Corp
BASF SE
Bayer AG
CNH Industrial N.V.
Corteva Agriscience
Deere & Co
Kubota Corp
Topcon Corp
Trimble Inc
Growth Strategies of Key Players
These companies are pursuing both organic and inorganic strategies for growth, and acquisition activity in precision agriculture has accelerated sharply — fourteen M&A transactions were tracked in the segment during 2025 alone, spanning equipment OEMs, private equity, and food companies.
John Deere has been the most active acquirer, following a pattern that runs from Blue River Technology (2017) and Bear Flag Robotics (2021) through two deals in a single quarter of 2025. In May 2025 it acquired Sentera, a St. Paul, Minnesota developer of drone-mounted multispectral imaging and AI agronomic analysis, integrating Sentera’s FieldAgent imagery and SMARTSCRIPT Weeds prescription tools into the John Deere Operations Center. In August 2025 it followed with GUSS Automation, the California maker of semi-autonomous orchard and vineyard sprayers that use GPS, LiDAR, and proprietary navigation software — converting a 2022 joint venture into full ownership and pairing GUSS with Deere’s Smart Apply line. Each deal closed a specific gap in Deere’s autonomy stack rather than adding scale.
CNH Industrial ran a parallel strategy, acquiring Raven Industries in November 2021 and picking up Advanced Farm Technologies’ IP and assets in April 2025. Kubota acquired AgJunction in an all-cash transaction valued at approximately CAD $91 million, bringing auto-steering and path-planning patents in-house for its North American autonomy programme. AGCO took an 85% stake in the PTx Trimble joint venture in April 2024, absorbing Trimble’s agriculture business into its Precision Technology division.
BASF has built its digital position through sequential acquisition. After ZedX in 2017, it acquired the xarvio platform from Bayer in 2018 as part of a €1.7 billion divestment package tied to the Monsanto deal, then added Horta’s decision support system in 2022. In February 2025 it launched xarvio FIELD MANAGER for Fruits & Veggies, extending into wine and table grapes across France, Italy, Spain, and Türkiye for the 2025/26 season, with tomatoes and potatoes following from 2026.
Key Findings of the Global Precision Farming Market
- Focus on sustainable agriculture and the need to maximize food production is fueling growth in the global precision farming market, reinforced by mandatory emissions reporting and traceability demands from major food buyers.
- North America accounted for the largest revenue share in 2025, at roughly 36.6% of global revenue.
- Asia Pacific is the fastest-growing region, driven by China’s Digital Agriculture Strategy, India’s drone subsidy schemes, and Australia’s technological maturity.
- Guidance system technologies continue to dominate the market, with auto-steering penetration reaching approximately 70% on farms above 1,000 hectares versus 52% on midsize holdings.
- Hardware holds the largest component share, at over 60% of regional revenue in Asia Pacific, though software and services are growing faster.
- Increasing government support, including Australia’s $60 million On Farm Connectivity Program (2023–2027) subsidising 50–80% of farm technology costs, and China’s provincial drone subsidy programmes.
- Mergers and acquisitions — rather than product launches — are now the dominant growth strategy, with fourteen precision agriculture M&A transactions tracked in 2025 alone.
- Autonomy is the primary acquisition target, as OEMs buy to close specific gaps in perception, navigation, and agronomic intelligence rather than to add scale.
- Subscription models (“Power as a Service,” “Data as a Service”) are lowering the capital barrier that has historically limited smallholder adoption.
- Soil monitoring remains a major application segment, with demand for soil, moisture, and climate sensors growing at roughly 11.5% annually as growers shift toward precision irrigation and nutrient management.
- High initial investment and integration complexity remain the principal restraints, with returns concentrated on larger, fully integrated operations.
- RESEARCH SCOPE
- STUDY GOALS
- SCOPE OF THE MARKET STUDY
- WHO WILL FIND THIS REPORT USEFUL?
- STUDY AND FORECASTING YEARS
- RESEARCH METHODOLOGY
- SOURCES OF DATA
- SECONDARY DATA
- PRIMARY DATA
- TOP DOWN APPROACH
- BOTTOM-UP APPROACH
- DATA TRIANGULATION
- SOURCES OF DATA
- EXECUTIVE SUMMARY
- MARKET SUMMARY
- KEY FINDINGS
- INCREASED ADOPTION OF AUTO STEERING AND VARIABLE RATE CONTROLS
- INCREASED MERGERS AND ACQUISITIONS
- NORTH AMERICA DOMINATES THE GLOBAL PRECISION FARMING MARKET IN TERMS OF REVENUE
- ASIA PACIFIC IS THE MOST PROMISING REGIONAL MARKET
- MARKET DYNAMICS
- MARKET DEFINITION
- DRIVERS
- FOCUS ON SUSTAINABLE AGRICULTURE
- GROWING AWARENESS AND ACCEPTANCE
- NEED TO MAXIMIZE FOOD PRODUCTION
- OPTIMIZATION OF INPUTS
- CONTROL OVER FARM DATA
- RESTRAINTS
- HIGH INITIAL INVESTMENT
- IMPLEMENTATION ISSUES
- OPPORTUNITIES
- GROWING PROMINENCE OF TELEMATICS TECHNOLOGIES
- GROWING OPPORTUNITIES IN EMERGING ECONOMIES
- WIDE PORTFOLIO OF OFFERINGS
- CHALLENGES
- LACK OF STANDARDIZATION
- IMPACT OF FARM INCOME
- MARKET BY TECHNOLOGY
- GUIDANCE SYSTEM TECHNOLOGIES
- REMOTE SENSING AND CONTROL SYSTEMS
- VARIABLE RATE TECHNOLOGY
- MARKET BY TYPE
- HARDWARE
- AUTOMATION AND CONTROL SYSTEMS
- SENSING AND MONITORING DEVICES
- SOFTWARE
- FARM MANAGEMENT SOFTWARE
- HARDWARE
- MARKET BY APPLICATIONS
- SOIL MONITORING
- YIELD MONITORING
- SOFTWARE APPLICATIONS
- VARIABLE RATE APPLICATIONS
- FIELD MAPPING
- OTHERS
- KEY ANALYTICS
- PORTER’S 5 FORCE ANALYSIS
- THREAT OF NEW ENTRANTS
- THREAT OF SUBSTITUTE PRODUCTS
- BARGAINING POWER OF BUYERS
- BARGAINING POWER OF SUPPLIERS
- INTENSITY OF COMPETITIVE RIVALRY
- KEY BUYING CRITERIA
- INITIAL COST (IMPLEMENTATION COST)
- PAYBACK PERIOD
- EASE OF UNDERSTANDING
- FEATURE AVAILABILITY
- PORTFOLIO OF OFFERINGS
- TECHNOLOGICAL ADVANCEMENT
- INTEGRATION ABILITY
- KEY TRENDS
- INCREASING USE OF UAVS
- STRONG EXPECTED GROWTH OF WEATHER TRACKING AND FORECASTING
- VENDOR LANDSCAPE
- OPPORTUNITY MATRIX
- PORTER’S 5 FORCE ANALYSIS
- GEOGRAPHICAL ANALYSIS
- NORTH AMERICA
- US
- CANADA
- MEXICO
- EUROPE
- GERMANY
- FRANCE
- ITALY
- UK
- SPAIN
- REST OF EUROPE
- ASIA PACIFIC
- AUSTRALIA
- JAPAN
- NEW ZEALAND
- CHINA
- INDIA
- REST OF ASIA PACIFIC
- REST OF WORLD
- MIDDLE EAST
- AFRICA
- NORTH AMERICA
- COMPANY PROFILES
- AG LEADER TECHNOLOGY INC
- AGCO CORP
- AGDATA
- AGJUNCTION INC
- AG-NAV INC
- AGRIBOTIX
- AGRIUM INC
- BASF SE
- CROPX LTD
- DEERE & CO
- DUPONT
- FARMERS EDGE PRECISION CONSULTING INC
- MONSANTO COMPANY
- MTS SYSTEMS CORP
- NOZZLEWORKS INC
- RAVEN INDUSTRIES INC
- SST DEVELOPMENT GROUP INC
- TEEJET TECHNOLOGIES
- TOPCON CORP
- TRIMBLE NAVIGATION LIMITED
LIST OF TABLES
TABLE 1 GLOBAL PRECISION FARMING MARKET BY GEOGRAPHY 2018-2026 ($ MILLION)
TABLE 2 MERGERS AND ACQUISITIONS IN PRECISION FARMING MARKET IN US 2012-2015
TABLE 3 GLOBAL PRECISION FARMING MARKET BY TECHNOLOGY 2018-2026 ($ MILLION)
TABLE 4 GLOBAL GUIDANCE SYSTEM MARKET BY GEOGRAPHY 2018-2026 ($ MILLION)
TABLE 5 GLOBAL REMOTE SENSING AND CONTROL SYSTEMS MARKET BY GEOGRAPHY 2018-2026 ($ MILLION)
TABLE 6 GLOBAL VARIABLE RATE MARKET BY GEOGRAPHY 2018-2026 ($ MILLION)
TABLE 7 GLOBAL PRECISION FARMING MARKET BY TYPE 2018-2026 ($ MILLION)
TABLE 8 GLOBAL HARDWARE MARKET BY GEOGRAPHY 2018-2026 ($ MILLION)
TABLE 9 GLOBAL PRECISION FARMING TECHNOLOGIES MARKET BY TYPE 2018-2026 ($ MILLION)
TABLE 10 GLOBAL SOFTWARE MARKET BY GEOGRAPHY 2018-2026 ($ MILLION)
TABLE 11 GLOBAL SOFTWARE MARKET BY TYPES 2018-2026 ($ MILLION)
TABLE 12 GLOBAL PRECISION FARMING MARKET BY APPLICATION 2018-2026 ($ MILLION)
TABLE 13 GLOBAL SOIL MONITORING MARKET BY GEOGRAPHY 2018-2026 ($ MILLION)
TABLE 14 GLOBAL YIELD MONITORING MARKET BY GEOGRAPHY 2018-2026 ($ MILLION)
TABLE 15 GLOBAL SOFTWARE APPLICATIONS MARKET BY GEOGRAPHY 2018-2026 ($ MILLION)
TABLE 16 GLOBAL VARIABLE RATE APPLICATIONS MARKET BY GEOGRAPHY 2018-2026 ($ MILLION)
TABLE 17 GLOBAL FIELD MAPPING MARKET BY GEOGRAPHY 2018-2026 ($ MILLION)
TABLE 18 GLOBAL OTHERS MARKET BY GEOGRAPHY 2018-2026 ($ MILLION)
TABLE 19 KEY BUYING CRITERIA FOR PRECISION FARMING TECHNOLOGIES AND THEIR IMPACT
TABLE 20 CHANGED IMPORTANCE OF KEY BUYING CRITERIA OVERTIME IN ALL REGIONS
TABLE 21 GLOBAL PRECISION FARMING MARKET BY GEOGRAPHY 2018-2026 ($ MILLION)
TABLE 22 NORTH AMERICA PRECISION FARMING MARKET BY COUNTRY 2018-2026 ($ MILLION)
TABLE 23 EUROPE PRECISION FARMING MARKET BY COUNTRY 2018-2026 ($ MILLION)
TABLE 24 ASIA PACIFIC PRECISION FARMING MARKET BY COUNTRY 2018-2026 ($ MILLION)
TABLE 25 REST OF WORLD PRECISION FARMING MARKET 2018-2026 ($ MILLION)
LIST OF FIGURES
FIGURE 1 GLOBAL PRECISION FARMING MARKET BY TECHNOLOGY 2018-2026 ($ MILLION)
FIGURE 2 NORTH AMERICA PRECISION FARMING MARKET 2018-2026 ($ MILLION)
FIGURE 3 ARABLE LAND IN NORTH AMERICA 1961-2012 (HA PER PERSON)
FIGURE 4 ASIA PACIFIC PRECISION FARMING MARKET 2018-2026 ($ MILLION)
FIGURE 5 WORLD POPULATION (BILLIONS OF LIVES) VERSUS ARABLE LAND (HECTARE PER PERSON) 1950-2025
FIGURE 6 GLOBAL GUIDANCE SYSTEM MARKET 2018-2026 ($ MILLION)
FIGURE 7 GLOBAL REMOTE SENSING AND CONTROL SYSTEMS MARKET 2018-2026 ($ MILLION)
FIGURE 8 GLOBAL VARIABLE RATE MARKET 2018-2026 ($ MILLION)
FIGURE 9 GLOBAL HARDWARE MARKET 2018-2026 ($ MILLION)
FIGURE 10 GLOBAL AUTOMATION AND CONTROL SYSTEMS MARKET 2018-2026 ($ MILLION)
FIGURE 11 GLOBAL SENSING AND MONITORING DEVICES MARKET 2018-2026 ($ MILLION)
FIGURE 12 GLOBAL SOFTWARE MARKET 2018-2026 ($ MILLION)
FIGURE 13 GLOBAL FARM MANAGEMENT SOFTWARE MARKET 2018-2026 ($ MILLION)
FIGURE 14 GLOBAL SOIL MONITORING MARKET 2018-2026 ($ MILLION)
FIGURE 15 GLOBAL YIELD MONITORING MARKET 2018-2026 ($ MILLION)
FIGURE 16 GLOBAL SOFTWARE APPLICATIONS MARKET 2018-2026 ($ MILLION)
FIGURE 17 GLOBAL VARIABLE RATE APPLICATIONS MARKET 2018-2026 ($ MILLION)
FIGURE 18 GLOBAL FIELD MAPPING MARKET 2018-2026 ($ MILLION)
FIGURE 19 GLOBAL OTHERS MARKET 2018-2026 ($ MILLION)
FIGURE 20 UNITED STATES PRECISION FARMING MARKET 2018-2026 ($ MILLION)
FIGURE 21 CANADA PRECISION FARMING MARKET 2018-2026 ($ MILLION)
FIGURE 22 MEXICO PRECISION FARMING MARKET 2018-2026 ($ MILLION)
FIGURE 23 GERMANY PRECISION FARMING MARKET 2018-2026 ($ MILLION)
FIGURE 24 FRANCE PRECISION FARMING MARKET 2018-2026 ($ MILLION)
FIGURE 25 ITALY PRECISION FARMING MARKET 2018-2026 ($ MILLION)
FIGURE 26 UK PRECISION FARMING MARKET 2018-2026 ($ MILLION)
FIGURE 27 SPAIN PRECISION FARMING MARKET 2018-2026 ($ MILLION)
FIGURE 28 REST OF EUROPE PRECISION FARMING MARKET 2018-2026 ($ MILLION)
FIGURE 29 AUSTRALIA PRECISION FARMING MARKET 2018-2026 ($ MILLION)
FIGURE 30 JAPAN PRECISION FARMING MARKET 2018-2026 ($ MILLION)
FIGURE 31 NEW ZEALAND PRECISION FARMING MARKET 2018-2026 ($ MILLION)
FIGURE 32 CHINA PRECISION FARMING MARKET 2018-2026 ($ MILLION)
FIGURE 33 INDIA PRECISION FARMING MARKET 2018-2026 ($ MILLION)
FIGURE 34 REST OF ASIA PACIFIC PRECISION FARMING MARKET 2018-2026 ($ MILLION)
FIGURE 35 MIDDLE EAST PRECISION FARMING MARKET 2018-2026 ($ MILLION)
FIGURE 36 AFRICA PRECISION FARMING MARKET 2018-2026 ($ MILLION)
- MARKET BY TECHNOLOGY
- GUIDANCE SYSTEM TECHNOLOGIES
- REMOTE SENSING AND CONTROL SYSTEMS
- VARIABLE RATE TECHNOLOGY
- MARKET BY TYPE
- HARDWARE
- AUTOMATION AND CONTROL SYSTEMS
- SENSING AND MONITORING DEVICES
- SOFTWARE
- FARM MANAGEMENT SOFTWARE
- HARDWARE
- MARKET BY APPLICATIONS
- SOIL MONITORING
- YIELD MONITORING
- SOFTWARE APPLICATIONS
- VARIABLE RATE APPLICATIONS
- FIELD MAPPING
- OTHERS
- GEOGRAPHICAL ANALYSIS
- NORTH AMERICA
- US
- CANADA
- MEXICO
- EUROPE
- GERMANY
- FRANCE
- ITALY
- UK
- SPAIN
- REST OF EUROPE
- ASIA PACIFIC
- AUSTRALIA
- JAPAN
- NEW ZEALAND
- CHINA
- INDIA
- REST OF ASIA PACIFIC
- REST OF WORLD
- MIDDLE EAST
- AFRICA
- NORTH AMERICA