Global Air Quality IoT Sensors Market by Product Type (Fixed Air Quality Monitors, Portable Air Quality Monitors, Wearable Air Quality Monitors, Indoor Air Quality Monitors, Outdoor Air Quality Monitors), Market by Measurement Parameter (Particulate Matter (PM2.5, PM10), Volatile Organic Compounds (VOCs), Carbon Dioxide (CO2), Nitrogen Dioxide (NO2), Ozone (O3)), Market by Connectivity Technology (Wi-Fi, Bluetooth, LoRaWAN, Cellular, Zigbee), Market by Deployment Type (On-Premises, Cloud-Based), and Market by End Use Sector (Residential, Commercial, Industrial, Agriculture, Government, Public Institutions), by Geography
GLOBAL AIR QUALITY IOT SENSORS MARKET OVERVIEW
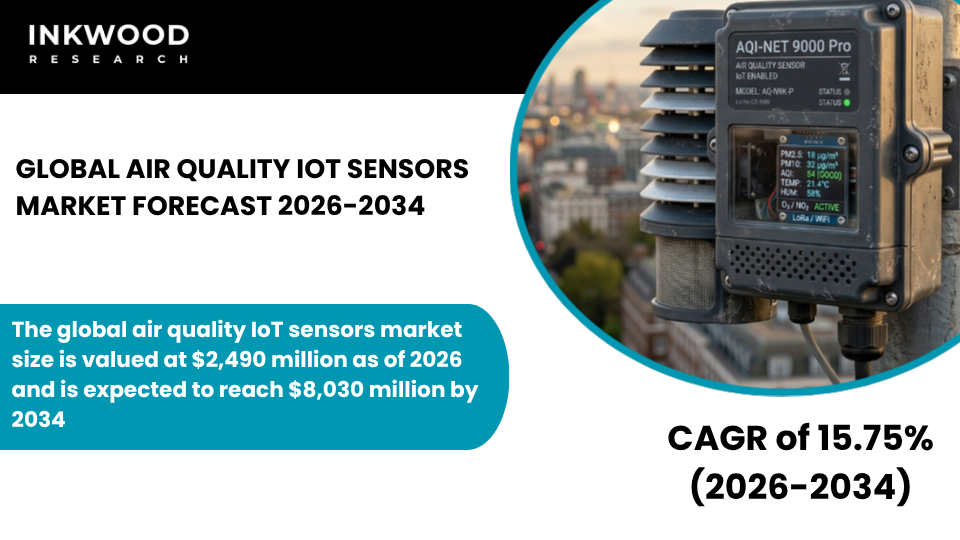
The global air quality IoT sensors market size is valued at $2,490 million as of 2026 and is expected to reach $8,030 million by 2034, growing at a CAGR of 15.75% during the forecast period 2026–2034. The base year considered for the study is 2025, and the forecast period is between 2026 and 2034. The market study has also analyzed the crisis impact on the air quality IoT sensors market qualitatively as well as quantitatively.
The air quality IoT sensors market encompasses the global ecosystem of connected sensing devices that detect, measure, and transmit data on airborne pollutants and environmental conditions in real time. These IoT-enabled devices monitor a broad range of contaminants, including particulate matter (PM2.5 and PM10), volatile organic compounds (VOCs), carbon dioxide (CO2), nitrogen dioxide (NO2), and ozone (O3), across environments ranging from homes and workplaces to industrial facilities and open urban spaces.
Understanding how IoT sensors monitor air quality is central to appreciating the market’s value: unlike traditional instruments, these sensors connect seamlessly to cloud platforms, mobile applications, and AI-powered analytics engines, enabling continuous automated surveillance without manual intervention. The types of air quality sensors available today span low-cost consumer-grade devices, ruggedized industrial monitors, and large-scale smart city sensor networks, making the air quality monitoring sensors market one of the broadest and fastest-evolving segments within the IoT environmental sensors market.
Moreover, the growing convergence of sensor miniaturization, wireless connectivity, real-time data analytics, and pollution control technologies is fundamentally redefining how governments, enterprises, and individuals understand and respond to air pollution. As both indoor vs outdoor air quality monitoring needs continue to expand, the role of IoT air pollution monitoring systems has never been more strategically important.
To Know More About This Report, Request a Free Sample Copy
GROWTH ENABLERS
Key enablers of the global air quality IoT sensors market growth:
- Increasing prevalence of air pollution-related diseases is driving demand for continuous air quality monitoring solutions
- Rapid urbanization and industrialization are generating a strong need for environmental surveillance systems
- Growth in smart homes and connected devices ecosystem is boosting adoption of IoT-based air quality sensors
- Stringent government regulations on emissions and air quality standards are encouraging sensor deployment
- Government regulations on air pollution monitoring are among the most powerful structural drivers of the air quality IoT sensors market. In the United States, the Environmental Protection Agency (EPA) revised its National Ambient Air Quality Standards (NAAQS) for PM2.5 in 2024, lowering the annual standard from 12 µg/m³ to 9 µg/m³, a threshold that significantly expands compliance obligations for state and local agencies.
- Similarly, the European Union’s revised Ambient Air Quality Directive, adopted in 2024, requires member states to substantially expand their environmental compliance monitoring systems and align air quality benchmarks closer to WHO guidelines. These regulatory mandates carry real enforcement weight, including financial penalties and mandatory public reporting.
- As a result, industrial operators, municipal governments, and commercial building managers are accelerating investments in real-time air quality monitoring IoT solutions and IoT environmental sensors to ensure compliance. This regulatory momentum is sustaining long-term IoT environmental sensors market growth across every major geography.
Key growth restraining factors of the global air quality IoT sensors market:
- Data accuracy and calibration challenges in low-cost sensors limit their reliability in critical applications
- High initial deployment costs for advanced monitoring networks restrain adoption among small enterprises
- Lack of standardization in air quality data and sensor performance creates interoperability issues
- Privacy and data security concerns associated with connected devices hinder market growth
- As IoT-enabled devices become more deeply embedded in homes, public infrastructure, and industrial environments, data privacy and cybersecurity risks are emerging as a meaningful constraint on the air quality IoT sensors market.
- These devices continuously collect and transmit sensitive environmental and location data, making them potential targets for unauthorized access. The absence of unified security protocols across sensor manufacturers further compounds this vulnerability. According to the European Union Agency for Cybersecurity (ENISA), IoT devices remain among the most frequently targeted categories in cyberattack incidents.
- For enterprise and government buyers evaluating large-scale air pollution monitoring devices market report recommendations, this creates significant procurement hesitation, particularly in sensitive environments such as hospitals, schools, and critical industrial zones. Until robust, standardized security frameworks are widely adopted across the IoT air quality monitoring market, data security concerns will continue to temper adoption in privacy-sensitive applications.
KEY MARKET TRENDS
Global Air Quality IoT Sensors Industry | Top Trends
- Portable air quality sensors demand is surging as consumers increasingly seek personal, real-time insights into their pollution exposure. Wearable and handheld devices now allow individuals to track PM2.5, VOC, and CO2 levels as they move through varying environments, from busy commutes to indoor office spaces. This trend is reshaping the air quality monitoring sensors market by extending demand well beyond regulatory and industrial applications into everyday consumer use.
- One of the most commercially significant smart air quality sensors market trends is the deepening integration of IoT air quality monitoring technology with HVAC systems in commercial and residential buildings. Smart buildings are increasingly using real-time data from indoor air quality monitoring systems to dynamically adjust ventilation rates, filter activation, and fresh air intake, all automatically. This approach improves occupant health and productivity while simultaneously reducing unnecessary energy consumption. It also supports green building certifications such as LEED and WELL, making cloud-connected air quality monitoring systems increasingly attractive to commercial real estate operators.
- The fusion of edge computing with real-time IoT monitoring platforms is transforming air quality data processing. Rather than routing raw sensor outputs to centralized cloud servers, edge-enabled AI-based environmental sensors perform local computation directly at the point of measurement. This capability dramatically reduces response latency, which is critical in industrial emission monitoring sensors applications where rapid detection of hazardous pollutants can prevent workplace accidents or regulatory breaches.
- Urban governments worldwide are deploying large-scale smart city air quality monitoring systems to capture granular, neighborhood-level pollution data that traditional reference stations cannot deliver. These smart city air quality initiatives combine fixed outdoor sensors, mobile monitoring units on public transit vehicles, and citizen science data platforms into integrated sensor networks. Cities such as London, Seoul, and Singapore have already built extensive IoT-based sensor networks as part of their smart city infrastructure. This trend is broadening the outdoor air quality monitoring market significantly, while also driving demand for environmental IoT sensors for pollution control and urban air pollution management at scale. According to the World Health Organization (WHO), approximately 99% of the global population breathes air exceeding WHO air quality guidelines, a sobering statistic that underscores the urgency and long-term scale of investment flowing into the smart city air quality monitoring systems market.
MARKET SEGMENTATION
Market Segmentation – Product Type, Measurement Parameter, Connectivity Technology, Deployment Type, and End Use Sector –
Market by Product Type:
- Fixed Air Quality Monitors
- Fixed air quality monitors are stationary sensing units designed for continuous, long-term deployment at specific, high-priority locations. They are typically installed on building facades, utility poles, rooftops, industrial perimeters, and government monitoring stations. These devices deliver high measurement stability and sustained uptime, making them the preferred choice for regulatory compliance and urban pollution surveillance within the air quality monitoring sensors market.
- Unlike portable alternatives, fixed monitors support simultaneous multi-parameter measurement, tracking PM2.5, PM10, NO2, O3, CO2, and VOCs, through electrochemical, optical, or metal oxide sensing technologies. Their integration with hardwired power supplies and ruggedized enclosures allows reliable operation across extreme weather conditions.
- Demand for fixed monitors is being driven strongly by government mandates requiring expanded national air quality monitoring networks. In the United States, the EPA’s Air Quality System (AQS) supports thousands of fixed monitoring stations, and NAAQS revisions are prompting further network expansion at the state and local level. Across Asia-Pacific and Europe, smart city air quality initiatives are funding dense urban sensor networks where fixed monitors serve as anchor nodes for broader environmental monitoring systems.
- Portable Air Quality Monitors
- Wearable Air Quality Monitors
- Indoor Air Quality Monitors
- Outdoor Air Quality Monitors
Market by Measurement Parameter:
- Particulate Matter (PM2.5, PM10)
- Volatile Organic Compounds (VOCs)
- Carbon Dioxide (CO2)
- Nitrogen Dioxide (NO2)
- Ozone (O3)
Market by Connectivity Technology:
- Wi-Fi
- Bluetooth
- LoRaWAN
- Cellular
- Zigbee
Market by Deployment Type:
- On-Premises
- Cloud-Based
Market by End Use Sector:
- Residential
- Commercial
- Industrial
- Agriculture
- Government
- Public Institutions
Geographical Study based on Four Major Regions:
- North America: The United States and Canada
- The North America air quality IoT sensors market size is valued at $873.65 million as of 2026 and is expected to reach $2,580.11 million by 2034, growing at a CAGR of 14.50% during the forecast period 2026–2034.
- North America holds a commanding position in the global air quality IoT sensors market, underpinned by robust regulatory infrastructure, high smart home adoption, and sustained government investment in environmental monitoring systems.
- In the United States, the EPA’s tightened PM2.5 annual standard, revised in 2024, is compelling state and local agencies to rapidly expand their air quality detection sensors networks.
- Meanwhile, Canada’s National Ambient Air Quality Objectives (NAAQOs), administered by Environment and Climate Change Canada, are motivating the real-time IoT environmental sensors deployment across major urban centers.
- The commercial sector is also a significant growth engine: building operators pursuing WELL certification and sustainability technologies adoption are creating strong recurring demand for smart air quality sensors in offices, retail spaces, and healthcare facilities.
- These forces together position North America as one of the most mature and strategically important regions within the broader IoT air quality monitoring market, with the indoor air quality sensors market and the outdoor air quality monitoring market both expanding simultaneously.
- Europe: The United Kingdom, Germany, France, Italy, Spain, Poland, Belgium, and Rest of Europe
- The Europe air quality IoT sensors market size is valued at $638.11 million as of 2026 and is expected to reach $2,034.78 million by 2034, growing at a CAGR of 15.60% during the forecast period 2026–2034.
- Europe is advancing rapidly in the air quality monitoring sensors market, supported by the EU’s revised Ambient Air Quality Directive of 2024, which mandates substantially expanded environmental compliance monitoring systems across all member states.
- The United Kingdom continues to invest in its Automatic Urban and Rural Network (AURN), the country’s largest air quality monitoring infrastructure, while simultaneously funding smart city air quality monitoring IoT sensor pilots across London, Birmingham, and Manchester.
- Germany, as Europe’s industrial powerhouse, faces significant pressure to monitor industrial emissions under the Federal Immission Control Act (BImSchG), sustaining strong demand for both fixed outdoor air quality monitoring market solutions and industrial air quality sensors market analysis-informed deployments across its manufacturing corridors.
- Both the UK and Germany reflect the broader European imperative to align national air quality standards with WHO guidelines by 2030, creating a decade-long structural tailwind for the air quality IoT sensors market across the region.
- Asia-Pacific: China, India, Japan, Australia & New Zealand, South Korea, Thailand, Indonesia, Vietnam, Singapore, and Rest of Asia-Pacific
- The Asia-Pacific air quality IoT sensors market size is valued at $703.92 million as of 2026 and is expected to reach $2,588.34 million by 2034, growing at a CAGR of 17.68% during the forecast period 2026–2034.
- Asia-Pacific is the fastest-growing region within the global air quality IoT sensors market, driven by severe urban air pollution, large-scale smart city infrastructure investments, and rapidly expanding industrial activity.
- China, through its Ministry of Ecology and Environment (MEE), operates one of the world’s most extensive national air quality monitoring networks and has been aggressively expanding its low-cost air quality IoT sensors adoption as part of its broader ecological civilization strategy.
- Japan, meanwhile, is channeling investment into AI-powered air quality monitoring systems and edge-computing sensor nodes under its Society 5.0 framework, targeting hyperlocal pollution mapping across both urban and industrial zones.
- The region’s combination of regulatory urgency, government funding, climate monitoring solutions adoption, and a rapidly growing health-conscious middle class makes Asia-Pacific the most dynamic and high-growth frontier for the IoT air quality monitoring market, as well as the most critical geography for global air quality IoT sensors market size and forecast projections through 2034.
- Rest of World: Latin America, the Middle East & Africa
Our market research reports offer an in-depth analysis of individual country-level market size and growth statistics. We cover the segmentation analysis, key growth factors, and macro-economic trends within the air quality IoT sensors market, providing detailed insights into —
MAJOR PLAYERS
The major players in the global air quality IoT sensors market are:
- Sensirion AG
- Bosch Sensortec GmbH
- Honeywell International Inc
- Siemens AG
- Aeroqual Ltd
Key strategies adopted by some of these companies:
- Sensirion AG launched the SEN66 multi-parameter environmental sensor node, combining PM2.5, PM10, VOC, NOx, CO2, humidity, and temperature sensing within a single compact module. This development is strategically significant for the air quality IoT sensors market because it allows device manufacturers to build highly capable smart air quality sensors with a dramatically smaller hardware footprint, reducing both device cost and time to market for OEM partners worldwide.
- Honeywell expanded its Honeywell Forge Environmental Intelligence platform to include enhanced indoor air quality monitoring capabilities for commercial buildings, integrating real-time sensor data directly with HVAC control systems. This move strengthens Honeywell’s positioning in the indoor air quality sensors market and supports accelerating demand for cloud-connected air quality monitoring systems in commercial real estate, where occupant wellness and energy efficiency are increasingly linked priorities.
- Airthings entered into strategic partnerships with leading building management system providers to integrate its Wave series of indoor air quality IoT sensors with commercial BMS platforms, enabling fully automated, data-driven ventilation control. This collaboration accelerates the adoption of real-time air quality monitoring IoT solutions in commercial buildings and reinforces the role of IoT air quality platforms market outlook as a key growth segment within the broader environmental monitoring sensors market analysis.
REPORT SYNOPSIS
| REPORT SCOPE | DETAILS |
|---|---|
| Market Forecast Years | 2026-2034 |
| Base Year | 2025 |
| Market Historical Years | 2022-2024 |
| Forecast Units | Revenue ($ Million) |
| Segments Analyzed | Product Type, Measurement Parameter, Connectivity Technology, Deployment Type, End Use Sector |
| Geographies Analyzed | North America, Europe, Asia-Pacific, Rest of World |
| Companies Analyzed | Sensirion AG, Bosch Sensortec GmbH, Honeywell International Inc, Siemens AG, Aeroqual Ltd, Airthings AS, Figaro Engineering Inc, Alphasense Ltd, TSI Incorporated |
TABLE OF CONTENTS
RESEARCH SCOPE & METHODOLOGY
- STUDY OBJECTIVES
- METHODOLOGY
- ASSUMPTIONS & LIMITATIONS
EXECUTIVE SUMMARY & KEY INSIGHTS
- MARKET SIZE, SHARE & ESTIMATES
- MARKET OVERVIEW
- SCOPE OF STUDY
- MAJOR MARKET FINDINGS
- RISING URBAN POLLUTION LEVELS AND HEALTH AWARENESS ARE ACCELERATING ADOPTION OF AIR QUALITY IOT SENSORS ACROSS RESIDENTIAL AND COMMERCIAL SEGMENTS
- GOVERNMENT-LED SMART CITY AND ENVIRONMENTAL MONITORING INITIATIVES ARE SIGNIFICANTLY DRIVING LARGE-SCALE DEPLOYMENTS GLOBALLY
- INTEGRATION WITH AI AND CLOUD ANALYTICS IS ENABLING REAL-TIME AIR QUALITY INSIGHTS AND PREDICTIVE MONITORING CAPABILITIES
- LOW-COST SENSOR INNOVATIONS ARE EXPANDING MARKET ACCESSIBILITY IN DEVELOPING ECONOMIES
MARKET DYNAMICS
- KEY DRIVERS
- INCREASING PREVALENCE OF AIR POLLUTION-RELATED DISEASES IS DRIVING DEMAND FOR CONTINUOUS AIR QUALITY MONITORING SOLUTIONS
- RAPID URBANIZATION AND INDUSTRIALIZATION ARE GENERATING A STRONG NEED FOR ENVIRONMENTAL SURVEILLANCE SYSTEMS
- GROWTH IN SMART HOMES AND CONNECTED DEVICES ECOSYSTEM IS BOOSTING ADOPTION OF IOT-BASED AIR QUALITY SENSORS
- STRINGENT GOVERNMENT REGULATIONS ON EMISSIONS AND AIR QUALITY STANDARDS ARE ENCOURAGING SENSOR DEPLOYMENT
- KEY RESTRAINTS
- DATA ACCURACY AND CALIBRATION CHALLENGES IN LOW-COST SENSORS LIMIT THEIR RELIABILITY IN CRITICAL APPLICATIONS
- HIGH INITIAL DEPLOYMENT COSTS FOR ADVANCED MONITORING NETWORKS RESTRAIN ADOPTION AMONG SMALL ENTERPRISES
- LACK OF STANDARDIZATION IN AIR QUALITY DATA AND SENSOR PERFORMANCE CREATES INTEROPERABILITY ISSUES
- PRIVACY AND DATA SECURITY CONCERNS ASSOCIATED WITH CONNECTED DEVICES HINDER MARKET GROWTH
- KEY DRIVERS
STRATEGIC MARKET ANALYTICS
- GROWTH METRICS
- TAM, SAM & SOM OPPORTUNITY ANALYSIS
- EMERGING MARKET TRENDS & PARADIGM SHIFTS
- INCREASING ADOPTION OF PORTABLE AND WEARABLE AIR QUALITY MONITORING DEVICES AMONG CONSUMERS
- GROWING INTEGRATION OF AIR QUALITY SENSORS WITH HVAC SYSTEMS FOR SMART INDOOR AIR MANAGEMENT
- RISING USE OF EDGE COMPUTING TO ENABLE REAL-TIME DATA PROCESSING AND REDUCE LATENCY
- EXPANSION OF SENSOR NETWORKS IN SMART CITIES FOR HYPERLOCAL AIR QUALITY MONITORING
- PORTER’S FIVE FORCES ANALYSIS
- BUYERS POWER
- SUPPLIERS POWER
- SUBSTITUTION
- NEW ENTRANTS
- INDUSTRY RIVALRY
- PESTLE ANALYSIS
- POLITICAL
- ECONOMIC
- SOCIAL LANDSCAPE
- TECHNOLOGY
- LEGAL
- ENVIRONMENTAL
- GROWTH OPPORTUNITY MAPPING & HEATMAP
- GROWTH PROSPECT MAPPING FOR NORTH AMERICA
- GROWTH PROSPECT MAPPING FOR EUROPE
- GROWTH MAPPING PROSPECT FOR ASIA-PACIFIC
- GROWTH MAPPING PROSPECT FOR REST OF WORLD
- MARKET MATURITY & LIFECYCLE ANALYSIS
- MARKET CONCENTRATION ANALYSIS
- GROWTH METRICS
AIR QUALITY IOT SENSORS VALUE CHAIN & DECISION FRAMEWORK
- VALUE CHAIN ANALYSIS
- RAW MATERIAL SUPPLIERS
- SENSOR MANUFACTURING
- HARDWARE INTEGRATION
- SOFTWARE DEVELOPMENT
- CLOUD PLATFORM PROVIDERS
- DISTRIBUTION CHANNELS
- END-USER APPLICATIONS
- KEY BUYING CRITERIA
- DATA ACCURACY
- COST EFFICIENCY
- CONNECTIVITY OPTIONS
- DEVICE DURABILITY
- PRICING MODELS, SUBSCRIPTION STRUCTURES & DATA MONETIZATION STRATEGIES
- REGULATORY & POLICY LANDSCAPE ANALYSIS
- VALUE CHAIN ANALYSIS
AIR QUALITY IOT SENSORS MARKET BY PRODUCT TYPE
- FIXED AIR QUALITY MONITORS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PORTABLE AIR QUALITY MONITORS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- WEARABLE AIR QUALITY MONITORS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- INDOOR AIR QUALITY MONITORS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OUTDOOR AIR QUALITY MONITORS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- FIXED AIR QUALITY MONITORS
AIR QUALITY IOT SENSORS MARKET BY MEASUREMENT PARAMETER
- PARTICULATE MATTER (PM2.5, PM10)
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- VOLATILE ORGANIC COMPOUNDS (VOCS)
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- CARBON DIOXIDE (CO2)
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- NITROGEN DIOXIDE (NO2)
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- OZONE (O3)
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PARTICULATE MATTER (PM2.5, PM10)
AIR QUALITY IOT SENSORS MARKET BY CONNECTIVITY TECHNOLOGY
- WI-FI
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- BLUETOOTH
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- LORAWAN
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- CELLULAR
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ZIGBEE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- WI-FI
AIR QUALITY IOT SENSORS MARKET BY DEPLOYMENT TYPE
- ON-PREMISES
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- CLOUD-BASED
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- ON-PREMISES
AIR QUALITY IOT SENSORS MARKET BY END USE SECTOR
- RESIDENTIAL
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- COMMERCIAL
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- INDUSTRIAL
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- AGRICULTURE
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- GOVERNMENT
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- PUBLIC INSTITUTIONS
- MARKET SIZE, FORECAST & SHARE (2022–2034)
- RESIDENTIAL
GEOGRAPHICAL ANALYSIS
- NORTH AMERICA
- MARKET SIZE & ESTIMATES
- NORTH AMERICA AIR QUALITY IOT SENSORS MARKET DRIVERS
- NORTH AMERICA AIR QUALITY IOT SENSORS MARKET CHALLENGES
- KEY REGIONAL PLAYERS & ECOSYSTEM
- COUNTRY ANALYSIS
- UNITED STATES
- UNITED STATES AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- CANADA
- CANADA AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- UNITED STATES
- EUROPE
- MARKET SIZE & ESTIMATES
- EUROPE AIR QUALITY IOT SENSORS MARKET DRIVERS
- EUROPE AIR QUALITY IOT SENSORS MARKET CHALLENGES
- KEY REGIONAL PLAYERS & ECOSYSTEM
- COUNTRY ANALYSIS
- UNITED KINGDOM
- UNITED KINGDOM AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- GERMANY
- GERMANY AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- FRANCE
- FRANCE AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- ITALY
- ITALY AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- SPAIN
- SPAIN AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- BELGIUM
- BELGIUM AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- POLAND
- POLAND AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- REST OF EUROPE
- REST OF EUROPE AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- UNITED KINGDOM
- ASIA-PACIFIC
- MARKET ESTIMATES & SIZES
- ASIA-PACIFIC AIR QUALITY IOT SENSORS MARKET DRIVERS
- ASIA-PACIFIC AIR QUALITY IOT SENSORS MARKET CHALLENGES
- KEY REGIONAL PLAYERS & ECOSYSTEM
- COUNTRY ANALYSIS
- CHINA
- CHINA AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- JAPAN
- JAPAN AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- AUSTRALIA & NEW ZEALAND
- AUSTRALIA & NEW ZEALAND AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- INDIA
- INDIA AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- SOUTH KOREA
- SOUTH KOREA AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- INDONESIA
- INDONESIA AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- THAILAND
- THAILAND AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- VIETNAM
- VIETNAM AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- SINGAPORE
- SINGAPORE AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- REST OF ASIA-PACIFIC
- REST OF ASIA-PACIFIC AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- CHINA
- REST OF WORLD
- MARKET ESTIMATES & SIZES
- REST OF WORLD AIR QUALITY IOT SENSORS MARKET DRIVERS
- REST OF WORLD AIR QUALITY IOT SENSORS MARKET CHALLENGES
- KEY REGIONAL PLAYERS & ECOSYSTEM
- REGIONAL ANALYSIS
- LATIN AMERICA
- LATIN AMERICA AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- MIDDLE EAST & AFRICA
- MIDDLE EAST & AFRICA AIR QUALITY IOT SENSORS MARKET SIZE & OPPORTUNITIES
- LATIN AMERICA
- NORTH AMERICA
COMPETITIVE LANDSCAPE
- KEY STRATEGIC DEVELOPMENTS
- MERGERS & ACQUISITIONS
- PRODUCT LAUNCHES & DEVELOPMENTS
- PARTNERSHIPS & AGREEMENTS
- BUSINESS EXPANSIONS & DIVESTITURES
- COMPETITOR POSITIONING & DIFFERENTIATION MAP
- COMPANY PROFILES
- SENSIRION AG
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- BOSCH SENSORTEC GMBH
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- HONEYWELL INTERNATIONAL INC
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- SIEMENS AG
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- AEROQUAL LTD
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- AIRTHINGS AS
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- FIGARO ENGINEERING INC
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- ALPHASENSE LTD
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- TSI INCORPORATED
- COMPANY OVERVIEW
- PRODUCT LIST
- STRENGTHS & CHALLENGES
- SENSIRION AG
- KEY STRATEGIC DEVELOPMENTS
LIST OF TABLES
TABLE 1: MARKET SNAPSHOT – AIR QUALITY IOT SENSORS MARKET
TABLE 2: PRICING MODELS, SUBSCRIPTION STRUCTURES & DATA MONETIZATION STRATEGIES
TABLE 3: REGULATORY & POLICY LANDSCAPE ANALYSIS
TABLE 4: MARKET BY PRODUCT TYPE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 5: MARKET BY PRODUCT TYPE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 6: FIXED AIR QUALITY MONITORS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 7: FIXED AIR QUALITY MONITORS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 8: PORTABLE AIR QUALITY MONITORS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 9: PORTABLE AIR QUALITY MONITORS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 10: WEARABLE AIR QUALITY MONITORS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 11: WEARABLE AIR QUALITY MONITORS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 12: INDOOR AIR QUALITY MONITORS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 13: INDOOR AIR QUALITY MONITORS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 14: OUTDOOR AIR QUALITY MONITORS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 15: OUTDOOR AIR QUALITY MONITORS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 16: MARKET BY MEASUREMENT PARAMETER, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 17: MARKET BY MEASUREMENT PARAMETER, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 18: PARTICULATE MATTER (PM2.5, PM10) MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 19: PARTICULATE MATTER (PM2.5, PM10) MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 20: VOLATILE ORGANIC COMPOUNDS (VOCS) MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 21: VOLATILE ORGANIC COMPOUNDS (VOCS) MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 22: CARBON DIOXIDE (CO2) MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 23: CARBON DIOXIDE (CO2) MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 24: NITROGEN DIOXIDE (NO2) MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 25: NITROGEN DIOXIDE (NO2) MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 26: OZONE (O3) MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 27: OZONE (O3) MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 28: MARKET BY CONNECTIVITY TECHNOLOGY, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 29: MARKET BY CONNECTIVITY TECHNOLOGY, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 30: WI-FI MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 31: WI-FI MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 32: BLUETOOTH MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 33: BLUETOOTH MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 34: LORAWAN MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 35: LORAWAN MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 36: CELLULAR MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 37: CELLULAR MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 38: ZIGBEE MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 39: ZIGBEE MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 40: MARKET BY DEPLOYMENT TYPE, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 41: MARKET BY DEPLOYMENT TYPE, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 42: ON-PREMISES MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 43: ON-PREMISES MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 44: CLOUD-BASED MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 45: CLOUD-BASED MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 46: MARKET BY END USE SECTOR, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 47: MARKET BY END USE SECTOR, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 48: RESIDENTIAL MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 49: RESIDENTIAL MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 50: COMMERCIAL MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 51: COMMERCIAL MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 52: INDUSTRIAL MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 53: INDUSTRIAL MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 54: AGRICULTURE MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 55: AGRICULTURE MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 56: GOVERNMENT MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 57: GOVERNMENT MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 58: PUBLIC INSTITUTIONS MARKET, BY REGION, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 59: PUBLIC INSTITUTIONS MARKET, BY REGION, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 60: MARKET BY GEOGRAPHICAL ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 61: MARKET BY GEOGRAPHICAL ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 62: NORTH AMERICA MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 63: NORTH AMERICA MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 64: KEY PLAYERS OPERATING IN THE NORTH AMERICAN MARKET
TABLE 65: EUROPE MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 66: EUROPE MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 67: KEY PLAYERS OPERATING IN THE EUROPEAN MARKET
TABLE 68: ASIA-PACIFIC MARKET, COUNTRY ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 69: ASIA-PACIFIC MARKET, COUNTRY ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 70: KEY PLAYERS OPERATING IN THE ASIA-PACIFIC MARKET
TABLE 71: REST OF WORLD MARKET, REGIONAL ANALYSIS, HISTORICAL YEARS, 2022-2024 (IN $ MILLION)
TABLE 72: REST OF WORLD MARKET, REGIONAL ANALYSIS, FORECAST YEARS, 2026-2034 (IN $ MILLION)
TABLE 73: KEY PLAYERS OPERATING IN THE REST OF WORLD MARKET
TABLE 74: LIST OF MERGERS & ACQUISITIONS
TABLE 75: LIST OF PRODUCT LAUNCHES & DEVELOPMENTS
TABLE 76: LIST OF PARTNERSHIPS & AGREEMENTS
TABLE 77: LIST OF BUSINESS EXPANSIONS & DIVESTITURES
LIST OF FIGURES
FIGURE 1: MAJOR MARKET FINDINGS
FIGURE 2: MARKET DYNAMICS
FIGURE 3: KEY MARKET TRENDS
FIGURE 4: PORTER’S FIVE FORCES ANALYSIS
FIGURE 5: GROWTH PROSPECT MAPPING FOR NORTH AMERICA
FIGURE 6: GROWTH PROSPECT MAPPING FOR EUROPE
FIGURE 7: GROWTH PROSPECT MAPPING FOR ASIA-PACIFIC
FIGURE 8: GROWTH PROSPECT MAPPING FOR REST OF WORLD
FIGURE 9: MARKET MATURITY ANALYSIS
FIGURE 10: MARKET CONCENTRATION ANALYSIS
FIGURE 11: VALUE CHAIN ANALYSIS
FIGURE 12: KEY BUYING CRITERIA
FIGURE 13: SEGMENT GROWTH POTENTIAL, BY PRODUCT TYPE, IN 2025
FIGURE 14: FIXED AIR QUALITY MONITORS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 15: PORTABLE AIR QUALITY MONITORS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 16: WEARABLE AIR QUALITY MONITORS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 17: INDOOR AIR QUALITY MONITORS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 18: OUTDOOR AIR QUALITY MONITORS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 19: SEGMENT GROWTH POTENTIAL, BY MEASUREMENT PARAMETER, IN 2025
FIGURE 20: PARTICULATE MATTER (PM2.5, PM10) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 21: VOLATILE ORGANIC COMPOUNDS (VOCS) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 22: CARBON DIOXIDE (CO2) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 23: NITROGEN DIOXIDE (NO2) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 24: OZONE (O3) MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 25: SEGMENT GROWTH POTENTIAL, BY CONNECTIVITY TECHNOLOGY, IN 2025
FIGURE 26: WI-FI MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 27: BLUETOOTH MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 28: LORAWAN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 29: CELLULAR MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 30: ZIGBEE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 31: SEGMENT GROWTH POTENTIAL, BY DEPLOYMENT TYPE, IN 2025
FIGURE 32: ON-PREMISES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 33: CLOUD-BASED MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 34: SEGMENT GROWTH POTENTIAL, BY END USE SECTOR, IN 2025
FIGURE 35: RESIDENTIAL MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 36: COMMERCIAL MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 37: INDUSTRIAL MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 38: AGRICULTURE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 39: GOVERNMENT MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 40: PUBLIC INSTITUTIONS MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 41: NORTH AMERICA AIR QUALITY IOT SENSORS MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 42: UNITED STATES MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 43: CANADA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 44: EUROPE AIR QUALITY IOT SENSORS MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 45: GERMANY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 46: UNITED KINGDOM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 47: FRANCE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 48: ITALY MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 49: SPAIN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 50: BELGIUM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 51: POLAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 52: REST OF EUROPE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 53: ASIA-PACIFIC AIR QUALITY IOT SENSORS MARKET, COUNTRY OUTLOOK, 2025 & 2034 (IN %)
FIGURE 54: CHINA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 55: INDIA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 56: JAPAN MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 57: AUSTRALIA & NEW ZEALAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 58: SOUTH KOREA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 59: THAILAND MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 60: INDONESIA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 61: VIETNAM MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 62: SINGAPORE MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 63: REST OF ASIA-PACIFIC MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 64: REST OF WORLD AIR QUALITY IOT SENSORS MARKET, REGIONAL OUTLOOK, 2025 & 2034 (IN %)
FIGURE 65: LATIN AMERICA MARKET SIZE, 2026-2034 (IN $ MILLION)
FIGURE 66: MIDDLE EAST & AFRICA MARKET SIZE, 2026-2034 (IN $ MILLION)
FAQ’s
FAQs
The global air quality IoT sensors market is valued at $2,490 million in 2026 and is projected to reach $8,030 million by 2034, growing at a CAGR of 15.75%. This global air quality IoT sensors market size and forecast reflects rising government regulations on air pollution monitoring, expanding smart city infrastructure, and growing low-cost air quality IoT sensors adoption across emerging economies.
The IoT air quality monitoring market growth is primarily driven by stricter environmental compliance monitoring systems mandates, rapid urbanization, the proliferation of smart homes and connected devices, and escalating concern over air pollution-related health outcomes. The integration of AI and IoT in environmental monitoring, through real-time air quality monitoring IoT solutions, is further accelerating adoption across both the public and private sectors.
Fixed air quality monitors currently command the largest share of the air quality monitoring sensors market. Their dominance reflects widespread deployment in government regulatory networks, industrial emission monitoring sensors applications, and smart city air quality monitoring infrastructure, where continuous, long-term operation and data reliability are non-negotiable requirements.
Smart cities air quality initiatives are significantly expanding the smart air quality sensors market by funding large-scale, hyperlocal IoT-based sensor network deployments in urban areas. Governments across Asia-Pacific, Europe, and North America are integrating environmental IoT sensors for pollution control into city management platforms, enabling real-time urban air pollution management and targeted policy responses.
Indoor air quality IoT sensors market growth in the commercial sector is being driven by rising adoption of wellness building standards such as WELL and LEED, growing employer focus on occupant health, and the integration of IoT air quality monitoring with HVAC systems. The role of IoT in pollution control within enclosed spaces has also gained permanent prominence following the heightened indoor air quality awareness generated during the pandemic era.
Asia-Pacific is the fastest-growing region in the global IoT air quality monitoring market, forecast to expand at a CAGR of 17.68% from 2026 to 2034. Severe urban pollution, ambitious smart city infrastructure investment, and strong government demand for environmental monitoring sensors market analysis-backed solutions are the defining drivers of this region’s leadership in the air quality IoT sensors market.
RELATED REPORTS
-
UNITED KINGDOM AIR QUALITY IOT SENSORS MARKET FORECAST 2026-2034
-
SOUTH KOREA AIR QUALITY IOT SENSORS MARKET FORECAST 2026-2034
-
JAPAN AIR QUALITY IOT SENSORS MARKET FORECAST 2026-2034
-
FRANCE AIR QUALITY IOT SENSORS MARKET FORECAST 2026-2034
-
GERMANY AIR QUALITY IOT SENSORS MARKET FORECAST 2026-2034
-
CANADA AIR QUALITY IOT SENSORS MARKET FORECAST 2026-2034
-
UNITED STATES AIR QUALITY IOT SENSORS MARKET FORECAST 2026-2034
-

GLOBAL REVERSE OSMOSIS COMPONENTS MARKET FORECAST 2025-2032
-

ASIA-PACIFIC REVERSE OSMOSIS COMPONENTS MARKET FORECAST 2025-2032
-

EUROPE REVERSE OSMOSIS COMPONENTS MARKET FORECAST 2025-2032